Business
Asian shares fall as Iraq crises escalate


TOKYO – Asian shares fell on Wednesday, echoing losses on Wall Street as concerns about escalating violence in Iraq eclipsed stronger U.S. economic data.
The gloom was likely to spread to European trading, where financial spreadbetters expected Britain’s FTSE 100 to open as much as 0.6 percent lower, Germany’s DAX down 0.5 percent, and France’s CAC 40 to weaken 0.7 percent.
“The bears look to be firmly in control and leaning heavily on that sell button as we expect to see a fairly large gap lower, given current volatility, on the open for the major European indices,” Capital Spreads trader Jonathan Sudaria wrote in a note to clients.
U.S. Secretary of State John Kerry urged leaders of Iraq’s autonomous Kurdish region on Tuesday to stand with Baghdad in the face of a Sunni insurgency, as security forces fought the rebels for control of the country’s biggest oil refinery.
A senior U.S. intelligence official said that the insurgents were “well positioned” to hold a broad swathe of territory captured in northern and western Iraq unless the Baghdad government can muster a counter-offensive.
MSCI’s broadest index of Asia-Pacific shares outside Japan fell about 0.4 percent, while Japan’s Nikkei stock average ended 0.7 percent lower.
In volatile U.S. trading on Tuesday, the S&P 500 closed down more than half a percent in its sharpest loss since June 12, after earlier setting a fourth record high in five sessions following upbeat U.S. economic data.
Sales of new homes surged 18.6 percent to a seasonally adjusted annual rate of 504,000 units in May, the highest since May 2008 and the biggest increase since January 1992. Separate data from the Conference Board showed its index of consumer attitudes rose to 85.2 in June from a downwardly revised 82.2 in May.
But U.S. Treasury prices shrugged off the brighter data and yields fell, with the benchmark 10-year rate dropping to 2.580 percent in Asia from its U.S. close of 2.586 percent.
A trio of Fed officials gave investors no reason to believe the central bank’s stance had changed. William Dudley, president of the New York Fed, said the U.S. central bank can wait to raise interest rates until mid-2015 without risking an undesirable rise in inflation.
San Francisco Fed President John Williams said on Tuesday that the U.S. economy is about two years from being “normal,” while Philadelphia Federal Reserve Bank President Charles Plosser said the economy continues to improve, making steady rather than exuberant progress.
With no help from U.S. Treasury yields, the dollar edged down about 0.1 percent to buy 101.89 yen, while the euro also inched lower to 138.71 yen.
“Overall, the yen looks better bid unless the Bank of Japan comes up with its next easing plan,” said Bart Wakabayashi, head of forex at State Street in Tokyo.
Despite the BOJ’s confidence that it will meet its inflation target next year without further stimulus, most economists still believe it will need to ease policy again by December, according to a Reuters poll published on Wednesday.
Japanese Prime Minister Shinzo Abe unveiled a package of measures on Tuesday aimed at boosting Japan’s long-term economic growth, though market impact was muted.
Against the greenback, the euro was slightly higher on the day at $1.3613.
The dollar index also consolidated at 80.293, solidly within the 80.000-81.000 range in which it has been stuck since May.
Crude oil markets were mixed as traders weighed the likelihood of supply disruptions from Iraq.
U.S. prices rose on a Wall Street Journal report that the government has allowed two companies to export ultra-light oil known as condensate, a first step that effectively loosens a 40-year ban on most U.S. crude exports.
U.S. crude for August delivery advanced about 0.6 percent to $106.69 a barrel, after spiking as high as $107.50 early in the session.
Brent crude for August fell about 0.2 percent to $114.24.
“Oil prices have been unusually stable in recent years, but events in Iraq are causing a reassessment of medium-term oil market fundamentals that we expect to translate into a phase of higher long-term prices and more volatile trading conditions,” strategists at Barclays said in a note to clients.
“Geopolitical risks have replaced China’s growth and Fed policy as the main concerns for investors,” they said.
Spot gold slipped about 0.4 percent to $1,312.40 an ounce, after spiking to a more than two-month high of $1,325.90 on Tuesday.
– REUTERS

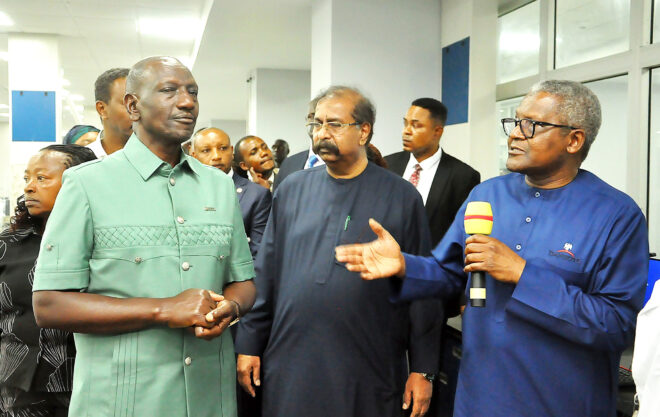
Kenyan President, William Samoei Ruto has described the Dangote Petroleum Refinery and Petrochemicals (DPRP) as “a masterpiece of science, engineering and art”.
He made the declaration following a tour of the world-class facility in Lagos, while reaffirming Kenya’s commitment to partnering with the Dangote Group on the proposed $17 billion East African Oil Refinery and Petrochemical Complex in Lamu.
President Ruto visited the refinery after attending the United Nations General Assembly (UNGA), noted that witnessing firsthand the scale, sophistication and operational excellence of the 700,000 barrels-per-day Dangote Refinery had strengthened his confidence in the East African refinery project.
READ ALSO: Dangote to Support Two Million Women with Refinery IPO Share Ownership
“Coming here and seeing it for myself, I can confirm that I have seen a masterpiece of science, engineering, and art. To my brother Aliko, congratulations. I always knew Nigerians to be very brave people and go-getters, but I did not anticipate that it was at this scale,” President Ruto said.
The Kenyan leader disclosed that preparations had been concluded for the ground-breaking ceremony of the East African refinery project in Lamu, which is expected to become a strategic regional asset for East Africa.
According to him, the refinery will drive industrialisation, create jobs, strengthen engineering and technical capacity, enhance energy security and promote regional economic integration.
“This is not a Kenyan refinery; it is going to be a regional refinery. We are positioning our continent as an emerging growth centre, and this project will help accelerate industrialisation, create jobs, enhance engineering capabilities and strengthen Africa’s economic competitiveness,” he stated bureaucratic bottlenecks to ensure efficient project execution.
“The Government of Kenya is 100 percent behind this project. We have secured the required land and are working to ensure that we spend our time building rather than navigating administrative delays,” he said.
The President further commended the leadership and commitment of Dangote Group President and Chief Executive, Aliko Dangote, highlighting his deep understanding of the refinery’s technical and operational processes.
“The detail with which Aliko Dangote understands this plant is remarkable. Unless you understand the details, you are unable to make the right decisions. That commitment to excellence is one of the reasons behind the success of this project,” he added.
Dangote Group’s Chief Strategy Officer, Aliyu Suleiman, disclosed, during the visit that the conglomerate generated approximately $17 billion in revenue during the first half of 2026 and is on course to achieve a record $36 billion in revenue for the full year, representing a 100 per cent increase over the $18 billion recorded in 2025.
“The revenues of the Group have grown significantly over the last five years. From $18 billion last year, we are on track to get to $36 billion this year. Our half-year revenue is already about $17 billion,” Suleiman said.
He attributed the strong performance to sustained investments across key sectors, including cement, sugar, fertiliser, petroleum refining, upstream oil and gas, and other strategic businesses.
Suleiman noted that Dangote Group’s growth ambitions are anchored on its Vision 2030 Strategy, aimed at expanding the company’s industrial footprint across Africa and creating globally competitive businesses on the continent.
“Between 2020 and 2025, the Group executed a capital expenditure programme of approximately $50 billion. Over the next five years, we intend to invest twice that amount as we accelerate our expansion across Africa,” he stated.
Suleiman emphasised that the proposed 700,000 barrels-per-day greenfield refinery and petrochemical complex in Lamu, estimated at approximately $17 billion, will be a cornerstone of the Group’s ambition to build a $100 billion African industrial enterprise.
“The East African refinery in Kenya is going to be a key component of our journey and our dream to get to $100 billion. It is going to be a major contributor,” he said.
He added that Dangote Group’s expansion plans span a broad range of sectors, including port infrastructure, gas infrastructure, LNG, upstream oil and gas, power generation, mining and other strategic industrial investments across Africa.
As part of preparations for the project, Dangote Group has signed a contract worth more than $450 million with Engineers India Limited (EIL) to provide project management consultancy and engineering, procurement and construction management services for the Lamu refinery and petrochemical complex.
The partnership builds on EIL’s experience and involvement in the successful development of the DPRP in Lagos. Once completed, the East African refinery is expected to process 700,000 barrels of crude oil per day, strengthening regional energy security and supporting industrial development across East Africa.
The Dangote Group is also progressing plans to expand the processing capacity of the DPRP in Nigeria from 700,000 barrels per day to approximately 1.4 million barrels per day through the addition of a new 750,000 barrels-per-day crude distillation unit.
The expansion is expected to further solidify Nigeria’s position as a leading exporter of refined petroleum products and enhance Africa’s energy self-sufficiency.
President Ruto’s visit and Dangote Group’s ambitious growth plans highlight the increasing impact of African-led investments in driving the continent’s industrial renaissance.
With record revenue growth, a robust investment pipeline, expansion of refining capacity in Nigeria and the planned development of the East African Oil Refinery in Kenya, Dangote Group is reinforcing its role as a key driver of Africa’s economic transformation, energy security, industrial development and regional integration.
Photo Caption: From Left – Kenya President, Dr. William Samoel Ruto; Group Vice President, Oil & Gas and Fertiliser, Dangote Industries Limited, Devakumar Edwin; and President/CE, Dangote Industries Limited, Aliko Dangote during the Kenya President’s Visit to Dangote Petroleum Refinery, Petrochemicals and Fertiliser Plant Lekki, Lagos on Friday 25th September 2026.

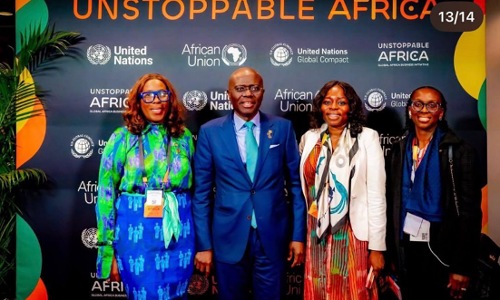
Lagos State Governor, Babajide Sanwo-Olu, has called for stronger international investment partnerships as he pitched Lagos as a strategic gateway for global investment into Africa.
Sanwo-Olu made the call while speaking at the Global Africa Business Initiative’s Unstoppable Africa 2026 in New York, where global business leaders, investors, policymakers and heads of government gathered to discuss ways of strengthening African businesses and expanding the continent’s economies.
The 2026 edition of the event was held on September 20 and 21 at the New York Marriott Marquis, on the sidelines of the opening of the 81st United Nations General Assembly.
SEE ALSO: ‘A Nation Cannot Escape the Bill’ — Atiku Questions Tinubu’s Third UNGA Absence
The governor highlighted Lagos’ large population, expanding market, infrastructure needs, entrepreneurial ecosystem and strategic position as key factors that create opportunities for investors seeking to participate in Africa’s economic growth.
Sanwo-Olu stressed that Lagos’ growing global relevance should translate into tangible benefits for residents through investments in infrastructure, transportation, healthcare, enterprise development and other sectors.
He said the state remained open to international capital, strategic partnerships and private-sector participation, with the goal of building partnerships capable of delivering measurable economic value across Lagos.
According to the governor, Lagos is pursuing a development agenda that combines long-term economic growth with efforts to address the everyday needs of its residents while creating an environment where businesses can establish, expand and compete.
A key feature of the governor’s presentation was the promotion of Invest Lagos, the flagship investment promotion initiative of the Lagos State Ministry of Commerce, Cooperatives, Trade and Investment.
The engagement followed the successful Invest Lagos 3.0 summit held in Lagos in June under the theme, “Lagos: The Business Gateway to Africa.”
The summit brought together global investors, policymakers, development institutions and business leaders to explore opportunities in infrastructure, manufacturing, technology, trade, finance and the creative economy.
Sanwo-Olu’s participation at Unstoppable Africa 2026 further provided an international platform for Lagos to showcase its investment opportunities and seek partnerships aimed at attracting global capital to the state.
The Nigerian equities market closed Friday’s trading session on a negative note, with the All-Share Index declining by 0.38 per cent to close at 252,113.41 points.
According to the Nigerian Exchange Group’s Daily Market Snapshot for Friday, September 25, 2026, equity market capitalisation stood at ₦163.65 trillion, representing a 0.01 per cent decline.
ALSO READ: NGX Invest Expands Primary Market Access with WhatsApp Subscription Channel
The fixed-income market capitalisation also fell by 0.01 per cent to ₦58.74 trillion, while the market capitalisation of Exchange-Traded Products (ETPs) declined by 2.15 per cent to ₦57.77 billion.
Meanwhile, the top five gainers were led by a stock that rose 10 per cent to close at ₦17.60, followed by CMFC, which gained 9.76 per cent to ₦3.26. Briscoe rose 9.74 per cent to ₦10.70, ABC Transport gained 9.68 per cent to ₦5.10, while Royal Exchange increased by 9.09 per cent to ₦1.08.
The figures were contained in the NGX Daily Market Snapshot released at the close of trading on Friday.

Ruto Hails DPRP “Masterpiece” as Dangote Group Accelerates African Expansion

Fire Breaks Out In Kubwa As Vehicle Crashes Into Gas Station

‘Obi Did Not Loot A Kobo’ — Obiaraeri Compares Peter Obi, Akpabio’s Records
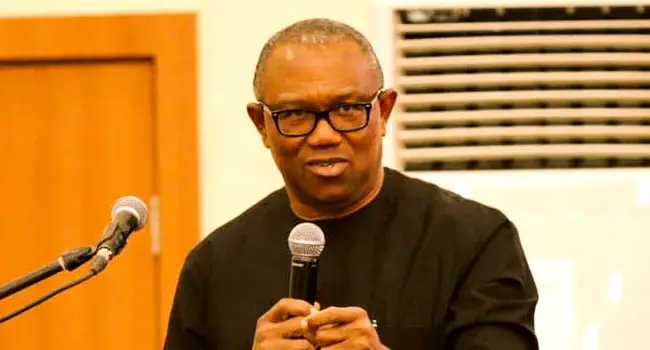
‘Where Is Nigeria’s President?’ — Obi Questions Tinubu’s Third Straight UNGA Absence

Africa Can’t Bear Global Burdens Without Equal Voice — Shettima

Bangkok Underwater: Nearly 4,900 Evacuated as Floods Hit Thailand Capital

Trump’s Family Unveils New Cryptocurrency Platform
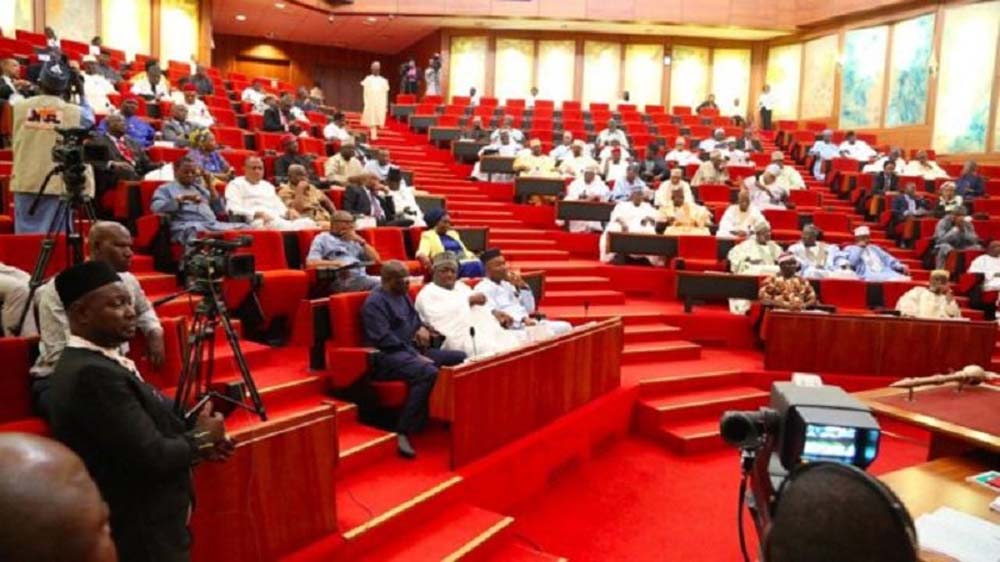
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart