Business
Europe stocks, euro gain after German morale jump


LONDON – European shares and the euro got a boost on Monday after German business morale unexpectedly rose in February, lifting investors out of a funk caused by a fall in Chinese home prices.
In Ukraine, where Moscow-backed Viktor Yanukovich was ousted from the presidency, the country’s dollar bonds rallied and the hryvnia currency fell, though there was scant impact on developed markets.
German Bund futures fell to the day’s low after the Ifo business climate index in Europe’s powerhouse economy rose to 111.3 from 110.6 last month, adding to the recent optimism over the economic recovery in the euro zone.
The euro edged up to $1.3769 after the data.
Earlier, shares in Asia fell and the Japanese yen rose as growth in Chinese home prices eased for the first time in 14 months – a sign Beijing’s campaign to tighten credit conditions may be starting to bite.
The FTSEurofirst 300 index .FTEU3 of top European stocks was up 0.13 percent, although a disappointing outlook from German carmaker Volkswagen (VOWG_p.DE) limited gains.
Asian shares excluding Japan .MIAPJ0000PUS fell 0.4 percent and most Asian emerging markets currencies were lower. Tokyo’s Nikkei index .N225 fell 0.2 percent as the yen, which is often sought in times of market stress, strengthened.
“Dollar-yen moves on risk aversion, and when Tokyo stocks are down dollar-yen is down, even if the reason is a drop-off in activity in its (Japan’s) major export market,” said Marshall Gittler, head of global FX strategy at IronFX Global.
Spanish government bond yields fell, approaching recent eight-year lows after Moody’s raised Spain’s credit rating in a further endorsement of Madrid’s efforts to revive an economy once at the sharp end of the euro zone debt crisis.
Moody’s upgraded by one notch to Baa2 with a positive outlook. Spain’s 10-year government bond yields last traded 2.6 basis points lower at 3.53 percent.
“It’s certainly reinforcing positive sentiment in Spain. Moody’s has recognized not only the economic recovery but also the structural reforms … and the fact that they’re sticking to their guns on the fiscal deficit,” said Nick Stamenkovic, bond strategist at RIA Capital Markets in Edinburgh.
The yen was up 0.1 percent at 102.37 to the dollar and slightly stronger versus the euro.
China shares sank to a two-week low, dragging Hong Kong markets down, as property and banking counters slipped on mainland news reports that stoked fears banks have stopped extending loans to property-related companies.
“I would get out of interest rate-sensitive sectors. It’s very hard to navigate right now with policy risk on the rise,” said Hong Hao, Hong Kong-based chief equity strategist at Bank of Communication International.
Data on Monday showed the pace of the rise in Chinese home prices slowed in January for the first time in 14 months, suggesting the government’s efforts to cool the market were having an effect.
YUAN FALLS
The Chinese yuan fell, extending its worst weekly performance in more than two years after the People’s Bank of China set its daily midpoint lower for a fifth session.
On Wall Street on Friday, stocks were off slightly on options-related expirations.
Group of 20 finance ministers and central bankers committed to spurring faster global growth at a two-day meeting in Sydney over the weekend.
The final communiqué said the G20 would increase investment and employment, generating more than $2 trillion in additional output over five years while creating tens of millions of new jobs.
On the commodities front, Brent crude added about 0.2 percent to $110.01 a barrel. Gold added about 0.2 percent to $1,330.80 an ounce after it marked a third straight week of gains.
– REUTERS

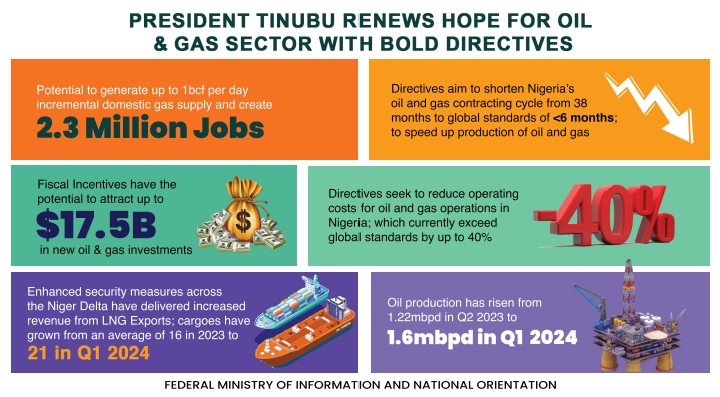
Nigeria produced a daily average of 1.687 barrels of crude oil and condensate in October 2026, and met its OPEC quota for the sixth consecutive month.
Data from the Nigerian Upstream Petroleum Regulatory Commission (NUPRC) showed that in strict crude oil terms (excluding condensate), the country produced an average of 1.51mbpd in October.
This is 101 percent of the 1.5mbpd quota set by OPEC.
READ ALSO: NLNG, NCDMB Endow Research Chairs in Six Nigerian Varsities with $9m
The data, released on Wednesday, also shows that single-day production hit a peak of 1.79 million barrels, while the lowest for the month under review stood at 1.60 million bpd.
The crude oil data (excluding condensate) shows that Nigeria has met its assigned OPEC quota for six straight months, producing 1.53mobpd in May; 1.55mobpd in June; 1.51mobpd in July; 1.5mobpd in August, 1.53mobpd in September and 1.51mobpd in October.
On a month of month basis, however, production dipped by 1.7 percent.
The NUPRC attributed the stable performance in recent months to an enhanced operational stability, supported improved production uptime and crude evacuation efficiency.
The sustained growth recorded in October reflects the continued commitment of operators and industry stakeholders towards improving operational efficiency, maintaining asset integrity, and enhancing production reliability across the Nigerian upstream petroleum sector.
A breakdown of the daily average crude oil and condensate production by terminals/streams during the review month shows that Forcados Terminal accounted for 318.49kbpd while Bonny comes second with 311.02kbpd.
Qua Iboe Terminal recorded an average production of 173.97kbpd of crude oil and condensates while Escravos Oil Terminal posted a daily average of 134.67kbpd.
Bonga ranked as the fifth highest producing terminal, recording an average of 106.65kbpd of crude oil and condensate.
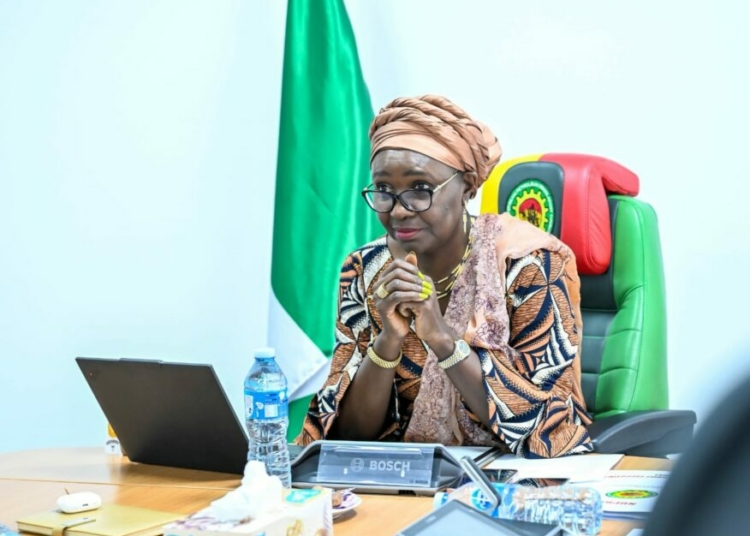
A total of 595 well re-entries and 145 new well-drilling operations, alongside 39 Field Development Plans (FDPs) have been approved in the first 10 months of 2026, as Nigeria intensifies efforts to ramp up crude oil production and attract fresh investments.
In addition, the Nigerian Upstream Petroleum Regulatory Commission (NUPRC) has sanctioned 740 drilling-related operations in the same period, as Nigeria’s total rig count rose to 100, with 46 currently active in drilling operations.
These details were made public during the management session of the 44th Annual International Conference and Exhibition of the Nigerian Association of Petroleum Explorationists (NAPE) in Lagos on Tuesday, by the Chief Executive (CE), NUPRC, Oritsemeyiwa Eyesan.
The conference is held under the theme, “Energy Security in an Era of Global Disruption: Positioning Nigeria for Resilience, Competitiveness, and Prosperity.”
The approvals, which underscore increased regulatory activity in the upstream petroleum sector. Eyesan, who was represented by the Deputy Director, Basinal Administration, NUPRC, Ahmad Abdullahi, said the increased approvals reflected improvements in the Commission’s regulatory processes, particularly the time required to grant operational clearances.
READ ALSO: Adeleke Clarifies Osun Debt Profile
According to her, faster approval processes have reduced delays and the additional costs incurred by operators while waiting for regulatory authorisation to execute projects.
“Year to date, about 39 FDPs have been approved. About 145 new well-drilling approvals granted. Year to date, about 595 well re-entry approvals were granted.
That goes to tell that as a commission, we have improved our approval time level, which again reduces costs that are being wasted or for projects to continue to wait for approval,” she said.
She explained that the Commission’s priority was to ensure that regulatory approvals translated into increased production and adequate energy supply.
“From the regulator’s perspective, to ensure that our energy security is not threatened, we must ensure that we approve Field Development Plans and new well-drilling applications to meet our production targets and guarantee energy availability,” Eyesan stated.
On drilling activities, the NUPRC boss said Nigeria’s rig count had increased by more than 300 per cent compared with the level recorded in 2021, reflecting renewed activities in the upstream industry.
“We have more than 100 rigs in country. About 46 rigs are actively involved in drilling year to date. If you compare this with maybe what we had in 2021, you will see that you have more than about 300 per cent increase,” she said.
Eyesan attributed the growth in investment activities to improved regulatory certainty, noting that investors were more willing to commit capital when they had confidence in the policy and operating environment.
She also identified the Petroleum Industry Act (PIA) as a major factor in rebuilding investor confidence, particularly in the acquisition of seismic data required for oil and gas exploration.
The NUPRC chief disclosed that multi-client seismic companies had invested more than $100 million in seismic data acquisition in Nigeria within three years of the enactment of the PIA.
“Based on our record, in the last three years, from the enactment of PIA, multi-client companies have invested more than $100 million in acquiring seismic data in Nigeria,” she said.
The investments are expected to deepen geological understanding of the country’s sedimentary basins, improve exploration decisions and support the discovery of additional hydrocarbon reserves.
On efforts to tackle crude oil theft and improve security across the industry, Eyesan said the Commission had introduced initiatives, including the Advanced Cargo Declaration programme and coordinated surveillance operations involving the Nigerian National Petroleum Company Limited (NNPC), private security operators such as Tantita Security Services and the Nigerian Navy.
She said the Commission’s responsibility went beyond punishing errant operators and perpetrators of oil theft.
According to her, the broader objective was to establish an operating environment in which legitimate crude oil production would be more profitable than crude oil theft.
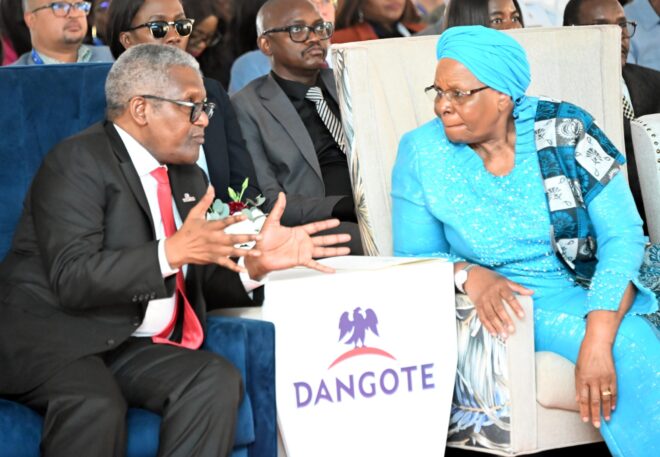
President/Chief Executive, Dangote Industries Limited, Aliko Dangote, has declared that over 90,000 people are expected to be working at the group’s petroleum refinery & petrochemicals and fertiliser operations in Lagos next year.
This is as the group accelerates investments to create jobs, strengthen industrial production and transform agriculture across Africa.
Dangote, who disclosed this in an interview, also unveiled plans to establish 20 fertiliser blending plants in strategic locations across the continent to improve farmers’ access to essential inputs and support year-round supply. The projects form part of an investment programme that could reach $65 billion over four years, spanning refining, fertiliser, petrochemicals, power, pipelines and other businesses.
“The refinery expansion is huge. By next year, we expect to have almost 90,000 people working on the refinery and fertiliser projects in Lagos,” he said.
READ ALSO: Shell Commends Oil Industry Reforms as Key to Unlocking More Barrels
Dangote said creating opportunities for Africa’s youthful population was a central motivation for the group’s expansion, stressing that the continent needed more factories and greater domestic production to meet its growing needs. “My biggest concern is job creation in Africa. We have a very youthful population, and we are not creating enough jobs. We must push harder to create opportunities and keep our young people productively engaged,” he said.
The refinery expansion will add another 700,000 barrels per day of processing capacity, taking the planned total to about 1.4 million barrels per day, alongside additional petrochemical facilities and infrastructure. Beyond energy, Dangote outlined a fertiliser expansion programme designed to help turn Africa’s agricultural potential into greater production, more reliable food supplies and economic opportunities.
“We also plan to establish 20 blending plants in strategic locations across Africa. We intend to begin mining potash and phosphate in Congo-Brazzaville very soon,” he said.
He disclosed that the group was working towards nine million tonnes of urea capacity, with plans for 1.2 million tonnes of diammonium phosphate, DAP, and one million tonnes of NPK blending capacity in Lagos. Dangote said the objective was to ensure that farmers in countries hosting the group’s operations, as well as neighbouring markets, could obtain fertiliser when needed, without the uncertainty associated with lengthy import and delivery processes.
“What we want is for the countries where we operate, and their neighbours, to have fertiliser available 365 days a year. Farmers should be able to buy it when they need it, without worrying about supply,” he said.
Citing Ethiopia, he explained that fertiliser imports had to pass through Djibouti before being transported inland, creating logistical challenges that could leave supplies arriving after the planting season. “With local production, the fertiliser will be available there. We will also have one million tonnes of NPK capacity attached to the project,” he said.
Dangote linked the programme to his determination that Africa should build the capacity to meet its own agricultural input requirements, rather than remain vulnerable to disruptions in international markets. “At the beginning of the Russia–Ukraine crisis, the African Union went to Russia to plead for fertiliser. I said then that, within four years, Africa should never again have to go anywhere to beg for fertiliser,” he said.
He expressed confidence that sufficient access to gas would enable a much larger expansion in fertiliser production. “If Africa needs 30 million tonnes and we can secure enough gas, we can produce and supply it,” he said. “Africa has an enormous agricultural advantage. We must lead the effort to turn that opportunity into a major agricultural transformation.”
The group’s wider investment programme includes an initial ambition to develop 10,000 megawatts of power with some African countries and increase cement capacity to 100 million tonnes. Dangote said reliable electricity was essential to industrial growth, enabling African countries to process their raw materials, retain more value within their economies and create opportunities for their people. He disclosed that approximately $50 billion of the planned investment would go into existing businesses, while another $15 billion would be directed towards new ventures, including projects yet to be announced. The programme would be financed through a combination of free cash flow, internally generated equity and debt, he said.
Dangote urged African investors to take the lead in developing the continent, arguing that substantial domestic investment would encourage international capital to follow.
“I am tired of hearing about ‘potential’. We have been talking about Africa’s potential for decades. But Africans themselves must invest in their continent,” he said. “What gives other investors comfort and confidence is seeing us put our own money on the table. That is what we are trying to do. We are demonstrating that we are serious.”
He argued that sustained investment by African businesses was essential to unlocking the continent’s industrial and agricultural opportunities, while giving international investors the confidence to participate.
“Governments are always calling for foreign investors. But what attracts a foreign investor is a domestic investor,” he said. “We must demonstrate that we are doing something substantial in Africa so that others can join us.”
Photo Caption: Group President/Chief Executive, Dangote Industries Limited, Aliko Dangote (left), in conversation with the President of the Republic of Namibia, H.E. Dr Netumbo Nandi-Ndaitwah, during the official launch of the Dangote Namibia Tank Farm and Regional Pipeline Investment in Walvis Bay, Namibia, recently.

NUPRC Screens 28 Wells Over Rivers Gas Seepage, Identifies Three as High-Risk

IGP Disu Charges Newly Promoted AIGs, CPs on Accountability, Strategic Leadership

Tinubu Moves to Fulfil Promise as Shettima Arrives Calabar for Bakassi Seaport

How Ogun Driver Allegedly Stole Boss’s ₦45m Lexus and Plotted to Sell It for ₦10m in Cotonou

Tinubu’s SA Preaches Harnessing Oil Production for Industrial Growth
RMAFC Reopens Oil Wells Dispute, Begins Verification in Nine States

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart