Energy
Iran’s Threat Pushes Brent Over $90

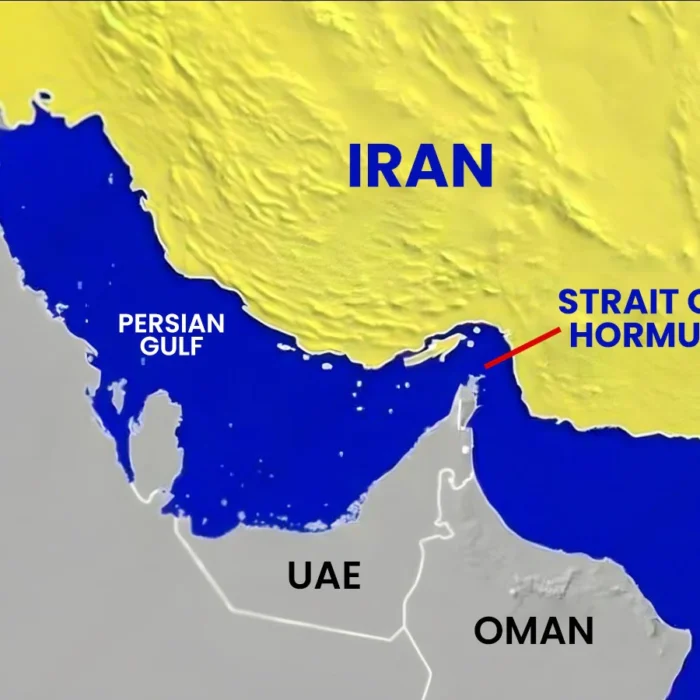
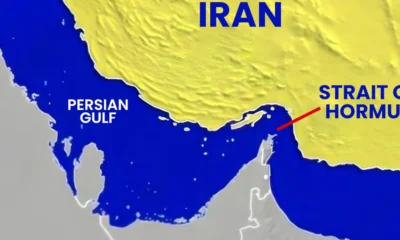
Brent crude closed above $90 per barrel on Monday as Iran threatened to launch a military offensive in the Strait of Hormuz if diplomatic efforts to end its war with the United States fail.
The benchmark Brent crude was quoted at $90.53 per barrel as of Monday evening, gaining $2.01, or 2.27 per cent, according to oilprice.com. US West Texas Intermediate crude also climbed to $84.25 per barrel, up $1.85, or 2.25 per cent.
According to Reuters, the rise followed renewed tensions around the strategic Strait of Hormuz after a senior Iranian official told the news agency that Tehran had shifted its policy from defensive to “fully offensive” because of a deadlock in efforts to secure a permanent end to the war.
The official said Iran was prepared to take military action in the Strait of Hormuz if diplomatic efforts failed. “Iranian entities must be prepared to escalate tensions in the Strait of Hormuz and wider region, as Iran will be ready to make decisions and take action on difficult decisions,” the official told Reuters.
READ ALSO: DPRP Receives $1bn Guarantees for Upcoming IPO
He added that Tehran would conduct a “timely and precise” military attack to break the United States naval blockade if diplomacy failed.
The development threatens to further disrupt tanker movements through Hormuz, a key global energy corridor, at a time when efforts to restore oil traffic through the waterway have stalled.
According to Reuters, progress towards peace talks and the resumption of oil tanker traffic through the Strait of Hormuz has ground to a halt, with neither side showing signs of moving towards an end to the conflict.
The latest escalation came on the day Iran and the United States were expected to reach a final agreement under a memorandum of understanding signed in June.
The June 17 memorandum provided a 60-day timeframe for Washington and Tehran to reach a broader agreement concerning Iran’s nuclear programme and US sanctions.
The interim agreement, which called for the “immediate and permanent termination of military operations on all fronts”, however, quickly collapsed over disagreements concerning control of the Strait of Hormuz.
The waterway, which is shared by Iran and Oman, is a major route for global energy supplies. It was reported that about a fifth of global oil and liquefied natural gas flowed through the strait before the war.
Tehran maintains that the June agreement gave it the right to manage the waterway, while Washington rejected that interpretation.
The dispute subsequently contributed to the resumption of hostilities, with Iran firing on vessels it said were attempting to sail through the strait using an unauthorised route.
US President Donald Trump subsequently declared on July 7 that the agreement was over.
The Iranian official told Reuters that Tehran had now given the United States only a short period to implement all the provisions of the agreement before further negotiations could take place.
“Within the short period of a few weeks set by Iran, all the agreement’s provisions must be implemented by the U.S. This is a precondition for further negotiations with the US,” the official said.
Mediators are expected to communicate Iran’s deadline to Washington and other regional countries. Iran is also separately negotiating with Oman over the management of the Strait of Hormuz, with Tehran saying the two countries are close to an agreement despite slow progress.
The situation was further complicated by Trump’s warning to Oman during a phone interview with Fox News on Monday. “If Oman gets in the way, we’ll bomb the shit out of them,” Trump said, according to Reuters.
Earlier, Trump said Iran should surrender, telling Fox News that Tehran “should put up the white flag of surrender”. The renewed threats have heightened concerns over the security of shipping through Hormuz and helped push crude prices higher on Monday.
The price movement also comes after oil had traded below the $80 mark earlier in the month amid expectations that tensions around the waterway could ease. Monday’s Brent price of $90.53 therefore represented a fresh rise above the $90 threshold, while WTI stood at $84.25 per barrel.





The Special Adviser to the President on Energy, Olu Verheijen, has called for Nigeria to translate increased oil and gas production into broader economic development, saying the country must use its energy resources to strengthen industries, create jobs and improve living standards.
Verheijen said the next phase of Nigeria’s oil and gas development should go beyond increasing production figures to building national productive capacity, stressing that investment recovery must deliver tangible benefits across the economy.
She made the call in an address titled, “Unlocking more barrels: From recovery to national renewal” at the 44th annual international conference and exhibition of the Nigerian Association of Petroleum Explorationists (NAPE), where she outlined exploration, local capacity development and technology as key priorities for the sector.
Her comments came at a time Nigeria’s oil production has recorded steady improvement with the country meeting OPEC production in the last six months.
READ ALSO: RMAFC Reopens Oil Wells Dispute, Begins Verification in Nine States
According to the presidential aide, Nigeria has made progress in restoring investor confidence, but must now translate improved investment conditions into higher production, stronger revenues and economic opportunities.
Using the IMA gas field as an example, Verheijen highlighted the lengthy delays that had constrained the development of Nigeria’s resources. Discovered in 1973, the field reached a final investment decision in September 2026, more than five decades after its discovery.
She said the delay reflected weaknesses in the country’s investment environment rather than a lack of resources, including unclear responsibilities, slow contracting processes, uncompetitive economics and unreliable access to customers.
Verheijen attributed efforts to address these challenges to the policy direction of President Bola Ahmed Tinubu, saying the government had worked with ministries, regulators, the Nigerian National Petroleum Company, operators and investors to improve the investment proposition.
She explained that fiscal reforms were designed to reward production, protect existing revenues and provide incentives suited to different resources. In the gas sector, she said, incentives had to be supported by commercial arrangements and access to customers to make projects financially viable.
She cited the opening of opportunities for third-party gas supply to Nigeria LNG as part of efforts to improve the commercial prospects of gas developments.
Verheijen noted that Ubeta and Bonga North reached final investment decisions in 2024, while IMA had since joined the list of projects moving into execution.
She said the government’s responsibility was to ensure the projects were delivered while improving output from existing assets.
On exploration, the presidential adviser said Nigeria needed to replenish its resource base through credible exploration programmes, reliable geological data and development plans that considered infrastructure and markets from the outset.
She added that improved reservoir understanding, infill drilling and enhanced recovery could support near-term production, but should complement rather than replace new discoveries and developments.
Verheijen also urged operators to present clear investment proposals, including the capital, technical capacity and execution plans required to develop their assets.
On local capacity, she said the growing role of Nigerian independent oil companies presented opportunities to expand onshore and shallow-water production, while international companies focused on deepwater and integrated gas projects.
However, she stressed that Nigerian ownership must be matched by strong governance, sound finances, technical competence and responsible environmental and community practices.
“Local content should leave Nigeria more capable after a project than before it began,” she said, adding that the policy should produce engineers capable of leading major developments and fabrication companies able to compete internationally.
She also called for greater adoption of technology, including improved seismic interpretation, reservoir modelling, digital monitoring and methane measurement, to reduce operating costs, improve recovery and make operations safer.
Verheijen said artificial intelligence could strengthen the work of industry professionals but would not replace the need for reliable data and sound technical judgement.
She further argued that oil, gas and power should be treated as parts of one national economic strategy, noting that dependable energy supply was essential for manufacturing, agriculture and job creation.
According to her, oil production can support export earnings and public finances, while gas can supply industries, electricity generation and export markets. However, she warned that gas projects would only be commercially viable if suppliers had confidence that customers would pay.
She identified the resolution of legacy debts in the power sector, improved metering and targeted support for vulnerable electricity consumers as necessary measures to strengthen the energy value chain.
The adviser said Nigeria must also prepare to compete for investment against emerging oil and gas destinations in Africa and elsewhere, adding that temporary disruptions in other producing countries should not form the basis of its investment strategy.
She urged government and industry to ensure that reforms translated into measurable improvements in the lives of Nigerians.
“A family struggling with the cost of living cannot spend a forecast. A business cannot run on a policy announcement,” she said, calling for sustained delivery and accountability.
Verheijen said the country’s progress should continue to be measured by reserves, revenues, reliability and responsibility, adding that the ultimate objective was to build an industry capable of developing Nigeria’s resources and supporting a more productive economy.
To bridge Nigeria’s estimated $200 billion gas infrastructure funding gap over the next decade, the Midstream and Downstream Gas Infrastructure Fund (MDGIF) is stepping up efforts to attract private sector and foreign investments.
This was revealed during the commissioning of five Compressed Natural Gas (CNG) daughter and last-mile retail stations established by Ibile Oil and Gas Corporation (IOGC) in collaboration with MDGIF, in Lagos, the Executive Director of MDGIF, Oluwole Adama.
According to Adama, the scale of investment required to develop Nigeria’s gas infrastructure was beyond the financial capacity of the fund, making partnerships with Development Finance Institutions (DFIs), Foreign Investment Funds (FIFs) and private sector players critical to achieving the country’s gas development objectives.
He maintained that the MDGIF is positioning itself as a catalytic institution to de-risk investments, unlock additional financing and encourage businesses to commit capital to infrastructure projects across the gas value chain.
READ ALSO: Shettima Visits Oba of Benin Ahead of APC Presidential Campaign Rally in Edo
He explained that the fund’s mandate went beyond providing direct financing, stressing that its primary responsibility was to create an enabling environment for investments in gas processing plants, gas capture projects, pipelines, CNG refuelling stations, terminals and storage facilities.
“An estimate a few years ago put the investment required to close Nigeria’s gas infrastructure deficit at about $20 billion annually for 10 years. That is approximately $200 billion. What MDGIF can do is limited in terms of the resources available to us, so we see ourselves as a catalytic agent,” he said.
Adama disclosed that the fund had secured a $500 million debt facility and was pursuing additional financing arrangements, including risk guarantees, to attract more investors into the sector.
He said MDGIF had engaged the United States Development Finance Corporation (DFC) on opportunities to mobilise further funding for gas infrastructure projects in Nigeria.
The objective, he explained, was to reduce investment risks, particularly at the early stages of project development, and unlock larger pools of capital from international financiers and private investors.
Adama also disclosed that the fund had supported more than 25 infrastructure projects, with about 18 already commissioned in less than two years.
He noted that the development of gas infrastructure required considerable time, involving project design, engineering, equipment manufacturing, shipping, port clearance and construction, adding that Nigerians should recognise that such investments could not be delivered overnight.
Earlier, the Minister of State for Petroleum Resources (Gas), Ekperikpe Ekpo, said the Federal Government was intensifying efforts to increase domestic gas utilisation and expand infrastructure to make natural gas more accessible to Nigerians.
He disclosed that domestic gas supply had increased from about 1.6 billion cubic feet to 2.2 billion cubic feet daily, attributing the improvement to growing investments in the sector and the government’s policy direction under President Bola Tinubu.
According to him, the government is working with private sector investors to address infrastructure and supply challenges, noting that increased demand for gas would continue to attract investments into the sector.
The minister stressed that the government alone could not establish the infrastructure required to deepen gas utilisation, making private sector participation indispensable.
He commended MDGIF for its catalytic role in supporting infrastructure development and attracting investments into the gas sector.
Also speaking, the IOGC Managing Director and Chief Executive Officer, Tayo Gbajumo, said the corporation was expanding its CNG infrastructure in Lagos as part of its mandate to establish 15 stations across the state.
He disclosed that five additional stations had been commissioned in Abule-Egba, Ajah, Oko-Oba, Idimu and Ogolonto, while the remaining six were at various stages of completion and expected to be commissioned by the first quarter of 2027.
Gbajumo said the facilities were designed to improve access to affordable energy, reduce transportation costs for businesses and households, and support the adoption of CNG-powered vehicles.
The five stations, supported by MDGIF, have a combined storage capacity of 45,640 standard cubic metres and are expected to serve approximately 8,400 vehicles daily at full capacity, according to Adama.
Gbajumo commended the Federal Government, the Lagos State Government and MDGIF for their support, saying the partnership demonstrated the importance of collaboration between government institutions and industry stakeholders in expanding gas infrastructure.
In a confirmation of expectations that more policy adjustments will not occur until 2027, OPEC+ oil-producing countries have voted to keep December production targets steady.
The OPEC+ alliance, yesterday, agreed in principle to keep its combined December oil output targets unchanged at 30.9 million barrels per day (bpd), with Saudi Arabia’s individual target held at 10.5 million bpd.
The resolution was passed at a virtual meeting attended by seven core OPEC+ members- Saudi Arabia, Russia, Iraq, Kuwait, Algeria, Kazakhstan and Oman.
This is as the group continues to struggle with export disruptions from the Middle East crisis, while Gulf members have been boosting exports that have been disrupted for months by the conflict, most are still pumping well below their targets.
OPEC+ comprises the Organisation of the Petroleum Exporting Countries (OPEC) and allies including Russia. Only the seven members — plus the United Arab Emirates (UAE) until it quit OPEC in May — have been involved in monthly output decisions in recent years.
READ ALSO: Gas Infrastructure Fund Sets Terms for Indigenous Access to Funding
All members of the 21-country group are due to meet on November 29, when it will decide 2027 quotas.
“Today’s decision was the easy one,” said Jorge Leon, an analyst at Rystad. “The much more important test comes at the November 29 ministerial meeting, when OPEC+ will decide its 2027 production framework.”
Oil prices jumped more than two per cent on Friday, with Brent crude settling at almost $118 a barrel, the highest since April, as traders braced for a potential escalation in the Iran war after the US midterm elections.
“OPEC+ faces an extremely difficult call for 2027,” Leon added. “The group has to plan around huge uncertainty over the US-Iran war, the pace of recovery through the Strait of Hormuz, and the size of the surplus that could emerge once disrupted barrels return.”
The seven members have been boosting output targets for much of 2026 and in September completed the phased rollback of a 1.65 million-barrel-per-day supply cut first agreed in 2023. At earlier meetings, they kept the targets steady for October and November.
OPEC+ still has one more layer of production cuts of about two million bpd covering most members through the end of 2026.
The group needs to complete a review of members’ production capacity during the fourth quarter before setting the 2027 baselines that will determine future quotas and shape plans to unwind those cuts, sources have said.
The Iran war has disrupted projects to expand capacity across the Middle East, throwing estimates of future production potential into uncertainty, Reuters reported in October. As a result, the review is now expected to be completed by mid-November.
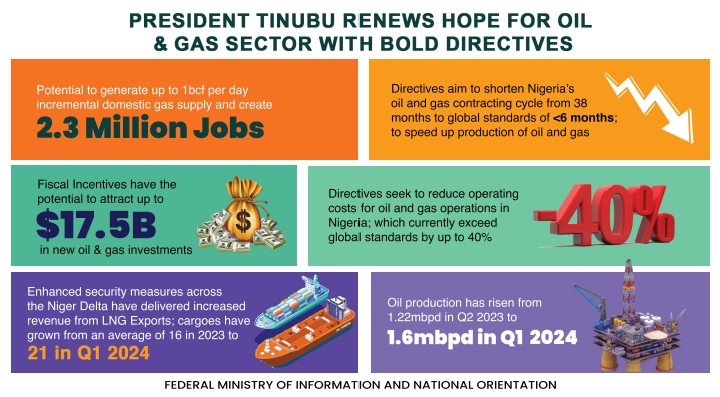

Tinubu’s SA Preaches Harnessing Oil Production for Industrial Growth
RMAFC Reopens Oil Wells Dispute, Begins Verification in Nine States

NNPC JV Deploys Football for Peace Amongst Rivers Host Comms
MDGIF Woos Foreign Investors for Nigeria’s $200bn Gas Infrastructure
Shettima Visits Oba of Benin Ahead of APC Presidential Campaign Rally in Edo

2027: Ika Artisans Pledge Five-Position Support for APC After Morka’s Engagement

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart