Business
Blue Economy: NIMASA, Ministry Ink Performance Pact

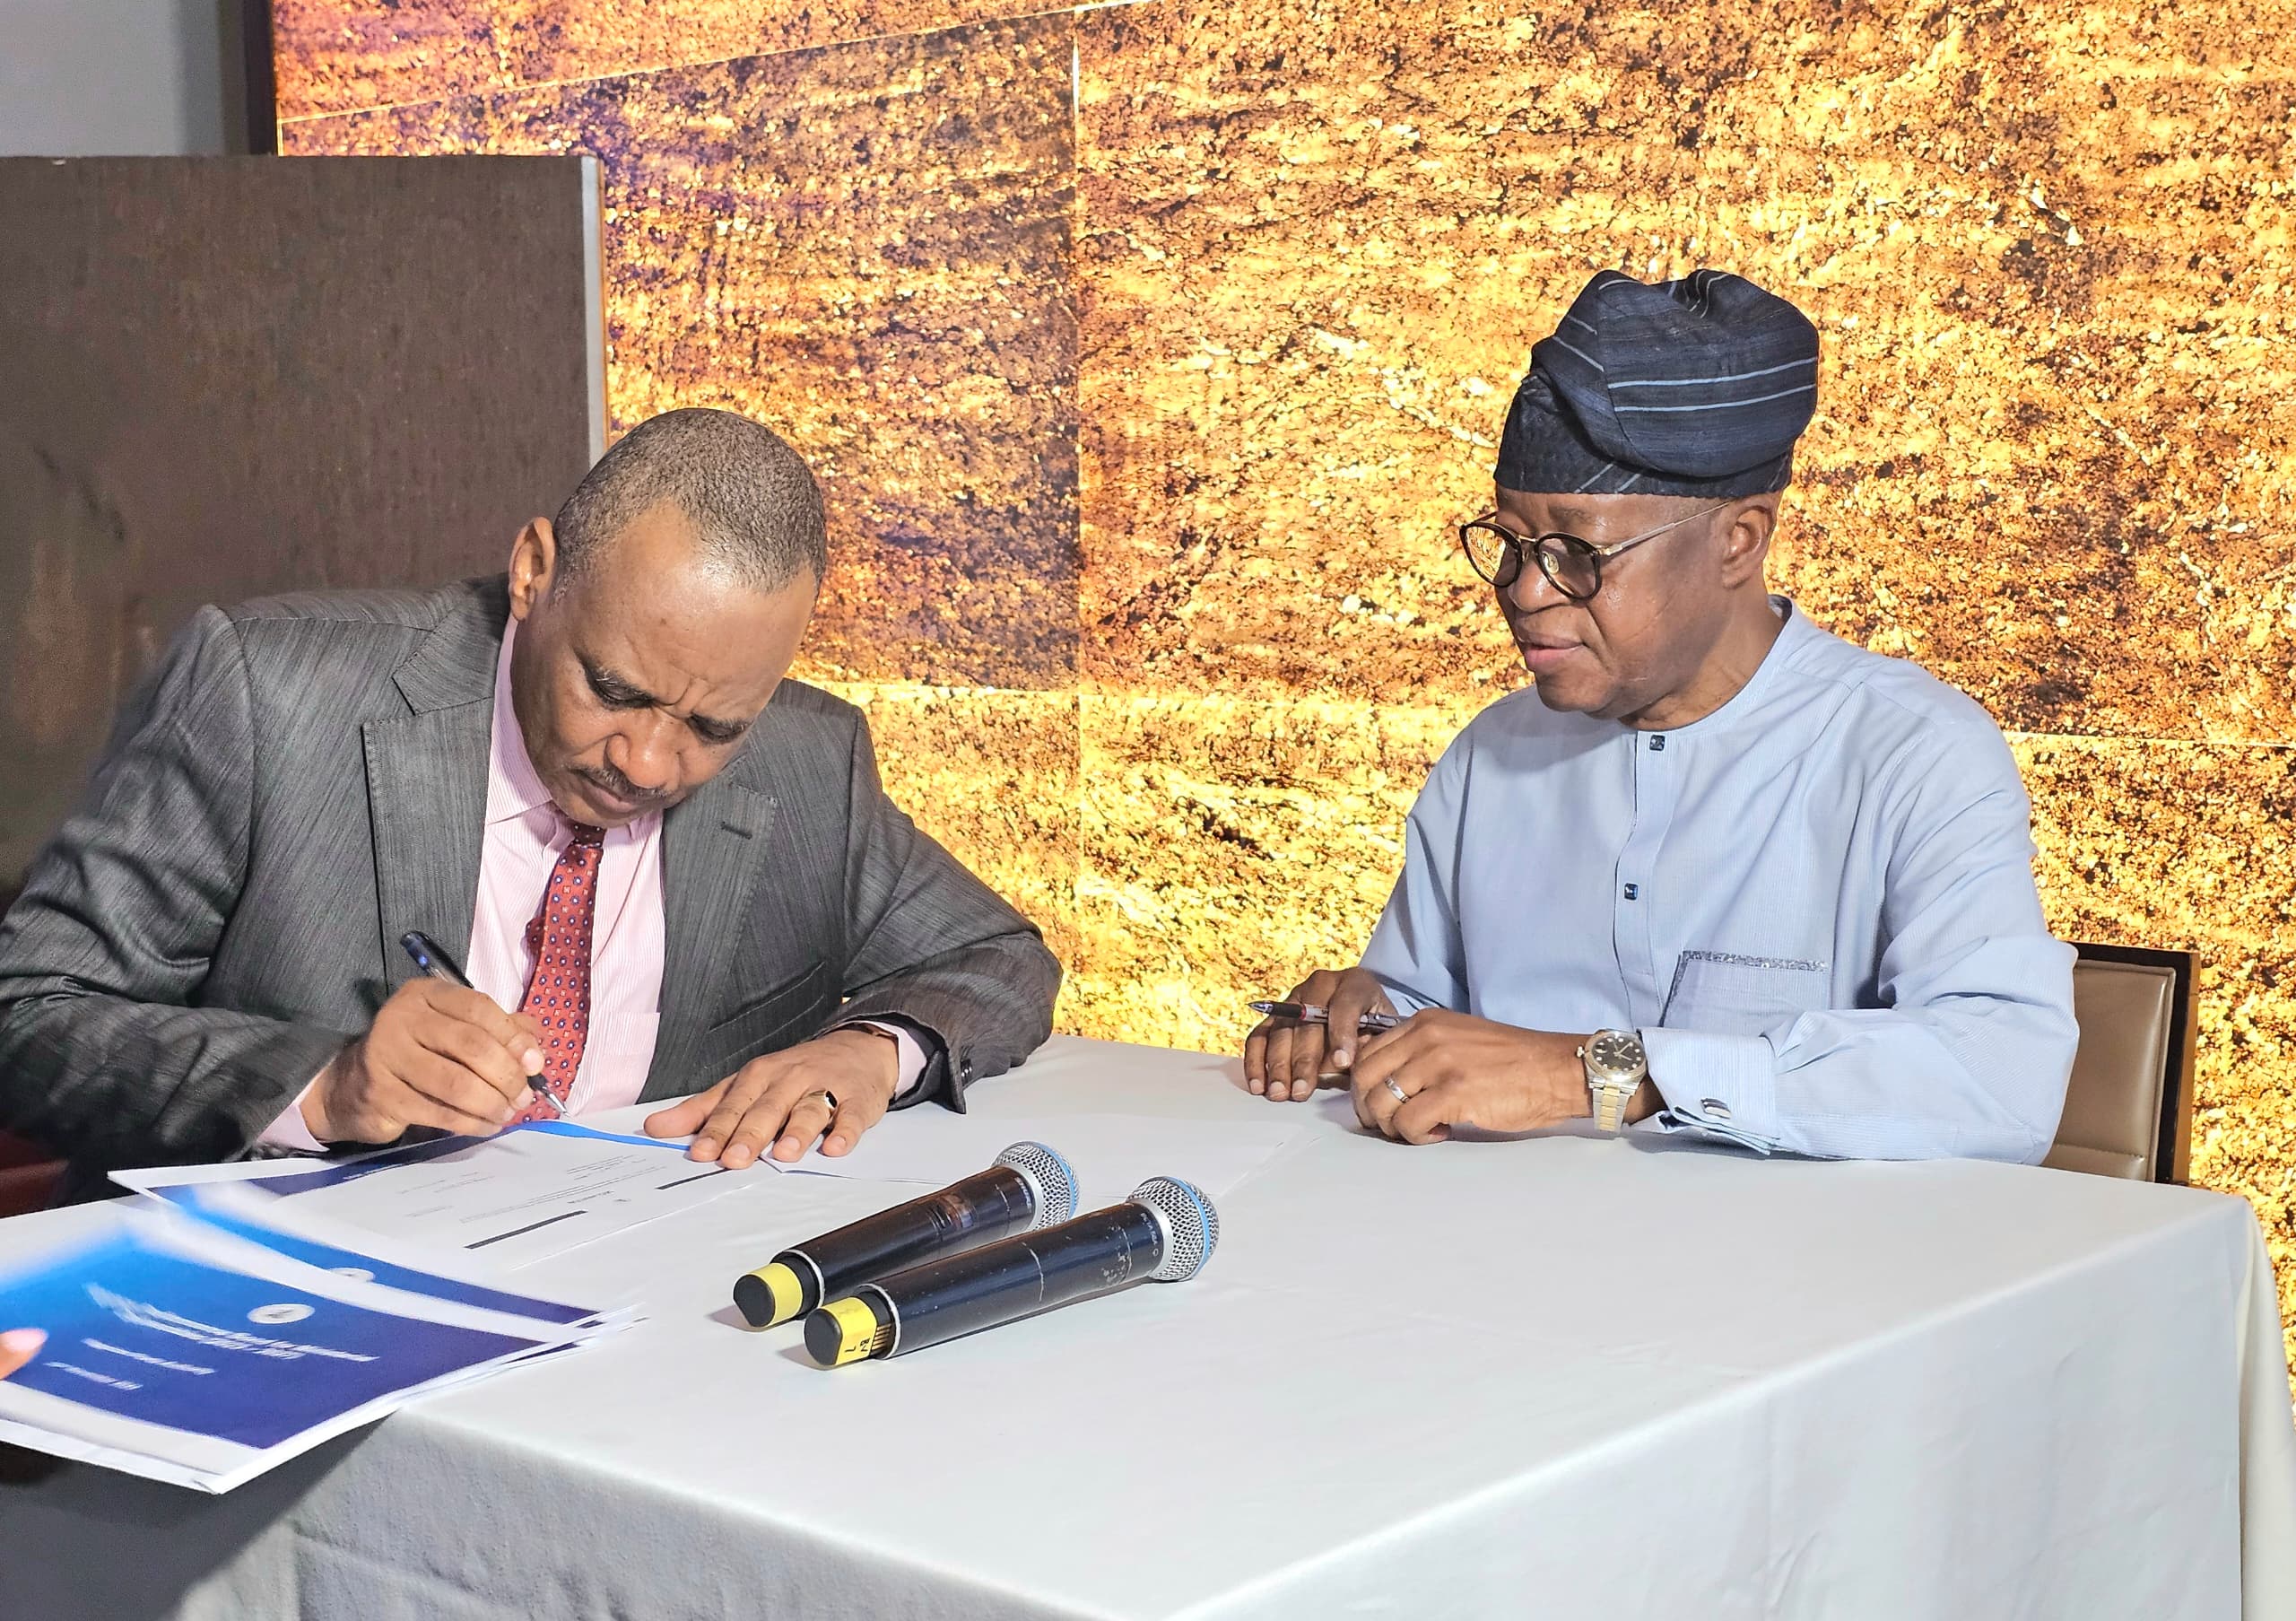
The Nigerian Maritime Administration and Safety Agency (NIMASA) and the Ministry of Marine and Blue Economy have signed a performance bond for ‘Ministerial Deliverables’ from 2023-2027.
Biztellers reports that the Director General, NIMASA, Dr Bashir Jamoh, personally signed the bond in Lagos, on Thursday in the presence of the Minister of Ministry of Marine and Blue Economy, Adegboyega Oyetola.
The pact was part of the Ministerial retreat in Lagos, where the Oyetola urged the management of the Agency to key into the vision of the Ministry in achieving its mandate as set by President Bola Ahmed Tinubu.
He said, “This document will drive our carefully thought out strategies and robust policies in line with the renewed hope Agenda of Mr President H. E. Asiwaju Bola Ahmed Tinubu GCFR.
“Our mandate is to institutionalise Blue Economy as an important pillar for economic sustenance and growth diversification.”
On his part the NIMASA DG assured of steady and measurable progress within the period covered by the Bond.
He made a presentation on how to deploy an effective security architecture for the Exclusive Economic Zone to sustain harnessing the Blue Economy potentials of Nigeria.
According to him “Now all hands must be on deck to deliver. We have a clearer understanding of the direction of the Ministry and we will ensure Nigerians benefit from Mr President’s vision in creating the Ministry”.
Other areas the DG presented to the Minister for effective monitoring include; NIMASA’s efforts in implementing the Cabotage Act, expansion of the domestic fleet, sustaining the Deep Blue Project and developing a national policy on marine and blue economy.
In the same vein, he harped on promoting Maritime Safety through effective capacity development, and enhanced Safety, Security and compliance to global acceptable standards.





Given the growing capacity of private refiners and their impact on local supplies, Nigeria’s president, Bola Ahmed Tinubu has assured of his government’s commitment to rehabilitating and repositioning Nigeria’s dormant national refineries.
Represented by the Permanent Secretary of the Ministry of Petroleum Resources, Patience Oyekunle, at the 20th OTL Africa Downstream Energy Week in Lagos, on Monday, Tinubu revealed his government’s priorities for the petroleum industry.
He made it clear that the facilities will not be allowed to become stranded investments.
Recall that three government refineries, including the Port Harcourt, Warri and Kaduna refineries, being managed by the Nigerian National Petroleum Company Limited (NNPC Ltd), have been moribund despite billions of naira spent on turnaround maintenance over the years.
READ ALSO: NUPRC Sets Revocation Date for Undeveloped Oil Licences
Speaking at OTL conference, Tinubu said the government was pursuing a more rigorous and commercially sustainable approach to the rehabilitation of the national refineries, with technical assessments, stronger partnerships and improved operational discipline expected to guide the process.
“At the same time, the government remains committed to ensuring that existing national refining assets are not allowed to become stranded investments.
“We are pursuing a more rigorous, commercially sustainable approach to the rehabilitation and repositioning of our refineries, supported by technical assessment, stronger partnerships, and improved operational discipline,“ she stated.
Tinubu emphasised that the objective is to ensure Nigeria refines more of its crude and a fuel supplier to other nations.
“Our objective is clear. Nigeria must first refine more of its crudes, create more value domestically, and become a reliable supplier of energy to Africa,” he said.
The President’s position comes as Nigeria seeks to increase domestic refining capacity and reduce its historical dependence on imported petroleum products, despite having substantial crude oil resources.
He said the country was transitioning from an industry historically characterised by import dependence and infrastructure constraints to one increasingly driven by domestic refining, private investment, market efficiency, value addition and regional competitiveness.
According to him, the reforms introduced under the Petroleum Industry Act (PIA) are intended to create a transparent, commercially viable and investment-friendly industry capable of delivering greater value to Nigerians.
“The reforms under the PIA are designed to create a petroleum industry that is transparent, commercially viable, investment-friendly, and capable of delivering value to Nigerians. Today, we are beginning to see the results,” he said.
Tinubu described the emergence of large-scale private refining capacity as an important turning point for Nigeria’s petroleum industry, citing the Dangote Petroleum Refinery as a major development in the country’s ambition to become a net exporter of refined petroleum products.
He said the refinery had reached its nameplate capacity of 650,000 barrels per day, strengthening Nigeria’s prospects of supplying refined products to other African countries.
“The emergence of large-scale private refining capacity represents an important turning point. The Dangote Refinery has reached its 650,000-per-day main-plate capacity, strengthening Nigeria’s prospect of becoming a net exporter of refined petroleum products and creating opportunities for regional supply,” he said.
The president said the government’s ambition extended beyond increasing crude oil production, stressing that Nigeria needed to develop an energy economy in which its petroleum resources would support industrialisation, manufacturing and other productive activities.
For decades, Nigeria exported crude oil while importing a substantial portion of the petroleum products required to power its economy. Tinubu said his administration wanted to change that pattern by retaining more value within the country through refining, petrochemicals, gas processing and other energy-intensive industries.
He said the government was also seeking to ensure that the country’s oil and gas resources translated into jobs, investment, technology and broader economic prosperity.
“Our commitment is therefore not to simply produce hydrocarbons. It is to create an ecosystem in which hydrocarbons catalyse industrialisation, jobs, investment, technology, and prosperity,” he said.
Tinubu also called on operators across the petroleum value chain to contribute more to domestic industrial development, particularly through investment in local content, technology, infrastructure and human capital.
He said industry stakeholders were expected to take greater responsibility for environmental protection and community development, warning that extracting resources without creating additional value was no longer consistent with the government’s expectations.
“To our industry stakeholders, I say, the era of extracting value without building value is changing. We expect greater investment in local content, technology, infrastructure, human capital, environmental responsibilities, and boost community development,” he said.
The president further urged investors to take advantage of opportunities in Nigeria’s petroleum industry, saying the country remained open to businesses with the technical competence and financial capacity to develop its oil and gas resources.
In his opening speech, the Chairman of the OTL Advisory Board, Adetunji Oyebanji, said Africa’s downstream petroleum industry had made significant progress since the organisation began in 2007, with developments in refining, logistics and market liberalisation expanding the continent’s capacity to meet its energy needs.
Oyebanji said the emergence of large-scale private refining in Nigeria, particularly the Dangote refinery, had changed the prospects for domestic petroleum supply and regional trade.
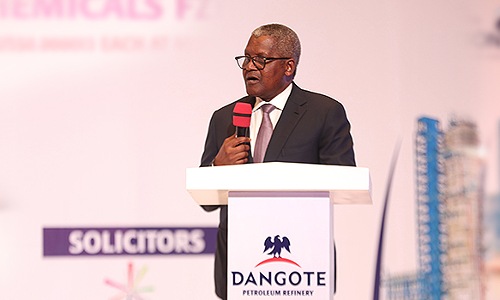
Africa’s ambition of becoming a global industrial powerhouse hinges on its ability to mobilise long-term financing, deliver reliable electricity and adopt policies that turn its vast natural resources into manufactured products.
The President/Chief Executive, Dangote Industries Limited, Aliko Dangote expressed these views in London at the Financial Times Africa Summit during a conversation with David Pilling the Africa Editor of the newspaper.
Dangote, who has outlined a $50 billion investment programme for 2026 to 2030, said the continent must build stronger financial institutions capable of funding large-scale industrial projects, expand electricity infrastructure and establish policies that encourage domestic manufacturing, value addition and economic diversification.
The industrialist maintained that Africa possessed the natural resources, population and investment opportunities required to become a global manufacturing powerhouse, but needed stronger institutions and infrastructure to translate those advantages into sustainable economic prosperity.
Responding to a question on why Africa had produced relatively few industrial enterprises of global scale despite its enormous economic potential, Dangote stressed the need for deliberate policies and institutions capable of supporting long-term industrial investment.
READ ALSO: Thor Empowers Host Communities with 10 Cassava, Palm Oil Processing Plants
The Africa Summit by the FT is a prestigious platform for Africa’s most influential leaders and this year’s Summit lived up to its billing convening leading policymakers, business leaders, financiers and visionaries to explore how Africa can contribute meaningfully to shape the next era of global development.
Dangote said, “I think the number one thing that the continent has to concentrate on doing is having very strong financial institutions, their own financial institutions, and also to have very strong agricultural policy, and also industrial policy”.
He maintained that infrastructure development was equally important but singled out electricity as perhaps the most urgent requirement for unlocking Africa’s industrial potential, adding; “For Africa, what we need the most today is actually power,” he declared.
Dangote explained that inadequate electricity supply continued to undermine Africa’s ability to process its mineral resources locally, forcing countries to export raw materials rather than capture the greater economic value associated with manufacturing and processing. He cited the mining industry as a particularly striking example, noting that companies frequently identified unreliable electricity supply as a major reason for their inability to establish processing facilities close to extraction sites.
According to him, approximately 650 million Africans remain without access to electricity, a deficit he described as fundamentally incompatible with the continent’s industrial ambitions.
He argued that resolving the power crisis would transform Africa’s manufacturing prospects, encourage investment in mineral processing and create substantial employment opportunities.
The industrialist also drew on his experience developing the Dangote Petroleum Refinery and Petrochemicals (DPRP) in Lagos to illustrate how Africa’s financing environment could frustrate even commercially promising projects.
He disclosed that the Group had been compelled to finance the refinery against its own balance sheet rather than depend on conventional project financing, which he described as extremely difficult to secure for major African industrial investments.
He explained that prolonged financing negotiations could undermine the viability of industrial projects by delaying execution, increasing costs and exposing investors to changing economic conditions.
For the Dangote Group, the decision to proceed with the refinery without conventional project finance involved extraordinary financial risks, compounded by severe currency depreciation and the enormous cost of developing supporting infrastructure. Dangote said the exchange rate moved from approximately ₦136 to the dollar to as high as ₦1,800 during the refinery’s development, while about 90 percent of the Group’s revenue was denominated in naira.
Dangote said the Group’s proposed $50 billion investment programme was designed partly to encourage other Africans to recognise the opportunities available across the continent.
“The legacy we are trying to set up is how do we industrialise our continent?” he said.
He explained that the Group intended to expand its investments between 2026 and 2030 to demonstrate that African businesses could execute large-scale projects and encourage other investors to participate in developing the continent. The ambition, he stressed, extended beyond the growth of one conglomerate to creating a wider industrial ecosystem capable of supporting businesses, generating employment and retaining more economic value within Africa.
Dangote also challenged African governments to reconsider their approach to industrial protection, warning that allowing cheap imported products to undermine domestic manufacturing could permanently weaken the continent’s productive capacity. He argued that emerging African industries required appropriate policy support to compete against established international manufacturers, particularly where imported products were sold at prices that discouraged investment in local factories.
He, however, distinguished industrial protection from restrictions on trade between African countries, advocating a regional approach that would strengthen manufacturing while preserving the objectives of the African Continental Free Trade Area. He maintained that African economies should trade more freely among themselves while establishing a common framework to protect their industries against unfair external competition.
The industrialist also questioned why Africa continued to experience widespread poverty despite its extensive agricultural land, mineral resources and youthful population.
He cited the continent’s natural endowments as evidence that Africa’s economic challenges were not principally the result of inadequate resources but of insufficient productive investment and industrial capacity. “Why should we remain poor?” he asked.
Dangote expressed confidence that the continent was entering a period in which African governments, entrepreneurs and investors were becoming increasingly determined to develop their own productive capabilities.
Business
Dangote Calls for Stronger Protection of Local Industries, Unveils Pan-African Energy Distribution Network

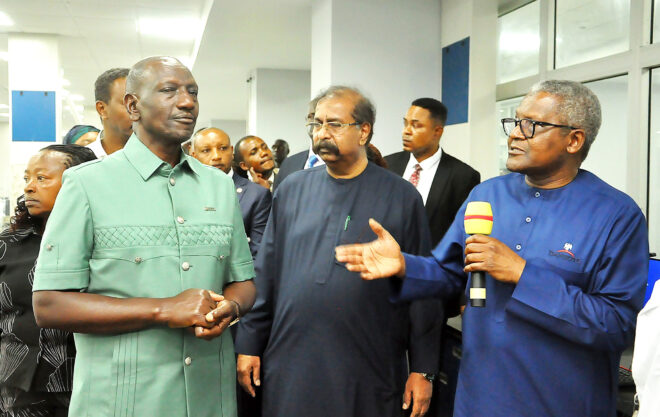
President and Chief Executive of Dangote Industries Limited (DIL), Aliko Dangote, has urged African governments to adopt policies that protect domestic industries and accelerate industrialisation.
He made the call in London, during the FT Africa Summit where he vented plans to establish an extensive petroleum distribution network across Africa through strategic investments in pipelines, storage facilities and supply corridors.
According to Dangote, the Group is aggressively expanding its petroleum logistics and distribution infrastructure across East, Central and Southern Africa as part of efforts to strengthen energy security, improve access to refined products and eliminate longstanding supply bottlenecks across the continent.
During a wide-ranging interview with Financial Times Africa Editor, David Pilling, the industrialist disclosed that the Group recently acquired a 25 percent stake in a petroleum products pipeline network in Kenya and is pursuing additional infrastructure projects connecting Djibouti and Ethiopia, alongside investments in Cameroon and Namibia.
READ ALSO: NMDPRA Issues Updates on Q3 Crude Supplies to Domestic Refineries
According to him, Africa’s aspiration for economic transformation will remain difficult to achieve without significant investments in infrastructure combined with industrial policies that promote local manufacturing, preserve productive capacity and create sustainable employment opportunities.
“Allowing imports to displace local production means we are exporting our jobs out of the continent and importing poverty into the continent,” Dangote said.
Dangote explained that the expansion forms part of a broader strategy to develop an interconnected African energy supply system capable of linking major refining centres with underserved markets that have historically depended on imported petroleum products and fragmented distribution channels.
“We are very aggressive with that,” he said, in response to questions about the Group’s plans for petroleum depots, pipelines and logistics infrastructure.
He revealed that the acquisition of a 25 per cent stake in Kenya’s petroleum pipeline network was achieved with the support of the Kenyan government and would significantly enhance the movement of refined petroleum products within the East African region.
“Just let me tell you, yesterday, with the support from the President of Kenya, we bought 25 percent of the pipeline network for the distribution of petroleum products,” Dangote disclosed.
The Group is also developing a major petroleum distribution corridor linking Djibouti and Addis Ababa, complete with storage terminals and tank farms designed to facilitate the efficient transportation and storage of refined products.
He added that another strategic project in Cameroon is nearing completion, while Namibia has been identified as a critical hub in the Group’s plan to penetrate Southern African markets.
Dangote described Namibia as a particularly attractive location because of its strategic proximity to the Dangote Petroleum Refinery and Petrochemicals (DPRP) in Lagos.
“From our refinery to Namibia is just about four days of steaming,” he noted.
According to him, refined products from the Lagos refinery will be transported to Namibia and distributed across interconnected markets, including Botswana and South Africa.
The Group is also examining other supply corridors extending into Zimbabwe and Zambia as part of its broader objective of developing a continental network supported by strategically located storage and transportation infrastructure.
The petroleum distribution expansion complements plans to establish another refinery in Lamu, Kenya, with a projected refining capacity of approximately 700,000 barrels per day.
Dangote noted that East Africa’s growing economies, vibrant mining sector and increasing energy demand make the region an attractive destination for refining investments.
He explained that the proposed refinery would source crude oil from multiple markets rather than depend exclusively on supplies from Kenya or Uganda, ensuring greater flexibility and long-term operational sustainability.
According to him, technical assessments identified Lamu as the preferred location because of its deep-water access, marine infrastructure and availability of critical resources required for large-scale refining operations.
Dangote revealed that the investment decision was concluded within four months, although he alleged that vested commercial interests attempted to delay the project through legal proceedings shortly before its public announcement.
Beyond energy infrastructure, Dangote strongly advocated policies aimed at protecting domestic industries from unfair competition, arguing that industrialisation cannot thrive if emerging African manufacturers are exposed to unrestricted imports from more established economies.
He questioned why African countries should be discouraged from supporting local industries when developed economies increasingly deploy similar measures to strengthen domestic manufacturing and employment.
Drawing parallels with recent developments in major global economies, he argued that industrial protection remains a legitimate and widely accepted economic strategy.
“If America is now saying, no, we are going to protect our industries, who are we in Africa not to protect our own industries?” he asked.
Dangote also disclosed that the Group has earmarked approximately $50 billion for investments between 2026 and 2030, describing the programme as part of a broader mission to demonstrate that African businesses can successfully execute transformative industrial projects at scale.
“The legacy we are trying to set up is how do we industrialise our continent?” he said.
According to him, the investment programme is designed not only to expand the Group’s operations but also to inspire other African entrepreneurs and investors to pursue ambitious industrial ventures capable of reshaping the continent’s economic future.
Looking beyond the energy sector, Dangote identified inadequate power supply, weak financial systems and underdeveloped industrial policies as major challenges constraining Africa’s economic growth.
He described electricity as a fundamental requirement for industrialisation, particularly in manufacturing, mining and mineral processing, where reliable power is essential for value addition.
With an estimated 650 million Africans still lacking access to electricity, he stressed that addressing the continent’s energy deficit would unlock significant opportunities for job creation, industrial development and economic diversification.
Questioning why a continent blessed with abundant natural resources, vast arable land and a young population continues to grapple with poverty, Dangote insisted that Africa possesses all the ingredients necessary to become a major industrial powerhouse.
Expressing optimism about the continent’s trajectory, he maintained that Africa’s industrial awakening has already begun.
“The journey has started,” Dangote declared. “But now we’re awake, and we will make it happen.”

Tinubu Promises to Boost Local Production with NNPC Refineries

INEC Opens Online Access to Voters’ Register After Public Outcry

ADC Replies Alake, Says APC’s ‘Falsehood’ Cannot Hide Tinubu’s Failures

‘How Did Tinubu Graduate Before School Existed?’ – ADC Challenges Shettima Over Atiku

Tinubu Congratulates Lula on Re-Election, Seeks Stronger Nigeria-Brazil Ties

Ebola: IGP Warns Nigerians Against Contact With Suspected Patients’ Body Fluids

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart