Business
EU signs part of Economic Deal with Ukraine

BRUSSELS — The European Union and Ukraine on Friday signed part of a broad political and economic agreement that sparked the West’s escalating conflict with Russia.
On the second day of a summit of EU leaders in Brussels, Ukrainian Prime Minister Viktor Yatsenyuk and European leaders signed several sections of the agreement that call for stronger political dialogue and security cooperation. But the most substantive sections of the deal—covering trade, law enforcement, anticorruption measures and macroeconomics—likely won’t be signed until after Ukraine holds elections in May.
The EU has already proposed to grant Ukraine the trade benefits of the deal—eliminating tariffs on most Ukrainian exports to the bloc—before the deal is signed.
These steps are intended to bolster Ukraine’s economy and fragile transitional government, months after former President Viktor Yanukovych, under pressure from Russia, refused to sign the agreement. That decision sparked protests, violent clashes with Ukrainian police and ultimately pushed Mr. Yanukovych from office.
“This deal meets the aspirations of millions of Ukrainians that want to be a part of the European Union,” Mr. Yatsenyuk said at the signing ceremony.
EU leaders also agreed to bring forward the deadline for finalizing political and trade accords with Georgia and Moldova. Those agreements, which would bind the two countries into much closer ties with the 28-nation bloc, were previously due to be signed by August.
The step was taken because of European concerns that Russia would step up pressure on Georgia and Moldova to abandon the agreements as it did with Ukraine last year.
The EU has already moved to alleviate Russian economic pressure on Moldova by lifting quotas on the country’s wine exports. It has also promised to ease the procedure for Moldovan citizens to travel to the bloc in the coming months.
Early Friday morning, the EU agreed on a new list of Russian sanctions targets, including members of President Vladimir Putin’s governing team. They will be added to a list of 21 Russians and Crimeans the EU had already slapped with a travel ban and asset freeze. Thursday’s action was coordinated with the U.S., which on Thursday brought its list of targets to 31 individuals and a Russian bank.The EU’s new targets, to be identified formally later Friday, are all Russians and don’t include businesspeople, according to someone familiar with the list. Herman Van Rompuy, president of the European Council—which comprises the national leaders of the EU’s member states—said that “some of [the targets] are really high-ranking.” The EU’s earlier list arguably didn’t include anyone in that category.
EU leaders maintained their silence Friday morning about who would be targeted on by sanctions. According to three people familiar with the list, it includes three figures who answer to Mr. Putin and were on the U.S. list issued Monday.
They include Putin aide Sergei Glazyev, a hard-liner who threatened Ukraine with economic retaliation last year as it contemplated whether to sign an Association Agreement with the EU. Also cited is Vladislav Surkov, another aide sometimes called “the Gray Cardinal” for his behind-the-scenes work at the Kremlin. When Mr. Surkov was hit with the U.S. sanctions earlier this week, he memorably joked that the things he liked about America were Tupac Shakur, Jackson Pollock and Allen Ginsberg, and he didn’t need to travel to the U.S. to appreciate their work.
Another target is Dimitry Rogozin, Russia’s deputy prime minister. He, too, laughed off the U.S. sanctions, and tweeted to “Comrade Obama” that “some prankster” must have come up with the sanctions targets.
Lithuanian President Dalia Grybauskaite said the bloc wouldn’t be cowed by Russian talk of retaliating against the European measures.
“Nobody is afraid of anybody,” she said when asked about the threats.
On Friday morning, Mr. Putin said his government won’t retaliate against the new U.S. sanctions on Russia imposed Thursday.
An unusual level of secrecy surrounded the names of the EU’s targets, as the bloc’s officials sought to prevent the individuals from moving their assets before the formal publication. The national leaders could bring no aides into their meeting, and they were deprived of Wi-Fi and phone service during the session, according to someone familiar with the situation.
European leaders also canceled an EU-Russia summit planned for June and said individual countries would cancel their own meetings with Russia. If Moscow continues to block a monitoring mission to Ukraine by the Organization for Security and Cooperation in Europe, they said, they would organize their own EU mission.
The leaders also said they had asked the European Commission, the EU’s executive body, as well as individual member states, to draw up plans for “targeted economic measures” if Russia continues to destabilize Ukraine.
They declined to specify what specific Russian actions would trigger such broader measures, such as embargoes. “We will assess each action, each incident in itself,” Mr. Van Rompuy said. “We will not put all our cards on the table…But the preparations are ongoing.”
Nicos Anastasiades, the president of Cyprus, whose banks and beaches make it a popular destination for Russians, told reporters the EU must pursue steps that avoid financially damaging its member states.
Other leaders said they are bracing for the possibility that just such steps will be necessary before long. “We need to prepare ourselves, and that means of course hurting ourselves in a way,” said Swedish Prime Minister Fredrik Reinfeldt. “I think this is already happening. Sweden as a country has 400 companies present in Russia, and they are already worried.”
Others looked for different ways to send Russia a message. German Chancellor Angela Merkel said the Group of Eight industrialized nations, which had included Russia, is essentially defunct as a result of Russia’s incursion into Ukraine.
“As long as there is no political environment for such an important political format as the G-8, the G-8 doesn’t exist anymore,” Ms. Merkel told the Bundestag, Germany’s parliament on Thursday.
-WALLSTREET JOURNAL

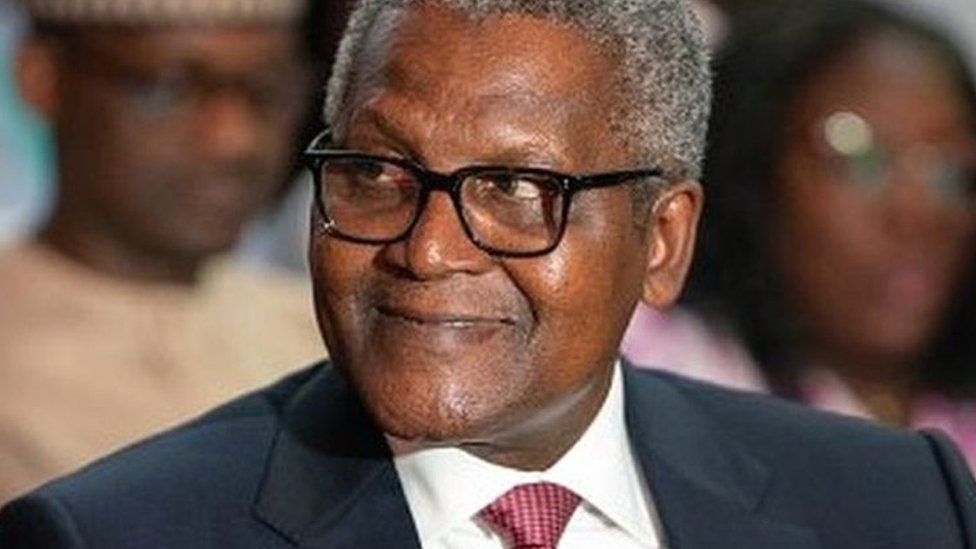
President/Chief Executive, Dangote Industries Limited, Aliko Dangote, has disclosed plans to increase the group’s investment programme in Africa from $50 billion to about $70 billion under its Vision 2030.
Biztellers reports that this strategy would witness a major intervention in electricity generation to support industrial growth, to the tune of 10,000-megawatt.
Addressing creative industry stakeholders from Northern Nigeria, including content creators, journalists, bloggers, entertainers and Kannywood stars, Dangote said expanding production, creating jobs and providing reliable electricity were essential to unlocking Nigeria’s economic potential.
He identified inadequate power supply as a major obstacle to the survival of small and medium-sized enterprises, warning that businesses dependent on petrol and diesel generators would struggle to remain profitable. Dangote said the group was considering a 10,000-megawatt power programme across Africa, potentially including Nigeria, alongside an expansion of the generating capacity dedicated to its own operations.
“We initially planned to invest $50 billion. We are now looking at increasing that to about $70 billion in Africa,” he said.
Explaining the ambition behind Vision 2030, Dangote said African businesses must take greater responsibility for investing in the continent and addressing the infrastructure constraints that discourage other investors.
READ ALSO: Chevron Nigeria Emerges Second-best Exhibitor at NAPE 2026
According to him, inconsistent government policies and unreliable electricity remain significant barriers to investment. He said the group had largely addressed the power challenge within its operations by generating its own electricity.
“Across the group, we currently have almost 1,500 megawatts. By the time we complete Vision 2030, that could rise to between 4,500 and 5,000 megawatts,” he said. “That is captive power—electricity for our own operations. Separately, part of the vision is to intervene in power generation with 10,000 megawatts across Africa, potentially including Nigeria.”
Responding to a question about the economic decision that would most improve the lives of ordinary Nigerians, Dangote placed electricity at the centre of the country’s development needs.
He argued that individual households and companies installing alternative power systems would not, by itself, resolve the wider economic problem.
“Installing solar power for yourself does not mean the wider problem has been solved. Other people may not have that option,” he said. “A vibrant economy is driven by small and medium-sized enterprises. Large companies such as ours help sustain those businesses, but SMEs are essential to economic activity. When you generate electricity using diesel or petrol, it becomes very difficult to make money.”
Dangote expressed confidence in Nigeria’s entrepreneurial strength, saying the country had yet to realise the full benefits of its large and dynamic economy. He said businesses had a responsibility to invest and create opportunities, while the government should concentrate on providing policies and conditions that allow enterprises to grow.
“The government’s principal responsibility is to create an enabling environment through good policies. With the right policies, businesses can invest and create jobs,” he said.
The industrialist identified agriculture and solid minerals as areas with substantial potential, particularly in Northern Nigeria, but stressed that the country must move beyond exporting unprocessed resources. He said investment in infrastructure, including ports, could open markets for other producers and make it easier for businesses to develop and export their products.
“It is not only about us; it is about Nigeria and the African continent,” he said. “We should not simply export raw materials and then buy back the processed products at many times the price. That is the pattern we want to change. Without production, we will continue to face economic difficulties. We must build a productive economy.”
Sharing lessons from his business career, Dangote attributed the group’s expansion to focus, financial discipline and the consistent reinvestment of earnings. He said the transition from trading to manufacturing was built around products the group already understood, supported by established customers, distribution networks and market knowledge.
“The logical next step was backward integration: producing the things we were already importing,” he said.
Dangote also urged entrepreneurs to avoid spending anticipated profits and to recognise when a venture was no longer commercially viable.
“Give it your best effort, but when you do the numbers and they are not adding up, you must be willing to leave,” he said.
Despite the challenges facing businesses, he maintained that the group would continue investing and encouraged smaller enterprises to build opportunities around major industrial projects.
“People like us will continue investing. People like you can build businesses around those investments—as suppliers, producers and service providers,” he said.
Chevron Nigeria won the second-best exhibitor award at the just-concluded 2026 Nigerian Association of Petroleum Explorationists (NAPE) conference and exhibition at Eko Hotels and Suites, Victoria Island, Lagos.
Biztellers reports that Olajumoke Cecilia Ajayi, FNAPE, NAPE President (2025–2026) and Managing Director/CEO of Ingentia Energies Limited, presented the award to Chevron, during the awards dinner on November 12, 2026.
The award is in recognition of Chevron’s outstanding exhibition, where visitors to its booth, particularly students, took part in Geology/Geophysics presentations and quizzes, word games, and Human Resources/Nigerian Content presentations and quizzes, with gifts for winners and participants.
Commenting on the award, the leader of the Chevron’s exhibition team, Dr. Victor Anyaegbudike, Manager Communications, Chevron companies in Nigeria and the Mid Africa Region, commended NAPE for its commitment to hosting the annual conference and exhibition. He noted that Chevron has operated in Nigeria for over 60 years, contributing to the country’s growth and development and making human investments that yield long-term, transformative returns.
READ ALSO: Tinubu, Shettima Head to Jos for APC Presidential Campaign Rally
“At Chevron Nigeria, we drive innovation and investment to open up opportunities for growth, jobs, productivity and lasting value. Forums like the NAPE conference and exhibition matter because they bring government, academia, students and industry together around shared goals and a better understanding of one another,” he remarked.
Victor noted that Chevron is committed to building productive, collaborative and mutually beneficial relationships, grounded in trust, with governments, partners, customers, communities and employees. “We believe that affordable, reliable and ever-cleaner energy is vital to a more prosperous and sustainable world,” he said.
Attendees at the NAPE conference and exhibition included representatives of the Federal Government of Nigeria, industry regulators, industry leaders, academics, and students from tertiary institutions across the country.

The Nigerian Exchange Limited (NGX) recorded a 1.36 per cent weekly gain as its market capitalisation increased to ₦163.80 trillion at the close of trading on Friday, November 13, 2026.
The NGX All-Share Index (ASI) rose to 252,269.16 points, pushing the market’s year-to-date return to 62.11 per cent.
The performance reflected a positive trading week for the equities market, with 43 listed companies recording price appreciation, compared with 29 in the previous week.
SEE MORE:NGX Market Cap Falls to ₦163.65trn As All-Share Index Drops
According to the Exchange’s weekly market report, investors traded 8.03 billion shares valued at ₦185.36 billion in 160,836 deals during the week.
This represented a significant increase in trading volume from the 2.83 billion shares exchanged in 192,158 deals in the preceding week, although the total value of transactions declined from ₦208.41 billion.
The Financial Services Industry dominated trading activities, accounting for 4.85 billion shares worth ₦95.79 billion. This represented 60.45 per cent of the total equity turnover volume and 51.68 per cent of turnover value.
The Agriculture Industry followed with 2.24 billion shares valued at ₦22.78 billion, while the Consumer Goods Industry recorded 260.99 million shares worth ₦11.89 billion.
Further details of the market performance showed that 39 equities declined during the week, compared with 57 in the previous week, while 64 equities closed unchanged against 60 recorded in the preceding period.
On the gainers’ chart, Champion Breweries Plc emerged as the best-performing stock, appreciating by 27.27 per cent, while LivingTrust Mortgage Bank Plc recorded the biggest loss, declining by 18.53 per cent.
Meanwhile, trading in Exchange-Traded Products (ETPs) stood at 1.21 million units valued at ₦278.97 million in 3,351 deals, compared with 1.46 million units worth ₦381.82 million in 4,085 deals in the previous week.
The fixed-income segment recorded 156,612 units valued at ₦177.88 million in 41 deals, against 21.99 million units worth ₦20.60 billion in 48 deals recorded in the preceding week.
The Exchange also recorded the listing of two commercial paper instruments issued by Thrive Agric Limited.
The instruments comprised ₦3.17 billion Series 1 (Tranche A) and ₦2.09 billion Series 1 (Tranche B) Commercial Papers, with a combined value of approximately ₦5.26 billion.

Dangote Plans 10,000MW Power Intervention, Raises Africa Investment Ambition to $70bn

40% of Breadmakers Shut Down as Atiku Accuses Tinubu of Economic Failure

ADC Fires Back at NBA Over Kalu, Says ‘No Respectful Way to Address Evil’

INEC Debunks Amupitan Resignation Rumour After London Protest, Voter Register Controversy

Chevron Nigeria Emerges Second-best Exhibitor at NAPE 2026
NGX Gains 1.36% as Market Capitalisation Climbs to ₦163.80trn

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart