Business
IMF Executive Board Concludes 2014 Article IV Consultation with Mauritius

PORT-LOUIS – On April, 21, 2014, the Executive Board of the International Monetary Fund (IMF) concluded the Article IV consultation1 with Mauritius.
A stable macroeconomic environment was maintained in 2013, despite difficult external developments. Real GDP growth was lower than expected at 3.2 percent in 2013, mainly on account of construction, sugar and tourism. With subdued international prices, inflationary pressures declined in 2013, despite the public sector wage increases, and year-on-year inflation fell to 3.5 percent. The unemployment rate was unchanged compared to 2012 at 8.0 percent. Credit to private sector growth remained robust. On the external front, the current account deficit widened to almost 10 percent of GDP in 2013. The reserve cover of imports of goods and services stayed constant at 4½ months with the Bank of Mauritius (BOM) accumulating additional net international reserves.
The fiscal policy stance was more expansionary than planned because of cyclical and one-off factors but also slippages. The structural primary deficit was broadly unchanged relative to 2011. The overall deficit including extra-budgetary funds is estimated at 4½ percent of GDP. While revenues remained broadly unchanged in proportion of GDP, expenditures increased by over 2 percent of GDP. As expected wages increased following the Pay Research Bureau’s (PRB) report, which increases civil servant salaries beyond annual inflation adjustments periodically with the next adjustment expected in 2016. Additional spending was also related to the flash floods in Port Louis as well as unplanned transfers to local governments and public enterprises. Finally, capital spending including by the special funds was 1 percent of GDP higher, though partially due to cost overruns.
Monetary policy was somewhat accommodative. Throughout the year, while a sluggish domestic demand and low international inflationary pressures helped anchor inflation expectations. The public sector wage increase related to the PRB report did not lead to strong private sector wage pressures. In this context, the BOM maintained the policy rate at 4.65 percent in September 2013 and February 2014, following a 25 basis point reduction in June 2013. In October 2013, reserve requirements were raised from 7 to 8 percent to curb excess liquidity in the banking system. The authorities continued building international reserves and used limited interventions to moderate excessive fluctuations of the rupee. The banking system remained well-capitalized and resilient in a strong regulatory context. Regulatory Tier I capital to risk-weighted assets are well above Basel II and the proposed Basel III requirements. Non-performing loans (NPL) increased slightly in 2013, but banks remained profitable with a 20 percent return on equity, despite low leverage ratios. However, liquidity ratios have worsened in recent years and are on the low side in international comparisons. BOM is consulting with banks on implementation of Basel III regulations and continued to publish its bi-annual CAMEL ratings for all domestic banks. It implemented macroprudential measures aimed at addressing emerging NPLs in the construction and real estate sectors as well as rising indebtedness. Threats to financial stability posed by a Ponzi-like scheme in 2013 were contained successfully, and the regulatory framework was subsequently improved.
Mauritius has established a track record as a reformer with strong institutions and a dynamic private sector. The Africa Training Institute (ATI) is set to open in June 2014 in Ebene. The country statistical capacity continues to be strengthened, including ongoing work on Monetary and Financial Statistics (MFS) as well as balance of payments (BOP) and international investment position (IIP) statistics. Mauritius subscribed to the IMF’s Special Data Dissemination Standard (SDDS) in February 2012, being the second Sub-Saharan African country to do so and is working on subscribing to SDDS Plus.
Executive Directors agreed with the thrust of the staff appraisal. They noted that Mauritius’ prudent policies and strong institutions have delivered steady growth, well-anchored inflation expectations, and continued financial stability. The near-term growth outlook is generally favorable, but an uncertain external environment carries risks. Against this background, Directors encouraged the authorities to consolidate recent macroeconomic gains, strengthen policy buffers, and pursue greater economic diversification through structural reforms to enhance the resilience of the economy.
Directors generally considered it appropriate to start tightening fiscal policy this year to smooth adjustment and increase the likelihood that the 50 percent target for the debt-to-GDP ratio is achieved by 2018, as mandated by law. They encouraged the authorities to articulate an ambitious consolidation strategy centered on better prioritizing public expenditure, strengthening tax administration, and broadening the tax base. Subsidy reforms and an overhaul of public enterprises, as well as an improved framework for fiscal devolution, including a better use of real estate taxes, could also underpin the budgetary adjustment over the medium term.
Directors agreed that the current monetary stance is broadly appropriate, but cautioned that a withdrawal of accommodation might be necessary if inflationary pressures intensify. They also suggested strengthening the institutional and operational arrangements that would support the eventual adoption of a formal inflation targeting framework.
Directors noted that the banking system remains well-capitalized, profitable, and resilient to shocks. They observed, however, that persistent excess liquidity in the banking system has hindered the monetary transmission mechanism, while also encouraging disintermediation and riskier lending. To address this issue, Directors encouraged the authorities to consider an approach to liquidity management involving additional issuance of government paper for monetary policy purposes and—more broadly—closer collaboration between the government and the central bank. Similarly, coordination between the central bank and the nonbank supervisor should continue to be strengthened to ensure the soundness of the overall financial system.
Directors took note of the staff’s assessment that the rupee appears to be modestly overvalued in real effective terms. To bolster Mauritius’s international competitiveness and durably reduce the large structural current account deficit, they recommended greater exchange rate flexibility, well-prioritized infrastructure investment, and stepped-up reforms to address labor and product markets rigidities. Directors also agreed that the external adjustment could benefit from further pension reforms that would boost national savings while strengthening social protection.
Directors welcomed the authorities’ intention to adopt the Fund’s SDDS Plus, and supported ongoing efforts to improve the collection of financial and labor market statistics.

The Petroleum Products Retail Outlets Owners Association of Nigeria (PETROAN) has urged the Federal Government to add its member-stations to the petrol discount programme.
It cautioned that the current arrangement could limit the reach and deny vast consumers in underserved communities the benefits of the 30-day discount window.
The PETROAN also urged the FG to allocate at least 30 percent of the discounted petrol volume to outlets operated by its members.
READ ALSO: Tanzania Nears Completion of $42bn Equinor, Shell-Led LNG Project
The calls followed last week’s announcement by the Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, of a petrol discount at Nigerian National Petroleum Company Limited (NNPC Ltd) retail outlets, with priority given to public transport operators nationwide.
According to the National Publicity Secretary, Independent Petroleum Marketers Association of Nigeria (IPMAN), Chinedu Ukadike, the exclusion of independent marketers could undermine the programme’s effectiveness, particularly in communities where NNPC retail outlets have limited presence.
He argued that independent marketers, with their extensive nationwide distribution networks, were better positioned to extend the benefits of the intervention to consumers in remote and underserved areas.
“Independent oil marketers have over 90 percent coverage and presence in the nooks and crannies of this country. You are giving NNPC that is situated only in the town. So how do the poor masses, whom you intend to ensure that this petroleum product will alleviate their sufferings, how would they now get it?” Ukadike asked.
He said the association was not opposed to the government’s policy but insisted that independent marketers should be included to ensure wider access to the discounted product.
“But it’s government policies; we are not against government policies, but let it be all-inclusive; let independent marketers be part of it,” he said.
Ukadike also urged the government to extend the discount period to 60 days, citing logistical challenges that could delay the movement of petrol from coastal depots to other parts of the country.
“And the 30 days should be extended to 60 days. Because of the circulation of petroleum products, most times it takes two weeks for a truck to leave Apapa and get to Gombe, Maiduguri, because of the bad road and all the rest of them and loading process,” he added.
Similarly, PETROAN National President, Billy Gillis-Harry, urged the Federal Government to allocate 30 per cent of the discounted petrol volume to the association’s retail outlets to facilitate broader national distribution.
In the bid to transform Tanzania into the East African regional energy hub, the country is on the verge of concluding an agreement with a consortium of energy companies, including a $42 billion LNG project.
It was gathered that the project is designed to tap the 47.13 tcf of gas discovered in Tanzania’s deep offshore fields, part of the country’s estimated 57.54 tcf in total discovered reserves, the sixth-largest in Africa, behind Nigeria, Algeria, Senegal, Mozambique and Egypt.
READ ALSO: Shell Identifies Keys to Nigeria’s Energy Future
Equinor and Shell would be the lead operators, alongside involvement from ExxonMobil Pavilion Energy and Medco Energi, while state oil major, the Tanzania Petroleum Development Corporation (TPDC), would also hold an equity stake in the project.
“It’s almost there,” Khamis Mussa Omar, Tanzania’s finance minister, told Reuters.
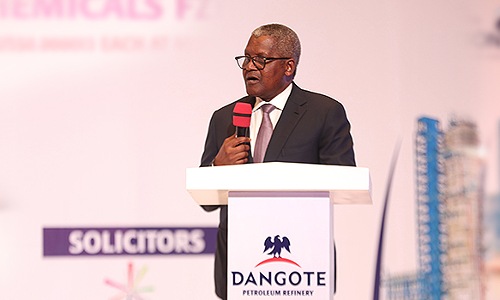
President of Dangote Group, Aliko Dangote, has reaffirmed his commitment to ensuring broad-based participation in the Dangote Refinery’s Initial Public Offering (IPO).
In a statement, the industrialist announced that investors applying with ₦50,000 and below will receive priority consideration as the company seeks to democratize ownership of one of Africa’s most significant industrial assets.
Dangote made the declaration during the final leg of the nationwide IPO roadshow held in Port Harcourt, Rivers State, where investors, financial market experts, business leaders and other stakeholders gathered to discuss the investment opportunity and its implications for Nigeria’s economic transformation.
READ ALSO: Sahara Champions Global Shipping Collaboration for $20m Mercy Ships Healthcare Impact
Speaking at the event, Dangote emphasised that the IPO should be viewed not merely as an investment opportunity, but as a chance for Nigerians to become shareholders in a landmark enterprise that is reshaping the country’s industrial landscape.
“We will prioritise people with ₦50,000 and below,” Dangote stated, underscoring the Group’s determination to make the offering accessible to small and medium-scale investors across the country.
He noted that while international and African investors had already committed substantial capital to the refinery, the IPO now offers Nigerians a rare opportunity to participate directly in the ownership of a world-class industrial project built on Nigerian soil.
According to him, investing in the refinery goes beyond financial returns, representing a vote of confidence in Nigeria’s future, institutional development, corporate governance standards and industrial capacity.
“African investors have invested in this refinery. Now it is time for Nigerians to invest in themselves and participate in a project that is creating value, jobs and opportunities for generations to come,” he said.
Dangote also encouraged prospective shareholders to adopt a long-term investment perspective, noting that participation in the IPO presents a pathway to wealth creation, portfolio diversification and increased public engagement with the capital market.
He added that wider participation in the stock market would deepen financial literacy, promote a savings and investment culture, and enable more Nigerians to better understand how businesses create value and contribute to economic growth.
The roadshow also featured insightful presentations from leading economists and market analysts on the refinery’s economic significance and the broader opportunities associated with the public offering.
Renowned economist Bismarck Rewane highlighted the enormous economic potential of the South-South region and stressed the need to convert the area’s resource endowment into sustainable prosperity, infrastructure development and improved living standards. He also noted that the IPO presents an opportunity to deepen Nigeria’s capital market by encouraging citizens to participate actively in wealth creation.
Similarly, economist Dr. Muda Yusuf outlined the refinery’s far-reaching impact on economic diversification, domestic value addition, energy security, capital formation and employment generation.
According to Yusuf, the refinery represents far more than a petroleum-processing facility, serving as a catalyst for growth across multiple sectors including petrochemicals, packaging, manufacturing, logistics and other downstream industries.
He further emphasized that policy consistency, regulatory stability and sustained stakeholder engagement remain critical to maintaining investor confidence and attracting long-term capital into Nigeria’s industrial sector.
Speaking on the investment outlook, stakeholders urged prospective investors to consider the company’s operational performance, valuation metrics and long-term fundamentals when evaluating the offer.
Yusuf also described the refinery as a major example of domestic value addition, noting that its extensive local content and industrial linkages would significantly amplify its contribution to the Nigerian economy.
Discussions at the event further highlighted the importance of sound monetary policy, affordable financing and a predictable business environment in supporting investment-led growth and industrial expansion.
The Port Harcourt engagement was particularly significant for the South-South region, with legal luminary and business leader Paul Usoro expressing satisfaction at the level of participation from investors across the region.
“My joy is to see the South-South well represented,” Usoro said, stressing the importance of ensuring that investors from the region take advantage of the opportunity presented by the IPO.
The Port Harcourt event marked the final stop of the nationwide IPO roadshow, concluding a series of engagements designed to deepen public awareness and expand participation in what is widely regarded as one of the most significant capital market offerings in Nigeria’s history.
For Dangote Group, the objective remains clear: to provide Nigerians from all backgrounds with an opportunity to participate in the ownership of a transformative industrial enterprise while contributing to economic growth, employment generation and national development.

2027 Election: ‘Your Future Is More Valuable’ — IGP Warn Youths Against Political Violence

Tinubu Charges PCC Members to Deliver Wards

Marketers Eye Portion of FG’s Petrol Discount

Tanzania Nears Completion of $42bn Equinor, Shell-Led LNG Project

IEA Puts UAE’s Oil Output at 5.3mbpd for September

Africa’s Energy Security Conversations Pull Industry Executives Together

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart