Business
Non-oil Exports Hit Record $6.1bn in 2025 — NEPC

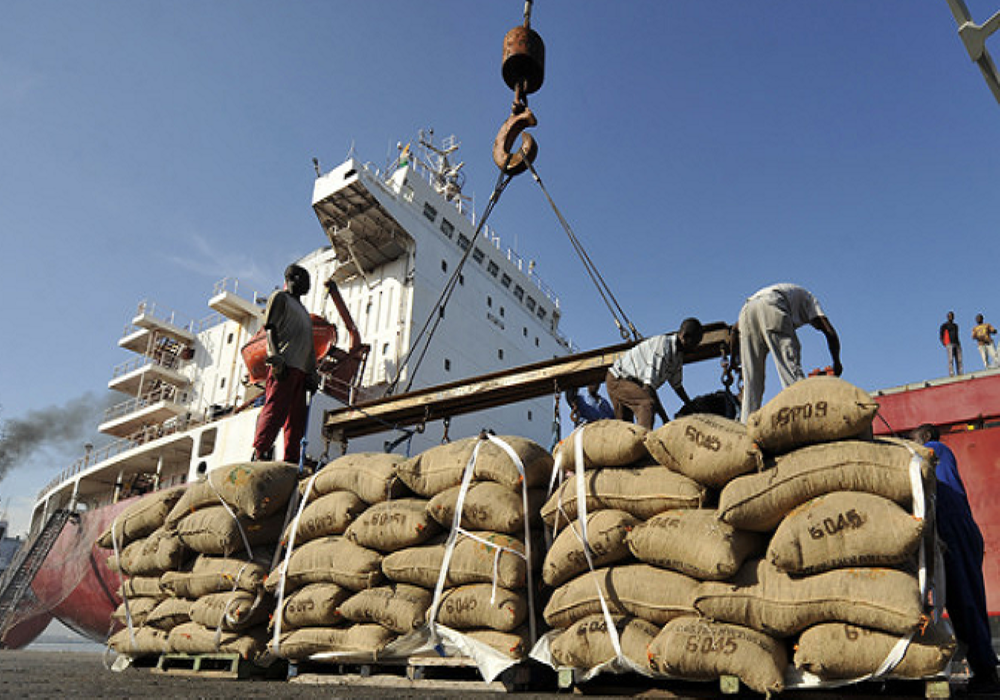
Nigeria’s non-oil exports rose to an all-time high of $6.1bn in 2025, marking the strongest performance in the sector since the establishment of the Nigerian Export Promotion Council nearly five decades ago.
The figure represents an 11.5 per cent year-on-year increase over the $5.4bn recorded in 2024, underscoring growing momentum in the country’s diversification drive away from crude oil dependence.
The Executive Director and Chief Executive Officer of the NEPC, Nonye Ayeni, disclosed this on Monday in Abuja during her annual progress report and 2026 non-oil export outlook briefing.
ALSO READ: Seplat Energy Reaffirms Responsible Operations, Backs NGX’s Net-Zero Drive
According to Ayeni, data obtained from pre-shipment inspection agencies showed that Nigeria had surpassed its previous best performance, describing the 2025 outcome as a historic milestone for formal, documented trade.
“Ladies and gentlemen, based on the records obtained from pre-shipment inspection agencies, Nigerian non-oil export performance in 2025 reached an all-time high. The non-oil export sector rose to approximately 6.1 billion U.S. dollars, representing a year-on-year growth of about 11.5 per cent over and above the 5.4 billion U.S. dollars recorded in 2024.
“This marks the highest non-oil export value achieved in the country for formal documented trade in the country and also from the inception of the council almost 50 years ago. So we have indeed beaten our own records of last year. So Nigeria has 6.1 billion U.S. dollars in terms of value for non-oil export.”
According to her, the $6.1bn export value reflects improved activity across several value chains, supported by expanding market access and increasing product diversification.
Beyond value, Ayeni noted that export volumes also rose significantly, with total non-oil exports hitting 8.02 million metric tonnes in 2025, compared with 7.29 million metric tonnes in 2024, representing a 10 per cent increase.
She explained that the strong performance cut across agricultural commodities, processed and semi-processed goods, industrial inputs, and solid minerals, indicating gradual progress in value addition and broader product representation.
“In 2025 alone, Nigeria exported a total of 281 non-oil products. This reflects our steady transition towards value-added exports and deeper integration into global value chains,” Ayeni stated.
However, the NEPC boss cautioned that the impressive figures did not fully capture the country’s export potential, noting that a significant volume of trade still occurs informally across Nigeria’s land borders.
She said the council was working with the National Bureau of Statistics, the Central Bank of Nigeria, and other stakeholders to mainstream informal trade into official export records, improve data accuracy, and strengthen policy support for exporters.
Ayeni added that ongoing reforms, export incentives, and capacity-building initiatives would be intensified in 2026 to sustain growth and expand Nigeria’s non-oil export footprint.
The latest performance comes amid renewed government efforts to boost foreign exchange earnings, stabilise the naira, and reduce the economy’s vulnerability to oil price shocks by deepening non-oil export revenues.




Nigeria’s public debt has climbed to ₦166.79 trillion as of June 30, 2026, with financial analyst and Managing Director of Financial Derivatives Company Limited, Bismarck Rewane, warning that the country’s debt burden is approaching the 40 per cent of Gross Domestic Product (GDP) limit.
Rewane raised concerns over the increasing debt burden, stressing that the key issue is not simply the amount Nigeria owes but what the borrowed funds have been used to achieve.
“There is a fiscal responsibility that says we shouldn’t exceed 40% of GDP, ₦166 trillion is the limit,” Rewane said.
ALSO READ: Dangote Refinery Ends Nigeria’s Fuel Import Dependence Era, Boosts GDP, FX Earnings — EIU
“The question is not how much the debt is, it is what have you used the debt to acquire? We haven’t seen any corresponding increase in productivity yet and there is a cost of living and affordability crisis.”
He also warned that Nigeria’s debt per capita was already high and could not continue rising indefinitely.
“Nigeria’s debt per head is very high and cannot increase further,” he added.
The comments come as the latest figures from the Debt Management Office (DMO), as reported by Business A.M, showed that Nigeria’s public debt increased by ₦79.41 trillion in three years, rising from ₦87.38 trillion in June 2023 to ₦166.79 trillion by June 2026.
The latest figure represents a 90.9 per cent increase in the country’s public debt stock since June 2023.
On a year-on-year basis, public debt increased by ₦14.39 trillion, or 9.4 per cent, from ₦152.40 trillion in June 2025. It also rose by ₦7.44 trillion, or 4.7 per cent, from ₦159.35 trillion recorded in March 2026.
According to the report, domestic debt stood at ₦91.59 trillion, representing 54.91 per cent of total public debt, while external debt amounted to ₦75.20 trillion, or 45.09 per cent.
The Federal Government accounted for ₦152.77 trillion, representing about 91.6 per cent of the total public debt, while states and the Federal Capital Territory accounted for the remaining ₦14.01 trillion.
The rising debt stock has also been accompanied by increasing debt-servicing costs.
Federal Government domestic debt service rose to ₦3.14 trillion in the first quarter of 2026, compared with ₦2.61 trillion in the corresponding period of 2025.
Interest payments accounted for most of the increase, rising by 25.4 per cent to ₦2.97 trillion during the period.
Rewane’s comments therefore place renewed focus on the economic returns from government borrowing, particularly whether borrowed funds are translating into higher productivity, stronger revenues and expanded productive capacity.
The concern has also been raised by other Nigerian economists and financial analysts, who have argued that borrowing should be linked to projects capable of generating economic returns and strengthening the government’s capacity to repay its obligations.
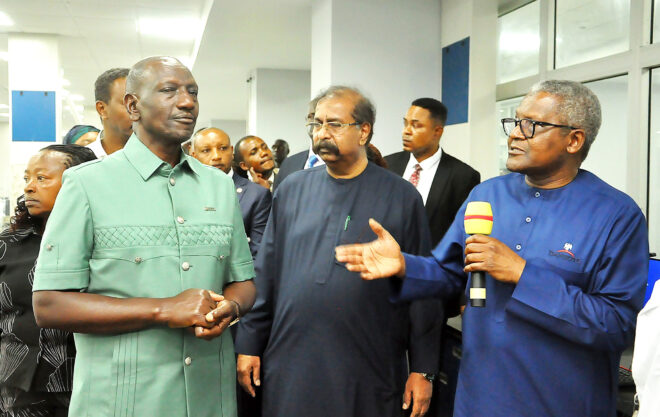
Kenyan President, William Samoei Ruto has described the Dangote Petroleum Refinery and Petrochemicals (DPRP) as “a masterpiece of science, engineering and art”.
He made the declaration following a tour of the world-class facility in Lagos, while reaffirming Kenya’s commitment to partnering with the Dangote Group on the proposed $17 billion East African Oil Refinery and Petrochemical Complex in Lamu.
President Ruto visited the refinery after attending the United Nations General Assembly (UNGA), noted that witnessing firsthand the scale, sophistication and operational excellence of the 700,000 barrels-per-day Dangote Refinery had strengthened his confidence in the East African refinery project.
READ ALSO: Dangote to Support Two Million Women with Refinery IPO Share Ownership
“Coming here and seeing it for myself, I can confirm that I have seen a masterpiece of science, engineering, and art. To my brother Aliko, congratulations. I always knew Nigerians to be very brave people and go-getters, but I did not anticipate that it was at this scale,” President Ruto said.
The Kenyan leader disclosed that preparations had been concluded for the ground-breaking ceremony of the East African refinery project in Lamu, which is expected to become a strategic regional asset for East Africa.
According to him, the refinery will drive industrialisation, create jobs, strengthen engineering and technical capacity, enhance energy security and promote regional economic integration.
“This is not a Kenyan refinery; it is going to be a regional refinery. We are positioning our continent as an emerging growth centre, and this project will help accelerate industrialisation, create jobs, enhance engineering capabilities and strengthen Africa’s economic competitiveness,” he stated bureaucratic bottlenecks to ensure efficient project execution.
“The Government of Kenya is 100 percent behind this project. We have secured the required land and are working to ensure that we spend our time building rather than navigating administrative delays,” he said.
The President further commended the leadership and commitment of Dangote Group President and Chief Executive, Aliko Dangote, highlighting his deep understanding of the refinery’s technical and operational processes.
“The detail with which Aliko Dangote understands this plant is remarkable. Unless you understand the details, you are unable to make the right decisions. That commitment to excellence is one of the reasons behind the success of this project,” he added.
Dangote Group’s Chief Strategy Officer, Aliyu Suleiman, disclosed, during the visit that the conglomerate generated approximately $17 billion in revenue during the first half of 2026 and is on course to achieve a record $36 billion in revenue for the full year, representing a 100 per cent increase over the $18 billion recorded in 2025.
“The revenues of the Group have grown significantly over the last five years. From $18 billion last year, we are on track to get to $36 billion this year. Our half-year revenue is already about $17 billion,” Suleiman said.
He attributed the strong performance to sustained investments across key sectors, including cement, sugar, fertiliser, petroleum refining, upstream oil and gas, and other strategic businesses.
Suleiman noted that Dangote Group’s growth ambitions are anchored on its Vision 2030 Strategy, aimed at expanding the company’s industrial footprint across Africa and creating globally competitive businesses on the continent.
“Between 2020 and 2025, the Group executed a capital expenditure programme of approximately $50 billion. Over the next five years, we intend to invest twice that amount as we accelerate our expansion across Africa,” he stated.
Suleiman emphasised that the proposed 700,000 barrels-per-day greenfield refinery and petrochemical complex in Lamu, estimated at approximately $17 billion, will be a cornerstone of the Group’s ambition to build a $100 billion African industrial enterprise.
“The East African refinery in Kenya is going to be a key component of our journey and our dream to get to $100 billion. It is going to be a major contributor,” he said.
He added that Dangote Group’s expansion plans span a broad range of sectors, including port infrastructure, gas infrastructure, LNG, upstream oil and gas, power generation, mining and other strategic industrial investments across Africa.
As part of preparations for the project, Dangote Group has signed a contract worth more than $450 million with Engineers India Limited (EIL) to provide project management consultancy and engineering, procurement and construction management services for the Lamu refinery and petrochemical complex.
The partnership builds on EIL’s experience and involvement in the successful development of the DPRP in Lagos. Once completed, the East African refinery is expected to process 700,000 barrels of crude oil per day, strengthening regional energy security and supporting industrial development across East Africa.
The Dangote Group is also progressing plans to expand the processing capacity of the DPRP in Nigeria from 700,000 barrels per day to approximately 1.4 million barrels per day through the addition of a new 750,000 barrels-per-day crude distillation unit.
The expansion is expected to further solidify Nigeria’s position as a leading exporter of refined petroleum products and enhance Africa’s energy self-sufficiency.
President Ruto’s visit and Dangote Group’s ambitious growth plans highlight the increasing impact of African-led investments in driving the continent’s industrial renaissance.
With record revenue growth, a robust investment pipeline, expansion of refining capacity in Nigeria and the planned development of the East African Oil Refinery in Kenya, Dangote Group is reinforcing its role as a key driver of Africa’s economic transformation, energy security, industrial development and regional integration.
Photo Caption: From Left – Kenya President, Dr. William Samoel Ruto; Group Vice President, Oil & Gas and Fertiliser, Dangote Industries Limited, Devakumar Edwin; and President/CE, Dangote Industries Limited, Aliko Dangote during the Kenya President’s Visit to Dangote Petroleum Refinery, Petrochemicals and Fertiliser Plant Lekki, Lagos on Friday 25th September 2026.
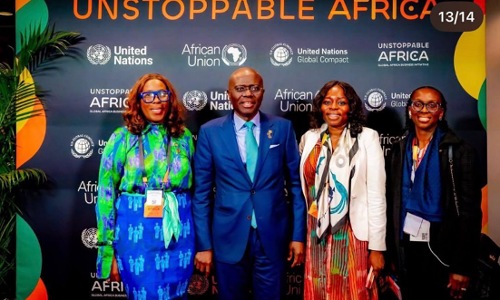
Lagos State Governor, Babajide Sanwo-Olu, has called for stronger international investment partnerships as he pitched Lagos as a strategic gateway for global investment into Africa.
Sanwo-Olu made the call while speaking at the Global Africa Business Initiative’s Unstoppable Africa 2026 in New York, where global business leaders, investors, policymakers and heads of government gathered to discuss ways of strengthening African businesses and expanding the continent’s economies.
The 2026 edition of the event was held on September 20 and 21 at the New York Marriott Marquis, on the sidelines of the opening of the 81st United Nations General Assembly.
SEE ALSO: ‘A Nation Cannot Escape the Bill’ — Atiku Questions Tinubu’s Third UNGA Absence
The governor highlighted Lagos’ large population, expanding market, infrastructure needs, entrepreneurial ecosystem and strategic position as key factors that create opportunities for investors seeking to participate in Africa’s economic growth.
Sanwo-Olu stressed that Lagos’ growing global relevance should translate into tangible benefits for residents through investments in infrastructure, transportation, healthcare, enterprise development and other sectors.
He said the state remained open to international capital, strategic partnerships and private-sector participation, with the goal of building partnerships capable of delivering measurable economic value across Lagos.
According to the governor, Lagos is pursuing a development agenda that combines long-term economic growth with efforts to address the everyday needs of its residents while creating an environment where businesses can establish, expand and compete.
A key feature of the governor’s presentation was the promotion of Invest Lagos, the flagship investment promotion initiative of the Lagos State Ministry of Commerce, Cooperatives, Trade and Investment.
The engagement followed the successful Invest Lagos 3.0 summit held in Lagos in June under the theme, “Lagos: The Business Gateway to Africa.”
The summit brought together global investors, policymakers, development institutions and business leaders to explore opportunities in infrastructure, manufacturing, technology, trade, finance and the creative economy.
Sanwo-Olu’s participation at Unstoppable Africa 2026 further provided an international platform for Lagos to showcase its investment opportunities and seek partnerships aimed at attracting global capital to the state.

2027: INEC Tackles Operational Gaps, Sets October 9 For PVC Collection

‘NELFUND Is A Haven Of Corruption’ — Dino Melaye Blasts Tinubu Govt

Nigeria’s ₦166tn Debt Nears 40% GDP Limit, Productivity Yet to Rise — Rewane

DSS Makes U-Turn On Sowore Trial, Orders Resumption Of Prosecution

Ruto Hails DPRP “Masterpiece” as Dangote Group Accelerates African Expansion

Fire Breaks Out In Kubwa As Vehicle Crashes Into Gas Station

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart