Business
Saudi Arabia Is On A High-stakes Mission To Buy The World

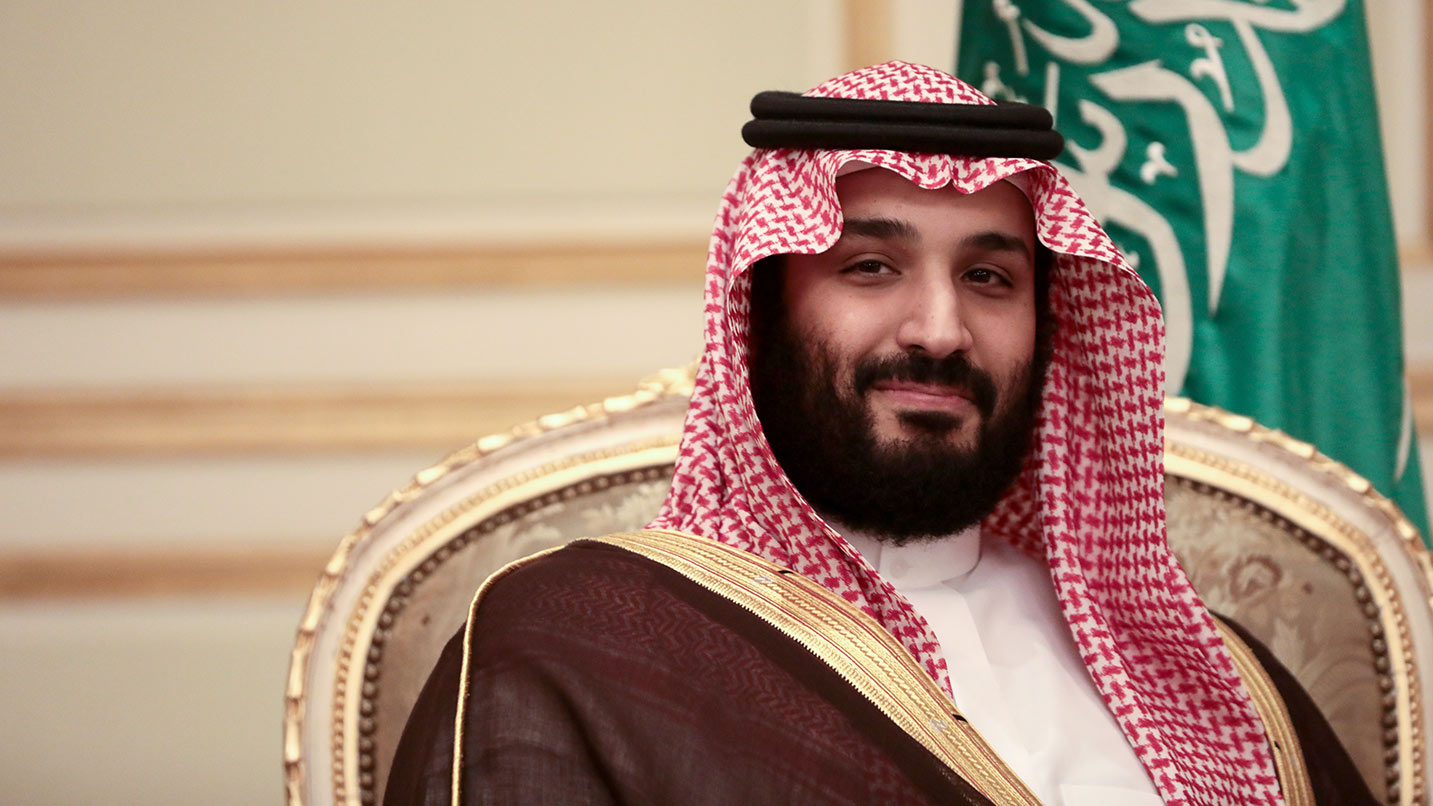
In the months before Mohammed bin Salman celebrated his 30th birthday nearly a decade ago, the yet-to-be anointed Crown Prince of Saudi Arabia was gifted a vital key to unlocking the kingdom’s future: full purview of its Public Investment Fund.
. . . Saudi Arabia’s Public Investment Fund, led by Crown Prince Mohammed Salman, is going global.
. . . The sovereign wealth fund is investing in everything from Uber and Blackstone to Heathrow and LIV Golf.
. . . The verdict is out on just how successful it will be in its global investment spree.
Back in 2015, MBS became chairman of the sovereign wealth fund established in 1971 by a former king at a time when it was ready to be transformed. A slow-moving cog of the state no more, PIF was ready to become an investment juggernaut with global presence.
It’s a task the fast-rising royal hasn’t shied away from. PIF, officially led by governor Yasir Al-Rumayyan, has been stepping up its mission to invest in high-profile assets globally in recent years to help fulfill its mission of reducing Saudi Arabia’s economic dependence on oil.
ALSO READ: Dangote Refinery vs NNPCL: Unfortunately, Nigeria needs both companies to thrive
That mission, a fundamental part of an ambitious program called Vision 2030 that MBS is in charge of, depends in part on how successful the PIF is in generating returns from its big bets overseas — and leveraging those bets to build hot new industries at home.
“MBS’ personal ambition is very much to make Saudi Arabia a highly visible and internationally respected post-oil economy,” Steffen Hertog, associate professor at the London School of Economics, told Business Insider. “The PIF is by far his most important vehicle in this endeavor.”
But as PIF spreads its wings, it is becoming increasingly unclear as to just how successful it stands to be beyond the Gulf.
A look at the PIF’s portfolio presents a show reel of some of the most prolific names in global business.
In the tech sector, it has pumped $3.5 billion into Uber, poured $45 billion into SoftBank’s Vision Fund, taken a 60% stake in Tesla rival Lucid, and become majority owner of augmented reality startup Magic Leap.
Beyond that, it has pumped billions of dollars into LIV Golf, led a $415 million takeover of Newcastle United, backed up a Blackstone infrastructure fund with $20 billion and invested in Carnival, the world’s biggest cruise operator. In June, PIF expanded its stake in London’s Heathrow Airport.
Figures published in July by GlobalSWF, a data firm tracking sovereign-wealth-fund activity, found that PIF deployed more capital in the first half of 2024 than all other state-owned investors, which collectively invested close to $100 billion in the six-month period.
According to LSE’s Hertog, PIF’s attraction to high-profile brands isn’t just about making itself more visible to the West. “These for the most part are corporates active in sectors that the PIF and MBS see as key for Saudi Arabia’s domestic economic diversification.”
To make these deals happen, the kingdom has been busy doing a lot of courting.
In February, it backed a two-day conference in Miami, where the likes of Blackstone leader Stephen Schwarzman and Donald Trump’s son-in-law Jared Kushner were billed as speakers. In October, the kingdom will be prepared for the global elite to descend on capital city Riyadh for its “Davos in the desert” investment conference.
The event, which has previously attracted the likes of JP Morgan and BlackRock CEOs Jamie Dimon and Larry Fink, has proven controversial in the past. MBS’s alleged role in the murder of journalist Jamal Khashoggi in 2018, which he denies having involvement in, gave some dealmakers pause for thought.
That said, the world’s corporate elite appear to be looking past the incident as time passes — something the Saudis seem to be aware of. This year’s theme, “Infinite Horizons,” offers a nod to the global scope it has in mind for its future.
For global companies, fund managers, and bankers, Saudi Arabia’s wealth has been a big draw at a critical time. While other investors have exercised caution in the face of a higher interest rate environment, the kingdom has kept its money flowing.
That’s partly because the fund has set a target of $2 trillion in assets under management by the end of the decade, and is racing against the clock to meet the deadline for its ambitious Vision 2030 program.
Saudi Arabia also finds itself locked in a tense rivalry with other economic powerhouses in the region such as the United Arab Emirates, where funds such as Mubadala and G42 have been busy securing their own big international deals. Bragging rights are on the table.
However, while the Saudis prepare to continue flashing their cash abroad, the PIF faces some risks.
For one, the fund has had to learn the hard reality of going big, as a number of its high-profile investments overseas have struggled financially. Earlier this month, for instance, PIF had to plug a funding gap for Lucid by pumping in an extra $1.5 billion.
The electric vehicle maker first raised more than $1 billion from the Saudis in 2018 after PIF’s talks with Elon Musk to take Tesla private fell through, but has struggled with a high burn rate and waning demand for EVs.
PIF has also had to backstop another company. According to filings released in the UK this month, the fund has put $750 million into Magic Leap since the start of 2023, as it struggling to take its immersive reality headsets mainstream.
For Hertog, though companies like Lucid have “fallen on hard times” — and other bets from PIF on the likes of the SoftBank Vision Fund have “indeed not done well” — it is still too early to say how the overall performance will turn out. The fund did swing to an annual profit in 2023 following an $11 billion loss the previous year, Bloomberg reported, though many bets are still in their early days.
“There are inherent risks in investing in new sectors so what matters is not individual failures but the performance of the whole portfolio,” Hertog said.
PIF’s tanglings with political figures are also raising concerns. Donald Trump’s son-in-law Kushner, who started private equity firm Affinity Partners in 2021, received a $2 billion commitment from PIF for its debut fund, with that commitment now facing an investigation by Senate Finance Committee chair Sen. Ron Wyden.
In a letter published in June, the senator raised concerns that PIF and other Middle Eastern funds were “using payments to Affinity executives as a means to influence Kushner and other politically powerful individuals.”
For Abdullah Alaoudh, a director at the Middle East Democracy Center, it seems clear that buying “a lot of influence” — or “whitewashing” as he puts it — is a key part of the fund’s deal-making overseas. If potential partners can gloss over some of its more controversial activities, such as the Kingdom’s war in Yemen, it’ll have an easier time seeing deals through.
As Hertog notes, it’s worth remembering that PIF’s main priority remains its domestic portfolio. “While some domestic investments have been pruned, the fund’s main ambition is domestic diversification,” he said.
Still, Saudi Arabia seems intent on making its mark on the global stage through the PIF. The world will be keeping watch.
The PIF did not immediately respond to a request for comment from BI.
Credit – Business Insider Africa


Africa’s ambition of becoming a global industrial powerhouse hinges on its ability to mobilise long-term financing, deliver reliable electricity and adopt policies that turn its vast natural resources into manufactured products.
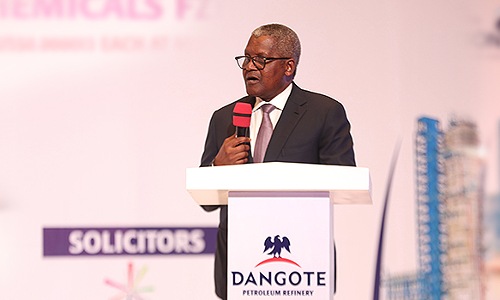
The President/Chief Executive, Dangote Industries Limited, Aliko Dangote expressed these views in London at the Financial Times Africa Summit during a conversation with David Pilling the Africa Editor of the newspaper.
Dangote, who has outlined a $50 billion investment programme for 2026 to 2030, said the continent must build stronger financial institutions capable of funding large-scale industrial projects, expand electricity infrastructure and establish policies that encourage domestic manufacturing, value addition and economic diversification.
The industrialist maintained that Africa possessed the natural resources, population and investment opportunities required to become a global manufacturing powerhouse, but needed stronger institutions and infrastructure to translate those advantages into sustainable economic prosperity.
Responding to a question on why Africa had produced relatively few industrial enterprises of global scale despite its enormous economic potential, Dangote stressed the need for deliberate policies and institutions capable of supporting long-term industrial investment.
READ ALSO: Thor Empowers Host Communities with 10 Cassava, Palm Oil Processing Plants
The Africa Summit by the FT is a prestigious platform for Africa’s most influential leaders and this year’s Summit lived up to its billing convening leading policymakers, business leaders, financiers and visionaries to explore how Africa can contribute meaningfully to shape the next era of global development.
Dangote said, “I think the number one thing that the continent has to concentrate on doing is having very strong financial institutions, their own financial institutions, and also to have very strong agricultural policy, and also industrial policy”.
He maintained that infrastructure development was equally important but singled out electricity as perhaps the most urgent requirement for unlocking Africa’s industrial potential, adding; “For Africa, what we need the most today is actually power,” he declared.
Dangote explained that inadequate electricity supply continued to undermine Africa’s ability to process its mineral resources locally, forcing countries to export raw materials rather than capture the greater economic value associated with manufacturing and processing. He cited the mining industry as a particularly striking example, noting that companies frequently identified unreliable electricity supply as a major reason for their inability to establish processing facilities close to extraction sites.
According to him, approximately 650 million Africans remain without access to electricity, a deficit he described as fundamentally incompatible with the continent’s industrial ambitions.
He argued that resolving the power crisis would transform Africa’s manufacturing prospects, encourage investment in mineral processing and create substantial employment opportunities.
The industrialist also drew on his experience developing the Dangote Petroleum Refinery and Petrochemicals (DPRP) in Lagos to illustrate how Africa’s financing environment could frustrate even commercially promising projects.
He disclosed that the Group had been compelled to finance the refinery against its own balance sheet rather than depend on conventional project financing, which he described as extremely difficult to secure for major African industrial investments.
He explained that prolonged financing negotiations could undermine the viability of industrial projects by delaying execution, increasing costs and exposing investors to changing economic conditions.
For the Dangote Group, the decision to proceed with the refinery without conventional project finance involved extraordinary financial risks, compounded by severe currency depreciation and the enormous cost of developing supporting infrastructure. Dangote said the exchange rate moved from approximately ₦136 to the dollar to as high as ₦1,800 during the refinery’s development, while about 90 percent of the Group’s revenue was denominated in naira.
Dangote said the Group’s proposed $50 billion investment programme was designed partly to encourage other Africans to recognise the opportunities available across the continent.
“The legacy we are trying to set up is how do we industrialise our continent?” he said.
He explained that the Group intended to expand its investments between 2026 and 2030 to demonstrate that African businesses could execute large-scale projects and encourage other investors to participate in developing the continent. The ambition, he stressed, extended beyond the growth of one conglomerate to creating a wider industrial ecosystem capable of supporting businesses, generating employment and retaining more economic value within Africa.
Dangote also challenged African governments to reconsider their approach to industrial protection, warning that allowing cheap imported products to undermine domestic manufacturing could permanently weaken the continent’s productive capacity. He argued that emerging African industries required appropriate policy support to compete against established international manufacturers, particularly where imported products were sold at prices that discouraged investment in local factories.
He, however, distinguished industrial protection from restrictions on trade between African countries, advocating a regional approach that would strengthen manufacturing while preserving the objectives of the African Continental Free Trade Area. He maintained that African economies should trade more freely among themselves while establishing a common framework to protect their industries against unfair external competition.
The industrialist also questioned why Africa continued to experience widespread poverty despite its extensive agricultural land, mineral resources and youthful population.
He cited the continent’s natural endowments as evidence that Africa’s economic challenges were not principally the result of inadequate resources but of insufficient productive investment and industrial capacity. “Why should we remain poor?” he asked.
Dangote expressed confidence that the continent was entering a period in which African governments, entrepreneurs and investors were becoming increasingly determined to develop their own productive capabilities.
Business
Dangote Calls for Stronger Protection of Local Industries, Unveils Pan-African Energy Distribution Network

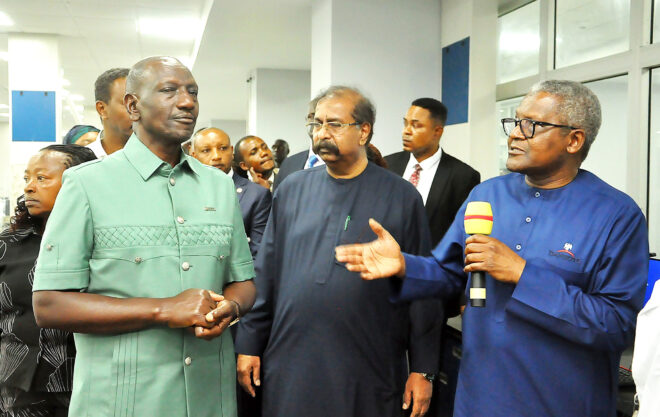
President and Chief Executive of Dangote Industries Limited (DIL), Aliko Dangote, has urged African governments to adopt policies that protect domestic industries and accelerate industrialisation.
He made the call in London, during the FT Africa Summit where he vented plans to establish an extensive petroleum distribution network across Africa through strategic investments in pipelines, storage facilities and supply corridors.
According to Dangote, the Group is aggressively expanding its petroleum logistics and distribution infrastructure across East, Central and Southern Africa as part of efforts to strengthen energy security, improve access to refined products and eliminate longstanding supply bottlenecks across the continent.
During a wide-ranging interview with Financial Times Africa Editor, David Pilling, the industrialist disclosed that the Group recently acquired a 25 percent stake in a petroleum products pipeline network in Kenya and is pursuing additional infrastructure projects connecting Djibouti and Ethiopia, alongside investments in Cameroon and Namibia.
READ ALSO: NMDPRA Issues Updates on Q3 Crude Supplies to Domestic Refineries
According to him, Africa’s aspiration for economic transformation will remain difficult to achieve without significant investments in infrastructure combined with industrial policies that promote local manufacturing, preserve productive capacity and create sustainable employment opportunities.
“Allowing imports to displace local production means we are exporting our jobs out of the continent and importing poverty into the continent,” Dangote said.
Dangote explained that the expansion forms part of a broader strategy to develop an interconnected African energy supply system capable of linking major refining centres with underserved markets that have historically depended on imported petroleum products and fragmented distribution channels.
“We are very aggressive with that,” he said, in response to questions about the Group’s plans for petroleum depots, pipelines and logistics infrastructure.
He revealed that the acquisition of a 25 per cent stake in Kenya’s petroleum pipeline network was achieved with the support of the Kenyan government and would significantly enhance the movement of refined petroleum products within the East African region.
“Just let me tell you, yesterday, with the support from the President of Kenya, we bought 25 percent of the pipeline network for the distribution of petroleum products,” Dangote disclosed.
The Group is also developing a major petroleum distribution corridor linking Djibouti and Addis Ababa, complete with storage terminals and tank farms designed to facilitate the efficient transportation and storage of refined products.
He added that another strategic project in Cameroon is nearing completion, while Namibia has been identified as a critical hub in the Group’s plan to penetrate Southern African markets.
Dangote described Namibia as a particularly attractive location because of its strategic proximity to the Dangote Petroleum Refinery and Petrochemicals (DPRP) in Lagos.
“From our refinery to Namibia is just about four days of steaming,” he noted.
According to him, refined products from the Lagos refinery will be transported to Namibia and distributed across interconnected markets, including Botswana and South Africa.
The Group is also examining other supply corridors extending into Zimbabwe and Zambia as part of its broader objective of developing a continental network supported by strategically located storage and transportation infrastructure.
The petroleum distribution expansion complements plans to establish another refinery in Lamu, Kenya, with a projected refining capacity of approximately 700,000 barrels per day.
Dangote noted that East Africa’s growing economies, vibrant mining sector and increasing energy demand make the region an attractive destination for refining investments.
He explained that the proposed refinery would source crude oil from multiple markets rather than depend exclusively on supplies from Kenya or Uganda, ensuring greater flexibility and long-term operational sustainability.
According to him, technical assessments identified Lamu as the preferred location because of its deep-water access, marine infrastructure and availability of critical resources required for large-scale refining operations.
Dangote revealed that the investment decision was concluded within four months, although he alleged that vested commercial interests attempted to delay the project through legal proceedings shortly before its public announcement.
Beyond energy infrastructure, Dangote strongly advocated policies aimed at protecting domestic industries from unfair competition, arguing that industrialisation cannot thrive if emerging African manufacturers are exposed to unrestricted imports from more established economies.
He questioned why African countries should be discouraged from supporting local industries when developed economies increasingly deploy similar measures to strengthen domestic manufacturing and employment.
Drawing parallels with recent developments in major global economies, he argued that industrial protection remains a legitimate and widely accepted economic strategy.
“If America is now saying, no, we are going to protect our industries, who are we in Africa not to protect our own industries?” he asked.
Dangote also disclosed that the Group has earmarked approximately $50 billion for investments between 2026 and 2030, describing the programme as part of a broader mission to demonstrate that African businesses can successfully execute transformative industrial projects at scale.
“The legacy we are trying to set up is how do we industrialise our continent?” he said.
According to him, the investment programme is designed not only to expand the Group’s operations but also to inspire other African entrepreneurs and investors to pursue ambitious industrial ventures capable of reshaping the continent’s economic future.
Looking beyond the energy sector, Dangote identified inadequate power supply, weak financial systems and underdeveloped industrial policies as major challenges constraining Africa’s economic growth.
He described electricity as a fundamental requirement for industrialisation, particularly in manufacturing, mining and mineral processing, where reliable power is essential for value addition.
With an estimated 650 million Africans still lacking access to electricity, he stressed that addressing the continent’s energy deficit would unlock significant opportunities for job creation, industrial development and economic diversification.
Questioning why a continent blessed with abundant natural resources, vast arable land and a young population continues to grapple with poverty, Dangote insisted that Africa possesses all the ingredients necessary to become a major industrial powerhouse.
Expressing optimism about the continent’s trajectory, he maintained that Africa’s industrial awakening has already begun.
“The journey has started,” Dangote declared. “But now we’re awake, and we will make it happen.”
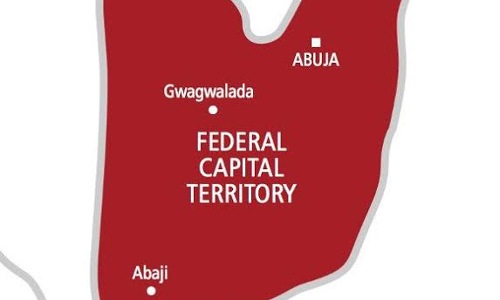
Some motorists and commuters in FCT have expressed mixed reactions to the N66-per-litre petrol discount offered by the Nigerian National Petroleum Company Ltd. as the Oct. 31 deadline approaches.
Speaking with the News Agency of Nigeria on Thursday, some of them commended the initiative while others expressed reservations about its impact.
NAN reports that the Federal Government announced a 30-day discount on petrol sold by the NNPC Ltd., with public transport operators to receive priority under the arrangement.
The Minister of Finance and Coordinating Minister of the Economy, Mr Taiwo Oyedele, said the arrangement was not a return to petrol subsidy.
READ ALSO: Thor Empowers Host Communities with 10 Cassava, Palm Oil Processing Plants
The minister said the government was also negotiating a ceiling of N1, 350 per litre on the ex-gantry or landing cost of petrol in an effort to reduce sharp fluctuations in pump prices.
NAN reports that Dangote Petroleum Refinery cut its gantry petrol price by N25 per litre from N1,350 to N1,325.
Mr Abubakar Saidu, a motorist who resides in Wuse, commended the Federal Government for the discount offered at NNPC Ltd. retail outlets.
Saidu stated that he purchased petrol through the app but sometimes had to wait in long queues before accessing the product.
He said that many Nigerians were unable to benefit from the discount due to network challenges.
“I downloaded the app and followed the procedure before buying the petrol at N1,339 per litre,” he said.
Another commuter who resides at Nyanya, Mr Obi Anyawu, said the intervention had not translated into lower transport fares.
Anyawu said the intervention had failed to ease the burden of high transportation costs on Nigerians.
According to him, commuters are still struggling to afford daily transportation to work.
“The transportation fare keeps increasing, and there has not been any difference,” he said.
Mrs Stephanie Okoro, a commuter who resides at Karu, said commuters were still struggling to afford daily transportation to work.
“I have not benefited from the intervention, and I have not seen any positive impact it has, even among the transporters.
“Commuters continue to face difficulties accessing affordable transportation, with many stranded at bus stops due to high fares,” she said.
Mr Jide Oyetola, a motorist who resides in Bwari, called for a comprehensive review of the intervention and the introduction of additional measures to alleviate the hardship faced by Nigerians.
Oyetola urged the government to explore alternative measures to reduce transportation costs and ease the economic burden on citizens.
“My secretary recently complained that her salary can no longer cover her transportation expenses.
“She said she might not be able to come to work five days a week because her salary can no longer cover her transportation costs.
“Even if she waits for a cheaper bus every morning, the situation will still not be manageable. You cannot blame her. I am sure she is not alone in that plight,” he said.
He said it forced her to consider reducing the number of days she would report to work.
Mrs Nonye Obanla, a commuter who resides at Dutse, urged the government to explore alternative measures to reduce transportation costs and ease the economic burden on citizens.
Courtesy – NAN

Dangote Identifies Power, Financing as Possible Keys to Africa’s Industrial Revolution

Dangote Calls for Stronger Protection of Local Industries, Unveils Pan-African Energy Distribution Network

NMDPRA Issues Updates on Q3 Crude Supplies to Domestic Refineries

FCT Motorists, Commuters Divided over NNPC Petrol Discount

Two Suspected Political Thugs Killed After Attacking NDC Candidate’s Convoy in Ebonyi

Shettima Arrives Maiduguri to Commission Hospital, Schools, 104 Housing Units

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart