Business
U.S. Stocks Make Gains


WASHINGTON – U.S. stocks advanced, with defensive sectors outperforming broader benchmarks amid rising investor hopes for continued easy-money policies from central banks.
The Dow Jones Industrial Average advanced 87 points, or 0.6%, to 15706 in midday trading. On Tuesday, the Dow erased an early loss of as much as 117 points to close down 21 points, or 0.1%.
The S&P 500 climbed four points, or 0.2%, to 1767. It is up 24% year to date. The Nasdaq Composite Index slipped 14 points, or 0.4%, to 3926.
Better-than-expected economic data from the U.S. and Europe supported stock-market gains in early trading. But Friday’s closely watched October employment report will take top billing for markets, as investors try to determine when the Federal Reserve could start paring its easy-money policies. The partial government shutdown is expected to weigh on Friday’s report.“Everyone is just watching the Fed,” said John Fox, director of research with Fenimore Asset Management, which manages $1.8 billion. But he isn’t expecting an imminent pullback, as “the employment number could be modest.”
Telecommunications and utilities sectors led gainers in the S&P 500, adding 1.2% and 0.8%, respectively. Those sectors often trade as proxies for the bond market, and sold off sharply over the summer, after the Fed said it would consider paring back on its bond-buying program.
Fed officials have said they will pay close attention to the labor market to determine when the economy is strong enough to weather a paring of stimulus efforts. A recent paper from a central-bank official argued that unemployment could need to fall much lower before rate increases would be effective, which helped support gains in Treasury prices Wednesday. The yield on the 10-year note fell to 2.640% from a three-week high of 2.662% late Tuesday.
In Europe, stocks gained after better-than-expected economic data and as expectations remained that the European Central Bank may also act to bolster the economy, possibly as soon as Thursday’s policy decision.
“Investors will be watching the ECB announcement closely in light of last week’s euro-zone inflation report, which was worryingly low,” said Stephen Macklow-Smith, a European equities portfolio manager at J.P. Morgan Asset Management, which oversees $1.5 trillion of assets. “It’s possible the ECB will decide to trim interest rates at the margin.”
In the U.S., an index tracking forward-looking economic indicators rose by more than expected. The Conference Board’s Leading Economic Index for September rose 0.7% on the month, while a rise of 0.6% was forecast.
The latest data “just shows that the global economy is doing well,” said Chris Gaffney, senior market strategist with EverBank Wealth Management. The gains reflect “general confidence on the global growth story.”
The Nasdaq Composite underperformed but tech stocks in the S&P 500 gained, as investors waited for social-media company Twitter’s initial public offering, expected Thursday.
Joseph Greco, managing director of trading with brokerage firm Meridian Equity Partners, said money-manager clients focusing on technology were trimming some holdings in the sector, so they could have cash on hand to invest in the stock.
“People are clearing up some capital,” he said. “If you [invest in] the media space, your fund has to own some.”The pricing of Twitter’s initial public offering is due late in the day Wednesday. The social-media company raised its proposed price range to between $23 and $25 a share this week, up from between $17 and $20 a share, amid strong demand. That increases the potential size of the IPO to $2 billion from $1.6 billion.
In earnings news, Tesla Motors tumbled after the electric-car maker reported third-quarter results. Adjusted earnings and revenue were above analyst estimates but not by as much as many investors had hoped. In addition, Model S deliveries in the quarter were less than some analysts were expecting.
Tesla shares had gained 32% since the second-quarter report, and by more than 400% year to date.
Abercrombie & Fitch slid after the teen-apparel retailer reported revenue that fell more than expected, weighed down by sharp declines in U.S. and international same-store sales. The company also said it plans to close all of the stand-alone Gilly Hicks stores, its intimate-apparel brand, by the fiscal first quarter.
Earlier, the Mortgage Bankers Association said its seasonally adjusted mortgage applications index fell 7% in the latest week amid declines in both refinancings and purchase activity.December crude-oil futures rose 1.6% to $94.89 a barrel, after settling at a five-month low on Tuesday. Gold futures gained 0.6% to $1,315.80 a troy ounce. The dollar was mixed, edging higher against the yen but easing against the euro.
The Stoxx Europe 600 was up 0.3% on the positive data and ECB hopes. Germany’s DAX 30 index advanced 0.3%, France’s CAC 40 index climbed 0.7% and the U.K.’s FTSE 100 index edged down 0.1%.
Data firm Markit said its October composite purchasing managers index for the euro area slipped to 51.9 from 52.2 in September, but was revised up slightly from an earlier reading. Readings above 50 indicate expansion.
In addition, the services PMI for the euro zone fell to 51.6 in October from September’s 52.2, but topped expectations of 50.9. And U.K. industrial production for September rose 0.9% on the month versus expectations of a 0.5% increase.
Asian markets were mixed. Japan’s Nikkei Stock Average rose 0.8%, supported by a weaker yen, while China’s Shanghai Composite fell 0.8%.
– WALL STREET JOURNAL
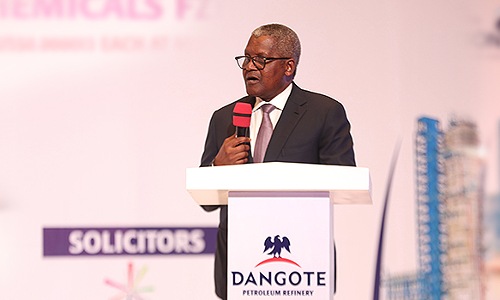
Africa’s ambition of becoming a global industrial powerhouse hinges on its ability to mobilise long-term financing, deliver reliable electricity and adopt policies that turn its vast natural resources into manufactured products.
The President/Chief Executive, Dangote Industries Limited, Aliko Dangote expressed these views in London at the Financial Times Africa Summit during a conversation with David Pilling the Africa Editor of the newspaper.
Dangote, who has outlined a $50 billion investment programme for 2026 to 2030, said the continent must build stronger financial institutions capable of funding large-scale industrial projects, expand electricity infrastructure and establish policies that encourage domestic manufacturing, value addition and economic diversification.
The industrialist maintained that Africa possessed the natural resources, population and investment opportunities required to become a global manufacturing powerhouse, but needed stronger institutions and infrastructure to translate those advantages into sustainable economic prosperity.
Responding to a question on why Africa had produced relatively few industrial enterprises of global scale despite its enormous economic potential, Dangote stressed the need for deliberate policies and institutions capable of supporting long-term industrial investment.
READ ALSO: Thor Empowers Host Communities with 10 Cassava, Palm Oil Processing Plants
The Africa Summit by the FT is a prestigious platform for Africa’s most influential leaders and this year’s Summit lived up to its billing convening leading policymakers, business leaders, financiers and visionaries to explore how Africa can contribute meaningfully to shape the next era of global development.
Dangote said, “I think the number one thing that the continent has to concentrate on doing is having very strong financial institutions, their own financial institutions, and also to have very strong agricultural policy, and also industrial policy”.
He maintained that infrastructure development was equally important but singled out electricity as perhaps the most urgent requirement for unlocking Africa’s industrial potential, adding; “For Africa, what we need the most today is actually power,” he declared.
Dangote explained that inadequate electricity supply continued to undermine Africa’s ability to process its mineral resources locally, forcing countries to export raw materials rather than capture the greater economic value associated with manufacturing and processing. He cited the mining industry as a particularly striking example, noting that companies frequently identified unreliable electricity supply as a major reason for their inability to establish processing facilities close to extraction sites.
According to him, approximately 650 million Africans remain without access to electricity, a deficit he described as fundamentally incompatible with the continent’s industrial ambitions.
He argued that resolving the power crisis would transform Africa’s manufacturing prospects, encourage investment in mineral processing and create substantial employment opportunities.
The industrialist also drew on his experience developing the Dangote Petroleum Refinery and Petrochemicals (DPRP) in Lagos to illustrate how Africa’s financing environment could frustrate even commercially promising projects.
He disclosed that the Group had been compelled to finance the refinery against its own balance sheet rather than depend on conventional project financing, which he described as extremely difficult to secure for major African industrial investments.
He explained that prolonged financing negotiations could undermine the viability of industrial projects by delaying execution, increasing costs and exposing investors to changing economic conditions.
For the Dangote Group, the decision to proceed with the refinery without conventional project finance involved extraordinary financial risks, compounded by severe currency depreciation and the enormous cost of developing supporting infrastructure. Dangote said the exchange rate moved from approximately ₦136 to the dollar to as high as ₦1,800 during the refinery’s development, while about 90 percent of the Group’s revenue was denominated in naira.
Dangote said the Group’s proposed $50 billion investment programme was designed partly to encourage other Africans to recognise the opportunities available across the continent.
“The legacy we are trying to set up is how do we industrialise our continent?” he said.
He explained that the Group intended to expand its investments between 2026 and 2030 to demonstrate that African businesses could execute large-scale projects and encourage other investors to participate in developing the continent. The ambition, he stressed, extended beyond the growth of one conglomerate to creating a wider industrial ecosystem capable of supporting businesses, generating employment and retaining more economic value within Africa.
Dangote also challenged African governments to reconsider their approach to industrial protection, warning that allowing cheap imported products to undermine domestic manufacturing could permanently weaken the continent’s productive capacity. He argued that emerging African industries required appropriate policy support to compete against established international manufacturers, particularly where imported products were sold at prices that discouraged investment in local factories.
He, however, distinguished industrial protection from restrictions on trade between African countries, advocating a regional approach that would strengthen manufacturing while preserving the objectives of the African Continental Free Trade Area. He maintained that African economies should trade more freely among themselves while establishing a common framework to protect their industries against unfair external competition.
The industrialist also questioned why Africa continued to experience widespread poverty despite its extensive agricultural land, mineral resources and youthful population.
He cited the continent’s natural endowments as evidence that Africa’s economic challenges were not principally the result of inadequate resources but of insufficient productive investment and industrial capacity. “Why should we remain poor?” he asked.
Dangote expressed confidence that the continent was entering a period in which African governments, entrepreneurs and investors were becoming increasingly determined to develop their own productive capabilities.
Business
Dangote Calls for Stronger Protection of Local Industries, Unveils Pan-African Energy Distribution Network

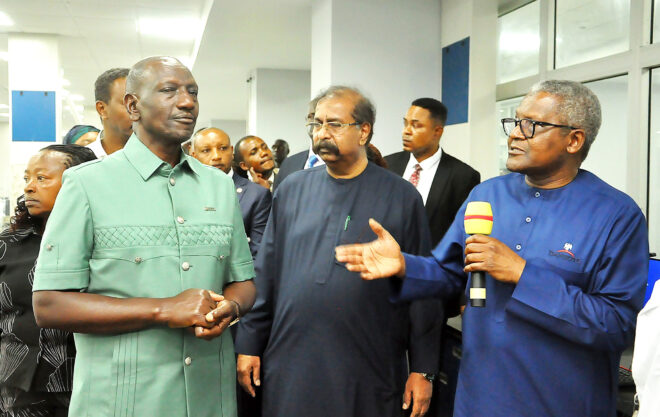
President and Chief Executive of Dangote Industries Limited (DIL), Aliko Dangote, has urged African governments to adopt policies that protect domestic industries and accelerate industrialisation.
He made the call in London, during the FT Africa Summit where he vented plans to establish an extensive petroleum distribution network across Africa through strategic investments in pipelines, storage facilities and supply corridors.
According to Dangote, the Group is aggressively expanding its petroleum logistics and distribution infrastructure across East, Central and Southern Africa as part of efforts to strengthen energy security, improve access to refined products and eliminate longstanding supply bottlenecks across the continent.
During a wide-ranging interview with Financial Times Africa Editor, David Pilling, the industrialist disclosed that the Group recently acquired a 25 percent stake in a petroleum products pipeline network in Kenya and is pursuing additional infrastructure projects connecting Djibouti and Ethiopia, alongside investments in Cameroon and Namibia.
READ ALSO: NMDPRA Issues Updates on Q3 Crude Supplies to Domestic Refineries
According to him, Africa’s aspiration for economic transformation will remain difficult to achieve without significant investments in infrastructure combined with industrial policies that promote local manufacturing, preserve productive capacity and create sustainable employment opportunities.
“Allowing imports to displace local production means we are exporting our jobs out of the continent and importing poverty into the continent,” Dangote said.
Dangote explained that the expansion forms part of a broader strategy to develop an interconnected African energy supply system capable of linking major refining centres with underserved markets that have historically depended on imported petroleum products and fragmented distribution channels.
“We are very aggressive with that,” he said, in response to questions about the Group’s plans for petroleum depots, pipelines and logistics infrastructure.
He revealed that the acquisition of a 25 per cent stake in Kenya’s petroleum pipeline network was achieved with the support of the Kenyan government and would significantly enhance the movement of refined petroleum products within the East African region.
“Just let me tell you, yesterday, with the support from the President of Kenya, we bought 25 percent of the pipeline network for the distribution of petroleum products,” Dangote disclosed.
The Group is also developing a major petroleum distribution corridor linking Djibouti and Addis Ababa, complete with storage terminals and tank farms designed to facilitate the efficient transportation and storage of refined products.
He added that another strategic project in Cameroon is nearing completion, while Namibia has been identified as a critical hub in the Group’s plan to penetrate Southern African markets.
Dangote described Namibia as a particularly attractive location because of its strategic proximity to the Dangote Petroleum Refinery and Petrochemicals (DPRP) in Lagos.
“From our refinery to Namibia is just about four days of steaming,” he noted.
According to him, refined products from the Lagos refinery will be transported to Namibia and distributed across interconnected markets, including Botswana and South Africa.
The Group is also examining other supply corridors extending into Zimbabwe and Zambia as part of its broader objective of developing a continental network supported by strategically located storage and transportation infrastructure.
The petroleum distribution expansion complements plans to establish another refinery in Lamu, Kenya, with a projected refining capacity of approximately 700,000 barrels per day.
Dangote noted that East Africa’s growing economies, vibrant mining sector and increasing energy demand make the region an attractive destination for refining investments.
He explained that the proposed refinery would source crude oil from multiple markets rather than depend exclusively on supplies from Kenya or Uganda, ensuring greater flexibility and long-term operational sustainability.
According to him, technical assessments identified Lamu as the preferred location because of its deep-water access, marine infrastructure and availability of critical resources required for large-scale refining operations.
Dangote revealed that the investment decision was concluded within four months, although he alleged that vested commercial interests attempted to delay the project through legal proceedings shortly before its public announcement.
Beyond energy infrastructure, Dangote strongly advocated policies aimed at protecting domestic industries from unfair competition, arguing that industrialisation cannot thrive if emerging African manufacturers are exposed to unrestricted imports from more established economies.
He questioned why African countries should be discouraged from supporting local industries when developed economies increasingly deploy similar measures to strengthen domestic manufacturing and employment.
Drawing parallels with recent developments in major global economies, he argued that industrial protection remains a legitimate and widely accepted economic strategy.
“If America is now saying, no, we are going to protect our industries, who are we in Africa not to protect our own industries?” he asked.
Dangote also disclosed that the Group has earmarked approximately $50 billion for investments between 2026 and 2030, describing the programme as part of a broader mission to demonstrate that African businesses can successfully execute transformative industrial projects at scale.
“The legacy we are trying to set up is how do we industrialise our continent?” he said.
According to him, the investment programme is designed not only to expand the Group’s operations but also to inspire other African entrepreneurs and investors to pursue ambitious industrial ventures capable of reshaping the continent’s economic future.
Looking beyond the energy sector, Dangote identified inadequate power supply, weak financial systems and underdeveloped industrial policies as major challenges constraining Africa’s economic growth.
He described electricity as a fundamental requirement for industrialisation, particularly in manufacturing, mining and mineral processing, where reliable power is essential for value addition.
With an estimated 650 million Africans still lacking access to electricity, he stressed that addressing the continent’s energy deficit would unlock significant opportunities for job creation, industrial development and economic diversification.
Questioning why a continent blessed with abundant natural resources, vast arable land and a young population continues to grapple with poverty, Dangote insisted that Africa possesses all the ingredients necessary to become a major industrial powerhouse.
Expressing optimism about the continent’s trajectory, he maintained that Africa’s industrial awakening has already begun.
“The journey has started,” Dangote declared. “But now we’re awake, and we will make it happen.”
Some motorists and commuters in FCT have expressed mixed reactions to the N66-per-litre petrol discount offered by the Nigerian National Petroleum Company Ltd. as the Oct. 31 deadline approaches.
Speaking with the News Agency of Nigeria on Thursday, some of them commended the initiative while others expressed reservations about its impact.
NAN reports that the Federal Government announced a 30-day discount on petrol sold by the NNPC Ltd., with public transport operators to receive priority under the arrangement.
The Minister of Finance and Coordinating Minister of the Economy, Mr Taiwo Oyedele, said the arrangement was not a return to petrol subsidy.
READ ALSO: Thor Empowers Host Communities with 10 Cassava, Palm Oil Processing Plants
The minister said the government was also negotiating a ceiling of N1, 350 per litre on the ex-gantry or landing cost of petrol in an effort to reduce sharp fluctuations in pump prices.
NAN reports that Dangote Petroleum Refinery cut its gantry petrol price by N25 per litre from N1,350 to N1,325.
Mr Abubakar Saidu, a motorist who resides in Wuse, commended the Federal Government for the discount offered at NNPC Ltd. retail outlets.
Saidu stated that he purchased petrol through the app but sometimes had to wait in long queues before accessing the product.
He said that many Nigerians were unable to benefit from the discount due to network challenges.
“I downloaded the app and followed the procedure before buying the petrol at N1,339 per litre,” he said.
Another commuter who resides at Nyanya, Mr Obi Anyawu, said the intervention had not translated into lower transport fares.
Anyawu said the intervention had failed to ease the burden of high transportation costs on Nigerians.
According to him, commuters are still struggling to afford daily transportation to work.
“The transportation fare keeps increasing, and there has not been any difference,” he said.
Mrs Stephanie Okoro, a commuter who resides at Karu, said commuters were still struggling to afford daily transportation to work.
“I have not benefited from the intervention, and I have not seen any positive impact it has, even among the transporters.
“Commuters continue to face difficulties accessing affordable transportation, with many stranded at bus stops due to high fares,” she said.
Mr Jide Oyetola, a motorist who resides in Bwari, called for a comprehensive review of the intervention and the introduction of additional measures to alleviate the hardship faced by Nigerians.
Oyetola urged the government to explore alternative measures to reduce transportation costs and ease the economic burden on citizens.
“My secretary recently complained that her salary can no longer cover her transportation expenses.
“She said she might not be able to come to work five days a week because her salary can no longer cover her transportation costs.
“Even if she waits for a cheaper bus every morning, the situation will still not be manageable. You cannot blame her. I am sure she is not alone in that plight,” he said.
He said it forced her to consider reducing the number of days she would report to work.
Mrs Nonye Obanla, a commuter who resides at Dutse, urged the government to explore alternative measures to reduce transportation costs and ease the economic burden on citizens.
Courtesy – NAN

Tinubu Congratulates Lula on Re-Election, Seeks Stronger Nigeria-Brazil Ties

Ebola: IGP Warns Nigerians Against Contact With Suspected Patients’ Body Fluids
‘Nigeria Cannot Do What China Did’ – Oxford Economist Warns

Peter Obi Demands Release of Rilwan Olawale, Accuses Tinubu of Undermining Democracy
Fears of Fresh US Strikes on Iran Fuels Crude Price Surge

Navy Uncovers 132,000 Litres of Stolen Crude Oil in Bonny

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart