Energy
Seplat Energy ratings Upgraded to ‘B’ by Fitch, Outlook Stable

Precious ADELOLA
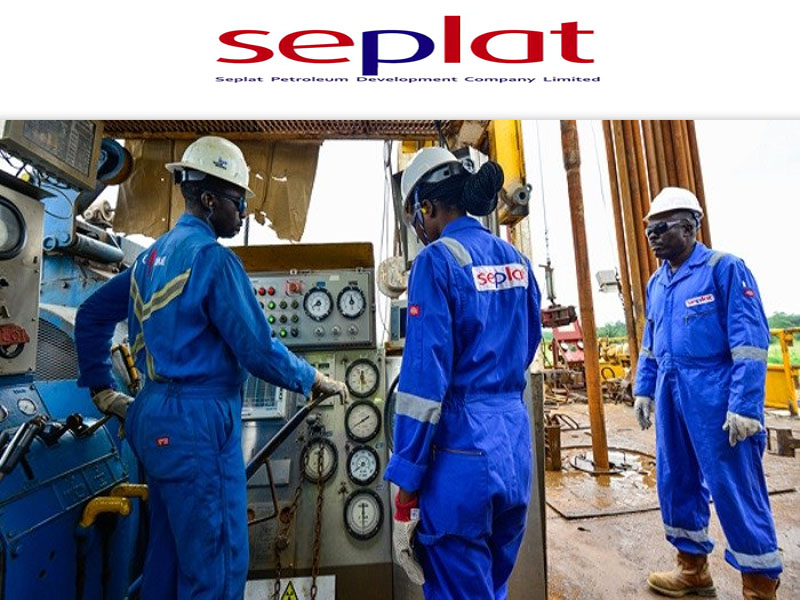
LONDON, UK – Seplat Energy Plc (“Seplat Energy” or “the Company”), a leading Nigerian independent energy company listed on both the Nigerian Exchange Limited and the London Stock Exchange, has been upgraded to ‘B’ from ‘B-‘ by Fitch Ratings on its Long-Term Issuer Default Rating (IDR).
Fitch also confirms Seplat Energy’s Outlook to be ‘Stable’ and upgraded the Company’s senior unsecured rating for USD650 million senior notes due 2026 to ‘B’ from ‘B-‘, with a Recovery Rating of ‘RR4’.
The rating agency stated: “The upgrade reflects improved financial flexibility and a strong liquidity profile following debt refinancing in 2021, which in our view will help Seplat Energy survive for more than two years of force majeure without access to the Trans Forcados Pipeline (TFP). Amukpe-Escravos Pipeline (AEP), an alternative oil export route, has been completed and is undergoing commissioning, according to Seplat, but there is no certainty around when it will ship its first oil.”
The rating incorporates the small scale of Seplat Energy’s cash flows, concentration of the company’s asset base in Nigeria (B/Stable) and a historically unstable operating environment in the troubled Niger Delta, including recurring issues with the oil transportation system. The rating also reflects moderate leverage, conservative financial policies, competitive unit profitability, end-2020 2P reserve life of 27 years, and a growing domestic gas business.
Specifically, Fitch upgraded Seplat Energy’s $650m bonds to B from B-. The upgrade reflects improved financial flexibility and a strong liquidity profile following debt refinancing in 2021. Because of Seplat Energy’s prudent approach to financial management, Fitch believes the company has built a very strong balance sheet. Even if the Trans Forcados Pipeline was in force majeure for an unprecedented two years, Seplat Energy has sufficient strength to survive and service its debt interest
Fitch view is underpinned by its view of Seplat Energy’s prudent debt management, flexibility on dividends and flexibility to deploy capex. Fitch sees Seplat Energy’s gas business as having potential to enhance cash flows, particularly after ANOH comes onstream; ANOH itself is already fully funded
Fitch lauds Seplat Energy’s ESG efforts and notes deeper communication and cooperation between local communities, the government and Seplat have significantly reduced the number of attacks on oil infrastructure.
KEY RATING DRIVERS
Resilience to Prolonged Pipeline Disruption: Seplat Energy’s debt refinancing in 2021 has resulted in no maturities in 2022 and just USD27 million of maturities in 2023. Its debt repayments are USD44 million in 2024 and USD40 million in 2025. We expect Seplat to be able to service its debt even in the extreme scenario that its export route via TFP is not operational in 2022-2023. It had USD220 million of unrestricted cash at 30 September 2021, and it should be able to generate cash flows from its eastern assets and use the expensive Warri refinery export route for its western assets if TFP is shut down.
Continued Delays with AEP: Following multiple delays since 2014, Seplat Energy’s latest guidance on AEP’s first oil flow is December 2021. Seplat also needs to agree offtake terms for the oil before shipments can begin. The start of oil deliveries though AEP remains uncertain, in our opinion. AEP will allow oil exports of 40 kb/d, reducing over-reliance on the TFP export route that had adversely affected Seplat in the past. The underground AEP should materially improve the pipeline uptime (74% in 9M21 for TFP) and shrink losses from crude theft and reconciliation (11%).
Small Nigerian E&P Company: Seplat Energy’s operations are concentrated around the Niger Delta region of Nigeria. The Nigerian oil and gas sector is characterised by high operational risks and regulatory uncertainty. Its main assets are oil mining leases (OMLs) 4, 38 and 41, which accounted for around 79% of 9M21 production and are reliant on the TFP. We expect Seplat to ramp up its daily oil and gas output to 59 thousand barrels of oil equivalent per day (kboe/d) until 2024 from 47 kboe/d in 9M21. In our view, OPEC+ cuts, which are gradually being unwound, will not hinder Seplat’s production growth.
Inorganic Growth: Fitch expects Seplat Energy’s management to actively seek opportunities for inorganic growth in Nigeria. Domestic opportunities exist as oil majors continue to streamline their portfolios, exiting Nigeria. Seplat Energy’s ability to expand through acquisitions is boosted by an undrawn USD350 million revolving credit facility (RCF). We view Seplat’s financial policies as conservative for the rating with funds from operations (FFO) net leverage averaging 1.7x in 2021-2025. Our view is underpinned by debt management, flexibility on dividends and on capex, as seen during the TFP non-availability in 2016-2017. We view large acquisitions as an event risk.
Gas Business Provides Stability: Seplat Energy’s growing footprint in the domestic gas market will enhance cash flow stability as gas sales benefit from more predictable domestic gas prices than oil. Nevertheless, regulated gas price under domestic supply obligation for power generation (around 30% of Seplat’s gas volumes) was lowered in July 2021 to USD2.18 per thousand cubic feet (kcf) from USD2.5/kcf, after having been flat through 2014-2020. Seplat sells the rest of its gas to commercial companies at contract prices averaging USD2.9/kcf. Its gas production was 19 kboe/d in 9M21, or 41% of total hydrocarbon volumes.
ANOH Plant Scheduled for 1H22: ANOH gas processing plant (GPP) – which is 50%/50%-owned by Seplat and Nigerian Gas Company Limited (NGC) – underpins the former’s effort to further expand gas operations, adding 300 kcf/d to its existing 465 kcf/d gross processing capacity. The JV partners have finalised non-recourse debt funding for the project, which is an important milestone. Seplat expects to start receiving dividends from 2023, although we conservatively do not include any contribution in our rating case. Seplat is also marginally expanding its GPP at Sapele and adding liquefied petroleum gas unit to it.
Income Tax Capital Allowance: Seplat Energy pays income tax that is reduced by its accumulated capital allowance derived from historical expenditures. We forecast its effective income tax rate on oil production to remain considerably below the nominal 85% until its USD747 million capital allowance at end-3Q21 is exhausted. We conservatively assume that Seplat will start paying significantly higher income taxes in 2025, based on our oil-price assumptions. Seplat has an option to remain in the current tax regime until its concession terms expire despite the enactment of the new tax system in 2021.
ESG – Social: Fitch has revised Seplat Energy’s ESG Relevance Score for Human Rights, Community Relations, Access & Affordability to ‘4’ from ‘5’ as deeper communication and cooperation between local communities, the government and Seplat Energy has significantly reduced the number of attacks on oil infrastructure. The uptime in recent years was 74% in 9M21, 83% in 2020, 92% in 2019 and 85% in 2018, compared with 50% in 2017.
Seplat Energy’s upstream operations focus on the troubled Niger Delta region. Historically, this area has been a high-risk environment driven by militancy, crude oil theft, pipeline sabotage, as well as environmental pollution arising from militant strikes against oil infrastructure. TFP was shut down for 305 days in 2016 and more than 182 days in 2017, adversely affecting the company’s operations.
– End –






The Group of Seven (G7) has resolved to release up to 100 million barrels of crude oil and petroleum products from strategic stocks.
An analyst at Argus Media, Sarah Raffoul, has expressed the view that this might mount pressure on European diesel prices in the short term.
Canada, France, Germany, Italy, Japan, the United Kingdom and the United States, constitute the G7, though the European Union (EU) also participates in the group’s meetings.
READ ALSO: Petrol Tanker Fire Ravages Houses, Vehicles in Calabar
The G7 concerns itself with major global economic, energy, security and international issues.
According to Raffoul, the coordinated release, which includes a front-loaded diesel release, is likely to ease immediate supply concerns and weaken risk premiums as additional barrels become available during the early part of the winter season.
“The measure is likely to reduce prompt market tightness and weaken risk premiums as additional barrels become available during the early part of the winter season, although the final breakdown between crude and products has yet to be disclosed,” she said.
Raffoul added that the impact is expected to be felt mostly in October and November, when most of the released volumes are likely to reach the market.
She said the announcement also reduces concerns over export restrictions and includes commitments to maximise refinery utilisation, further improving confidence in near-term diesel availability.
However, Raffoul said the release does not fundamentally change the broader supply outlook because the additional barrels are being drawn from existing inventories rather than new production.
“The additional barrels are being drawn from existing inventories rather than new production, meaning the measure provides temporary relief rather than a lasting increase in supply,” she said.
She noted that several factors continue to support diesel fundamentals, including unplanned refinery outages in Asia, uncertainty surrounding Chinese export volumes and continued restrictions on Russian diesel exports.
“Europe also remains reliant on imports to balance its diesel market, leaving it exposed to disruptions in global trade flows,” Raffoul said.
She said the stock release is likely to cap further price increases and ease immediate supply concerns, but is unlikely to eliminate them entirely.
“OECD European diesel inventories remain relatively low by historical standards, while strengthening jet fuel markets have pushed the European jet-diesel regrade back into positive territory,” she said.
Raffoul added that the development suggests diesel values may need to strengthen relative to current levels to restore the normal relationship between the two products.
She said stronger refinery runs, Chinese export policy and sustained stock releases could leave the market more comfortably supplied than currently expected.
“On the other hand, further refinery disruptions, weaker exports, stronger winter demand or delays to inventory rebuilding could allow tightness to deepen once the effect of the stock release begins to fade,” she said.
Raffoul said the announcement points to softer European diesel prices in the near term, but noted that underlying fundamentals suggest any weakness is more likely to reflect a reduction in supply risk than a meaningful loosening of market balances.

Investment banker, development economist and former Imo State deputy governorship candidate, Dr. Nnaemeka Onyeka Obiaraeri, has described the 2026 Nigeria-US Solid Mineral Framework Agreement as structurally superior to Nigeria’s post-independence oil and gas joint-venture arrangements with international oil companies (IOCs).
Obiaraeri made the assertion in a post on X on Friday while comparing the newly signed minerals framework with Nigeria’s longstanding arrangements in the oil and gas sector.
According to him, the minerals agreement is different because of its emphasis on local value addition and processing.
SEE ALSO: Dangote Blames Marketers, IOCs for Lamu Refinery Protests
“The 2026 US-Nigeria Solid Mineral Framework Agreement is structurally superior to Nigeria’s post-independence Oil and Gas arrangements with International Oil Companies (IOCs),” Obiaraeri stated.
He argued that while oil joint ventures have primarily involved the extraction and export of crude oil, with limited domestic refining capacity historically, the new mining framework seeks to ensure that Nigeria does not remain merely a source of raw materials.
“The JV contract with the IOCs primarily involves the extraction and export of raw crude oil with minimal local refining capacity, whereas the new mining pact explicitly attempts to prevent Nigeria from remaining a mere source of raw materials,” he said.
Obiaraeri also said the framework comes with protection for the lives and participation rights of host communities.
He linked the issue to insecurity and illegal mining, alleging that indigenous communities have suffered deaths and hardship as a result of activities involving bandits and illegal mining networks.
“The Solid Mineral MOU also comes with protection of lives and participation rights of the host communities,” he said.
Recall that Nigeria and the United States signed a mineral investment framework in New York on September 24, 2026, aimed at attracting American investment into Nigeria’s estimated $700 billion mineral resources.
The agreement was signed by Minister of Solid Minerals Development, Dele Alake, and US Deputy Secretary of State Christopher Landau at Nigeria’s Mission House in New York.
The framework provides for cooperation in areas including geological data and exploration, mineral development and processing, infrastructure and technical capacity.
The Federal Government said the agreement is intended to promote a value-addition-driven mineral value chain and create greater opportunities for Nigerian businesses.
Nigeria’s oil and gas sector, meanwhile, has historically operated under several contractual arrangements involving the government and foreign oil companies, including joint ventures and production-sharing contracts.
Under the joint-venture model, NNPC Limited and IOC partners participate jointly in the development of petroleum assets according to their respective interests and the terms of the applicable agreements.
NNPC Limited, for instance, operates a joint venture with Chevron Nigeria Limited, with Chevron holding a 40 per cent interest and NNPC Limited holding the remaining 60 per cent in the relevant assets.
The partnership covers exploration and development activities in the Niger Delta.
Nigeria also uses production-sharing contracts for some petroleum developments, particularly in deepwater projects.
In August 2026, President Bola Tinubu approved a new deep-offshore investment framework intended to unlock up to $50 billion in investment, with NNPC Limited acting as the government’s nominated counterparty under the applicable production-sharing contracts.
Against this background, Obiaraeri said the new minerals framework provides an opportunity for Nigeria to adopt a different approach to its natural resources.
He argued that, rather than simply extracting and exporting resources, Nigeria should ensure that more processing, industrial activity and economic value remain within the country.
“I remain Nnaemeka Onyeka Obiaraeri,” he said, adding that he speaks “truth to power” and seeks to proffer solutions to national and subnational challenges.
With the completion of a nationwide gas-grid mapping exercise expected in October, the Nigerian Midstream and Downstream Petroleum Regulatory Authority (NMDPRA) has revealed that the digital licensing round for gas distribution areas will happen before the end of 2026.
The Authority Chief Executive, Engr. Rabiu Umar, made the disclosure on Wednesday at the Gas Investment Forum 2026, themed “Positioning Nigeria as Africa’s Global Gas Powerhouse.”
Umar said applicants would bid for gas distribution licences in designated areas across the country under a process similar to the award of Oil Mining Licences (OMLs) in the upstream sector.
“Under the licensing round, applicants will bid for gas distribution licences in the gridded areas available across the country, in the same way licensees apply for Oil Mining Licences (OMLs) in the upstream sector,” he said.
READ ALSO: MT Asharami Ghana Delivers 5,000MT LPG Cargo to Ghana
He said the initiative was part of efforts to move Nigeria from a fragmented gas-access system to an open-access regime that would allow more participants to use existing infrastructure.
“Without infrastructure, reserves are potential. They will continue to have potential,” Umar said.
“With infrastructure, gas becomes productivity and national resilience, especially in the light of the global headwinds that we see.”
According to him, the country needs infrastructure capable of moving gas from wellheads to processing plants, power stations, industrial clusters, transport corridors, homes and export terminals.
Umar said the Federal Government’s Decade of Gas Initiative was serving as an “engine of execution”, while NMDPRA was accelerating licences and approvals for gas processing plants, pipelines, storage facilities, compressed natural gas (CNG) and liquefied natural gas (LNG) projects.

Group Tackles Atiku on NNPC Ltd’s ₦11.2tn Federation Receivables

Ndindi Nyoro Gives Ruto 14 Days to Disclose Dangote Refinery Deal

Atiku Blows Lid on NNPC Ltd’s ₦11.2trn Receivables, Pipeline Contracts
Military Gear Found at Ondo Crash Site as Helicopter Burns to Rubble

JUST IN: Oluremi Tinubu Arrives BATICC for APC Women’s Pre-Inaugural Ceremony Arrives BATICC for APC Women’s Pre-Inaugural Ceremony

‘Nigerians Still Exposed to Kidnappers Despite Subsidy Savings for Security’ – Atiku

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart