Business
European Bonds Decline on Manufacturing Data as Kiwi Gain


LONDON – European government bonds fell after a report confirmed euro-area manufacturing expanded for a fifth month in November. The New Zealand and Australian dollars rallied as Asian economic reports beat estimates.
German 10-year bund yields climbed four basis points to 1.73 percent at 10:35 a.m. in London. Treasury 10-year note yields gained four basis points and the rate on similar-maturity gilts jumped seven basis points. The pound rose to its strongest level versus the dollar since August 2011, the kiwi jumped 0.8 percent and the Aussie added 0.3 percent.
The Stoxx Europe 600 Index fell 0.2 percent and Standard & Poor’s 500 Index (SPA) contracts were little changed. Gold dropped 0.8 percent while crude oil gained 0.4 percent.
Manufacturing in the euro area expanded, with Markit Economics’s factory index rising to 51.6 in November from 51.3 in October and an estimate for 51.5.
 The gauge in Spain fell to 48.6, the lowest since May, and compared with a forecast 51.1. Manufacturing indexes in China beat estimates for November as gauges in South Korea, India and Taiwan climbed. The U.S. Institute for Supply Management’s index was 55.1 in November, falling from the highest level since April 2011, according to the median economist forecast in a Bloomberg survey.
“The European PMIs were stronger than expected, apart from Spain, and this is weighing on bunds,” said Mathias Van Der Jeugt, a fixed-income strategist at KBC Bank NV in Brussels. “In the short term, the data limits the chance that the ECB will ease further. We believe U.S. manufacturing ISM can also beat consensus today and add downward pressure onto bunds.”
Treasuries, Gilts
Treasury 10-year notes rose to 2.79 percent and the rate on similar-maturity gilts climbed to 2.84 percent. Sterling gained 0.3 percent to $1.641 after advancing to $1.6443, the highest since Aug. 29, 2011.
New Zealand’s dollar strengthened against all of its 16 major counterparts, rising the most against the euro. Australia’s dollar strengthened to 91.32 U.S. cents.
The yen weakened 0.3 percent to 102.77 per U.S. dollar and the euro slipped 0.2 percent to $1.3561. Sterling jumped as much as 0.5 percent to $1.6443 before paring its advance to $1.6421.
The Stoxx Europe 600 Index dropped after falling as much as 0.3 percent after the Spanish data. Three stocks declined for every one that rose. The index gained 0.9 percent in November for a third consecutive monthly gain. The gauge has climbed 16 percent this year.
ThyssenKrupp AG slumped 7.8 percent after Germany’s largest steelmaker said it will sell equity equivalent to as much as 10 percent of its market value. ThyssenKrupp agreed to sell its U.S. steel plant to ArcelorMittal and Nippon Steel & Sumitomo Metal Corp. for $1.55 billion, the Essen-based company said in a Nov. 29 statement. ArcelorMittal gained 2.1 percent.
U.S. Futures
Futures (SPX) on the S&P 500 expiring this month declined less than 0.1 percent. The index advanced 27 percent this year and reached an all-time high on Nov. 27.
Spending on a Black Friday weekend fell for the first time since 2009. Purchases at stores and websites fell 2.9 percent to $57.4 billion during the four days beginning with the Nov. 28 Thanksgiving holiday, according to a survey commissioned by the National Retail Federation.
The MSCI Asia Pacific Index dropped 0.1 percent, Japan’s Topix rose less than 0.1 percent, while Australia’s S&P/ASX 200 slid 0.7 percent. Hong Kong’s Hang Seng Index added 0.7 percent and India’s Sensex gained 0.5 percent.
A Chinese index of small companies tumbled by a record after the government said it will resume initial public offerings. China’s securities regulator said 50 companies will be ready for IPOs by the end of January as authorities prepare to lift a more than one-year ban on new listings.
China Data
The Shanghai Composite Index dropped 0.6 percent, while the ChiNext Index sank 8.4 percent, paring this year’s gain to 76 percent. There are more than 760 companies in line for approval and it will take about a year to complete an audit of all the applications, the regulator said on Nov. 30.
“Investors are weighing the positive economic data that’s coming out from the different markets, trying to gauge if these are sufficient to extend the rally on equities,” Jonathan Ravelas, chief market strategist at BDO Unibank Inc., said in Manila. “The resumption of China IPOs will spur fund rotation to the newcomers on hopes these will provide better returns.”
China’s official manufacturing purchasing managers’ index came in at 51.4 for November, matching the 18-month high reached in October. The median projection in a Bloomberg News survey was for 51.1, with levels above 50 signaling expansion. A separate gauge from HSBC Holdings Plc and Markit Economics was 50.8, topping estimates. HSBC/Markit’s manufacturing index for South Korea rose to 50.4 from 50.2, while a measure for Taiwan output climbed to 53.4 from 53.
Emerging Markets
The MSCI Emerging Markets Index advanced 0.1 percent, headed for the highest level in almost two weeks. The Shanghai Stock Exchange Composite Index (SHCOMP) retreated 0.6 percent, snapping a three-day gain.
The Thai baht weakened to the lowest level since Sept. 9 versus the dollar as the central bank warned a political standoff was hurting Southeast Asia’s second-largest economy. Protesters seeking Prime Minister Yingluck Shinawatra’s ouster vowed to incite more unrest.
PT Bank Rakyat Indonesia led a 1.5 percent gain in the Jakarta Composite Index (JCI) and the rupiah jumped 1.6 percent after data showed a surprise trade surplus. Indian shares climbed to the highest level since Nov. 20 after data showed economic growth quickened last quarter from a four-year low.
The Indonesian rupiah headed for its biggest gain since May 2012. Exports exceeded imports by $42.4 million in October, compared with the median estimate for a $775 million deficit by economists surveyed by Bloomberg, official data showed today.
U.S. Debt
Global stocks beat all assets for a third month in November, the longest winning streak since 2009. The MSCI All-Country World Index of equities rose 1.5 percent including dividends as China pledged to expand economic freedoms, the European Central Bank cut interest rates and speculation increased the Federal Reserve will put off a paring of stimulus.
America’s banks have never been so wary of risking their cash deposits on U.S. government debt. Their $1.8 trillion of the bonds now equal less than 70 percent of their cash, the least since the Federal Reserve began compiling the data in 1973.
Gold, Crude
The cost of insuring corporate bonds against losses fell, with the Markit iTraxx Europe Index of credit-default swaps on 125 investment-grade companies decreasing 0.6 basis points to 78.8 basis points. The gauge fell to 77 basis points last week, the lowest since April 2010.
Gold for immediate delivery fell for the first time in three sessions in London trading, declining 1 percent to $1,237.50 an ounce. Copper declined 0.6 percent to $7,014.50 a metric ton on the London Metal Exchange, while aluminum traded 0.4 percent lower at $1,748.25 a ton, near a four-year low.
Crude oil was little changed at $93.73 a barrel in electronic trading on the New York Mercantile Exchange. Natural gas fell for the first time in eight days in New York, declining 0.8 percent and snapping the longest rising streak since January 2011.
Soybeans advanced 0.6 percent to $13.445 a bushel in Chicago after earlier touching $13.46, the highest in more than two months, on surging demand for U.S. supplies.
– BLOOMBERG

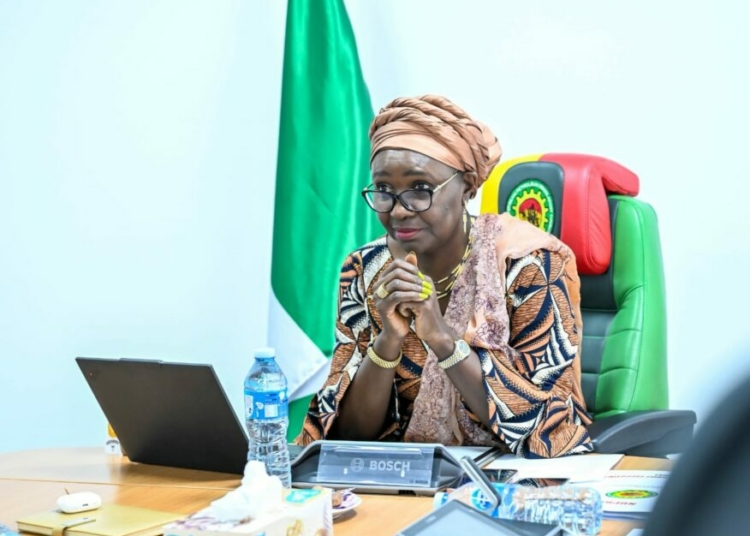
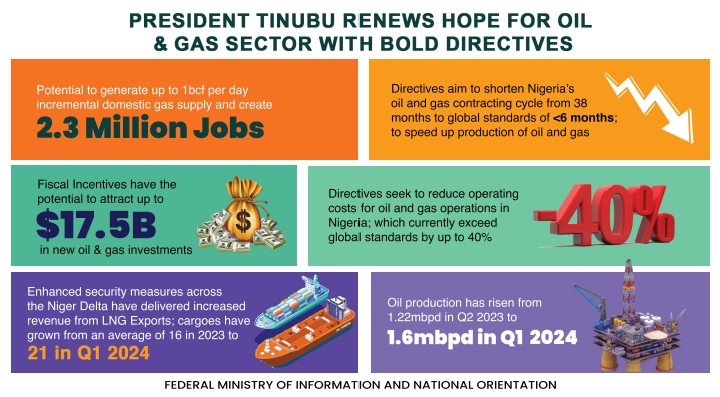
A total of 595 well re-entries and 145 new well-drilling operations, alongside 39 Field Development Plans (FDPs) have been approved in the first 10 months of 2026, as Nigeria intensifies efforts to ramp up crude oil production and attract fresh investments.
In addition, the Nigerian Upstream Petroleum Regulatory Commission (NUPRC) has sanctioned 740 drilling-related operations in the same period, as Nigeria’s total rig count rose to 100, with 46 currently active in drilling operations.
These details were made public during the management session of the 44th Annual International Conference and Exhibition of the Nigerian Association of Petroleum Explorationists (NAPE) in Lagos on Tuesday, by the Chief Executive (CE), NUPRC, Oritsemeyiwa Eyesan.
The conference is held under the theme, “Energy Security in an Era of Global Disruption: Positioning Nigeria for Resilience, Competitiveness, and Prosperity.”
The approvals, which underscore increased regulatory activity in the upstream petroleum sector. Eyesan, who was represented by the Deputy Director, Basinal Administration, NUPRC, Ahmad Abdullahi, said the increased approvals reflected improvements in the Commission’s regulatory processes, particularly the time required to grant operational clearances.
READ ALSO: Adeleke Clarifies Osun Debt Profile
According to her, faster approval processes have reduced delays and the additional costs incurred by operators while waiting for regulatory authorisation to execute projects.
“Year to date, about 39 FDPs have been approved. About 145 new well-drilling approvals granted. Year to date, about 595 well re-entry approvals were granted.
That goes to tell that as a commission, we have improved our approval time level, which again reduces costs that are being wasted or for projects to continue to wait for approval,” she said.
She explained that the Commission’s priority was to ensure that regulatory approvals translated into increased production and adequate energy supply.
“From the regulator’s perspective, to ensure that our energy security is not threatened, we must ensure that we approve Field Development Plans and new well-drilling applications to meet our production targets and guarantee energy availability,” Eyesan stated.
On drilling activities, the NUPRC boss said Nigeria’s rig count had increased by more than 300 per cent compared with the level recorded in 2021, reflecting renewed activities in the upstream industry.
“We have more than 100 rigs in country. About 46 rigs are actively involved in drilling year to date. If you compare this with maybe what we had in 2021, you will see that you have more than about 300 per cent increase,” she said.
Eyesan attributed the growth in investment activities to improved regulatory certainty, noting that investors were more willing to commit capital when they had confidence in the policy and operating environment.
She also identified the Petroleum Industry Act (PIA) as a major factor in rebuilding investor confidence, particularly in the acquisition of seismic data required for oil and gas exploration.
The NUPRC chief disclosed that multi-client seismic companies had invested more than $100 million in seismic data acquisition in Nigeria within three years of the enactment of the PIA.
“Based on our record, in the last three years, from the enactment of PIA, multi-client companies have invested more than $100 million in acquiring seismic data in Nigeria,” she said.
The investments are expected to deepen geological understanding of the country’s sedimentary basins, improve exploration decisions and support the discovery of additional hydrocarbon reserves.
On efforts to tackle crude oil theft and improve security across the industry, Eyesan said the Commission had introduced initiatives, including the Advanced Cargo Declaration programme and coordinated surveillance operations involving the Nigerian National Petroleum Company Limited (NNPC), private security operators such as Tantita Security Services and the Nigerian Navy.
She said the Commission’s responsibility went beyond punishing errant operators and perpetrators of oil theft.
According to her, the broader objective was to establish an operating environment in which legitimate crude oil production would be more profitable than crude oil theft.
President/Chief Executive, Dangote Industries Limited, Aliko Dangote, has declared that over 90,000 people are expected to be working at the group’s petroleum refinery & petrochemicals and fertiliser operations in Lagos next year.
This is as the group accelerates investments to create jobs, strengthen industrial production and transform agriculture across Africa.
Dangote, who disclosed this in an interview, also unveiled plans to establish 20 fertiliser blending plants in strategic locations across the continent to improve farmers’ access to essential inputs and support year-round supply. The projects form part of an investment programme that could reach $65 billion over four years, spanning refining, fertiliser, petrochemicals, power, pipelines and other businesses.
“The refinery expansion is huge. By next year, we expect to have almost 90,000 people working on the refinery and fertiliser projects in Lagos,” he said.
READ ALSO: Shell Commends Oil Industry Reforms as Key to Unlocking More Barrels
Dangote said creating opportunities for Africa’s youthful population was a central motivation for the group’s expansion, stressing that the continent needed more factories and greater domestic production to meet its growing needs. “My biggest concern is job creation in Africa. We have a very youthful population, and we are not creating enough jobs. We must push harder to create opportunities and keep our young people productively engaged,” he said.
The refinery expansion will add another 700,000 barrels per day of processing capacity, taking the planned total to about 1.4 million barrels per day, alongside additional petrochemical facilities and infrastructure. Beyond energy, Dangote outlined a fertiliser expansion programme designed to help turn Africa’s agricultural potential into greater production, more reliable food supplies and economic opportunities.
“We also plan to establish 20 blending plants in strategic locations across Africa. We intend to begin mining potash and phosphate in Congo-Brazzaville very soon,” he said.
He disclosed that the group was working towards nine million tonnes of urea capacity, with plans for 1.2 million tonnes of diammonium phosphate, DAP, and one million tonnes of NPK blending capacity in Lagos. Dangote said the objective was to ensure that farmers in countries hosting the group’s operations, as well as neighbouring markets, could obtain fertiliser when needed, without the uncertainty associated with lengthy import and delivery processes.
“What we want is for the countries where we operate, and their neighbours, to have fertiliser available 365 days a year. Farmers should be able to buy it when they need it, without worrying about supply,” he said.
Citing Ethiopia, he explained that fertiliser imports had to pass through Djibouti before being transported inland, creating logistical challenges that could leave supplies arriving after the planting season. “With local production, the fertiliser will be available there. We will also have one million tonnes of NPK capacity attached to the project,” he said.
Dangote linked the programme to his determination that Africa should build the capacity to meet its own agricultural input requirements, rather than remain vulnerable to disruptions in international markets. “At the beginning of the Russia–Ukraine crisis, the African Union went to Russia to plead for fertiliser. I said then that, within four years, Africa should never again have to go anywhere to beg for fertiliser,” he said.
He expressed confidence that sufficient access to gas would enable a much larger expansion in fertiliser production. “If Africa needs 30 million tonnes and we can secure enough gas, we can produce and supply it,” he said. “Africa has an enormous agricultural advantage. We must lead the effort to turn that opportunity into a major agricultural transformation.”
The group’s wider investment programme includes an initial ambition to develop 10,000 megawatts of power with some African countries and increase cement capacity to 100 million tonnes. Dangote said reliable electricity was essential to industrial growth, enabling African countries to process their raw materials, retain more value within their economies and create opportunities for their people. He disclosed that approximately $50 billion of the planned investment would go into existing businesses, while another $15 billion would be directed towards new ventures, including projects yet to be announced. The programme would be financed through a combination of free cash flow, internally generated equity and debt, he said.
Dangote urged African investors to take the lead in developing the continent, arguing that substantial domestic investment would encourage international capital to follow.
“I am tired of hearing about ‘potential’. We have been talking about Africa’s potential for decades. But Africans themselves must invest in their continent,” he said. “What gives other investors comfort and confidence is seeing us put our own money on the table. That is what we are trying to do. We are demonstrating that we are serious.”
He argued that sustained investment by African businesses was essential to unlocking the continent’s industrial and agricultural opportunities, while giving international investors the confidence to participate.
“Governments are always calling for foreign investors. But what attracts a foreign investor is a domestic investor,” he said. “We must demonstrate that we are doing something substantial in Africa so that others can join us.”
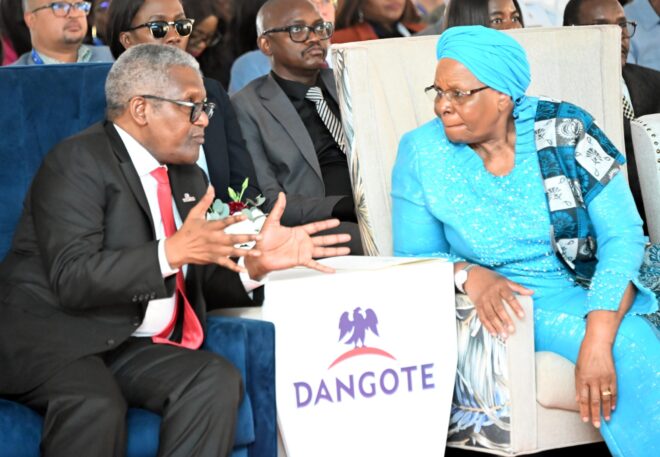
Photo Caption: Group President/Chief Executive, Dangote Industries Limited, Aliko Dangote (left), in conversation with the President of the Republic of Namibia, H.E. Dr Netumbo Nandi-Ndaitwah, during the official launch of the Dangote Namibia Tank Farm and Regional Pipeline Investment in Walvis Bay, Namibia, recently.
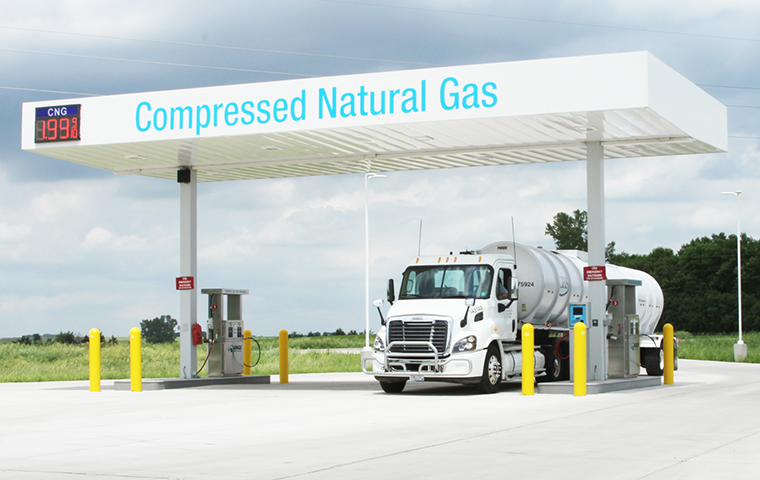
The quest for diversified fuel sources with a view to reducing cost of transportation has seen operational CNG stations in Nigeria rise to 106.
The Executive Chairman of the Presidential Initiative on Compressed Natural Gas and Electric Vehicles (Pi-CNG & EV), Barr. Ismaeel Ahmed, has stated this during the commissioning of a CNG Integrated Refueling Unit (IRU) Station by Pi‑CNG & EV and Rolling Energy, in Karu.
According to Ahmed, 170 stations are in different stages of development or waiting for different licences from the Nigerian Midstream and Downstream Petroleum Regulatory Authority (NMDPRA).
He added that investors are trooping into the sector as $2.6 billion worth of private investment has come in, adding that while most of the stations are privately-owned, the government is intervening with policies that will make their construction easy.
READ ALSO: Shettima Arrives Jigawa for APC Presidential Campaign Rally, Tinubu to Inaugurate Four Projects
He stated that it took Nigeria 60 years to get to 24,000 PMS stations but the rate of construction of CNG stations makes the country the fastest adoption rate for CNG and electric vehicles.
“We are moving at a scale that is very impressive. The work is in progress and a lot of entrepreneurs are seeing the need for this and they are coming in and we’re calling them to come in and invest more,” he said.
He added that the route where CNG buses are plying has led to reduction in transport fare but he said there is the need to do more in providing additional buses for fares to crash.
On his part, the State House Permanent Secretary, Temitope Fashedemi, said the use of CNG will help to reduce the burden of increasing the price of petrol.
He added that Nigerians will soon see the availability of the product when more investors build new stations and the Ajaokuta-Kaduna-Kano pipeline is completed.
“The stations will reduce the pressure in other places that we’re going to, and they can come here and refuel at any time, and even convert. And hopefully this will also be a clarion call for persons with the capacity to also set up things like this for the benefit of the citizens.”
The Chairman and Founder of Rolling Energy, Mubarak Umar Danbatta, said the station will help the government achieve its goals in ensuring that Nigeria is energy secure.

Rig Count Hits 100, as NUPRC Approves 740 Drilling Jobs

Adeleke Clarifies Osun Debt Profile

Ogun Police Deny Awujale Palace Siege, Explain Chief Gbenden’s Invitation

Peter Obi, Kwankwaso to Hold NDC Town Hall Meeting in Benue Today

2027: Obi Promises to Tackle Insecurity, Revive Plateau Tourism

Diaspora Investors Urged to Look Beyond Real Estate, Explore Nigeria’s Capital Market

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart