Business
Deflation Fears Rise in Europe


LONDON — Inflation rates are falling across much of Europe, adding to fears that some economies could be in danger of entering a damaging and prolonged period of falling prices.
Figures from Sweden, Hungary, Germany and Cyprus on Tuesday showed inflationary pressures weakened in October, echoing a dramatic cooling in inflation in the 17 nations that use the euro, which prompted the European Central Bank this month to cut its benchmark interest rate to a record low.
Even the U.K., which has grappled with much higher rates of inflation than its neighbors for most of the past five years, appears to be enjoying at least a temporary respite from rapid price increases, data showed.
 The slowdown in inflation, if sustained, should provide Europe’s central banks with extra time to support their economies with low interest rates and other easy-money policies. But it also raises the specter of deflation—a sustained fall in prices that can play havoc with public and private efforts to repay debts and bring consumer spending to a halt.
Figures from Sweden’s official statistics agency Tuesday showed the nation’s consumer-price index fell 0.1% on the year in October, the second annual fall in inflation this year.
In Hungary, the annual rate of consumer price inflation fell to 0.9% in October, the lowest level since 1974, according to official data.
And in Germany, Europe’s largest economy, data Tuesday confirmed the annual rate of inflation fell in October to 1.2%, its lowest level since April. Measured according to the European Union’s standard methodology, consumer prices in Cyprus fell 0.5% in the 12 months to October, having risen by 0.3% in the 12 months to September.
The slowdown in inflation last month in many cases reflected, at least in part, a fall in domestic fuel costs triggered by lower oil prices on international markets. But there are also indications that weak consumer demand is a contributing factor. The euro zone emerged from a lengthy contraction in the second quarter with modest growth, but unemployment remained at a record high in September, and with wages rising slowly, consumers have been reluctant to spend.
The euro zone’s annual rate of inflation fell to just 0.7% in October, well below the ECB’s target of just below 2%. The figures released Tuesday indicate that falling inflation rates—and outright deflation—are already a broader problem for Europe. The figures follow a warning from the European Bank for Reconstruction and Development Monday that there is a risk deflation in the euro zone could spread to neighboring countries in central and southeastern Europe.
In the U.K., the Office for National Statistics said annual inflation fell to 2.2% in October from 2.7% in September. The slowdown takes the annual rate to a level last seen in the U.K. in September 2012, and last lower in November 2009.
– WALL STREET JOURNAL

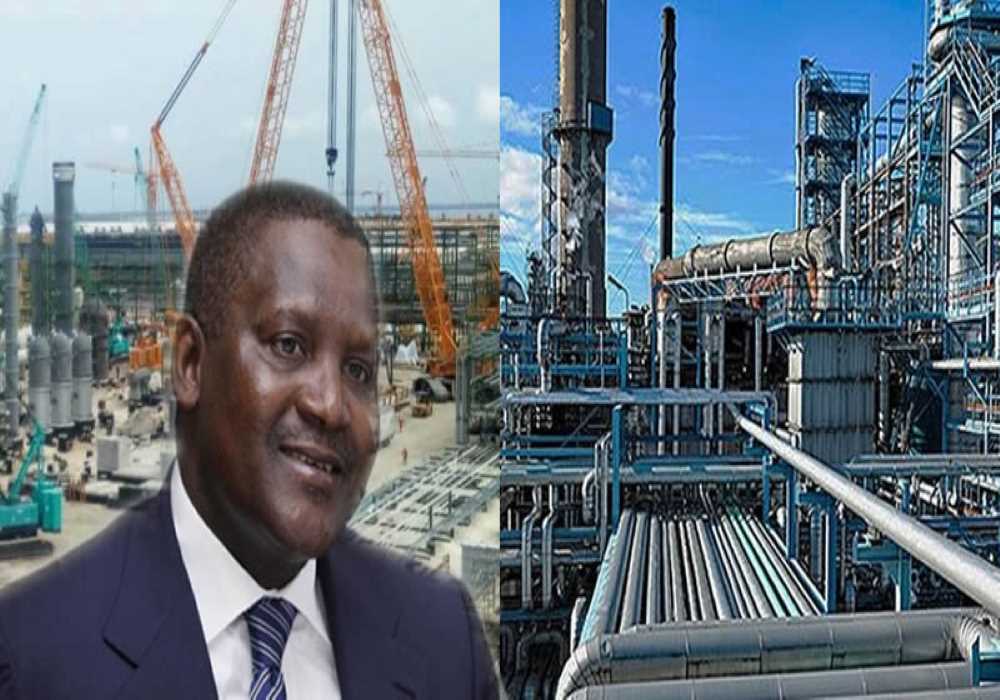
The President of Dangote Industries Limited (DIL), Aliko Dangote, has expressed support for the economic reforms of the President Bola Ahmed Tinubu administration, particularly the removal of the fuel subsidy and the liberalisation of the foreign exchange market.
The industrialist gave the commendation in Lagos on Monday at the Nigerian Exchange Group (NGX) during the formal launch of the Initial Public Offering (IPO) of Dangote Petroleum Refinery and Petrochemicals (DPRP).
He also commended Tinubu’s leadership and said the Dangote Refinery was supporting the administration’s efforts.
“I want to thank him for taking a lot of bold steps by removing the subsidy and democratising the exchange rate…” Dangote said.
READ ALSO: Dangote Refinery IPO: SEC Warns Investors Against Fraudsters, Fake Platforms
He assured that the Dangote Group would continue working with the government to contribute to Nigeria’s development.
“So, we thank you very much for your leadership and we will continue to partner with the government to ensure that we make this country great and we make Africa great,” he said.
Dangote, a former president of the Nigerian Exchange, also expressed surprise at the transformation of the bourse, saying he had not expected it to reach its current level.
“I was the president of this exchange. Even when I was inviting people to come and help me turn the exchange around to make it a world-class exchange, I never thought this exchange would be at this level in 2026,” he said.
He revealed that a more grand ceremony would be held with Tinubu in attendance.
The refinery’s IPO, which opened on Monday, offers 4.1 billion new ordinary shares at N525 per share, with a minimum subscription of 10 shares valued at N5,250.
The offer is scheduled to close on 13 October 2026, subject to the terms of the prospectus.

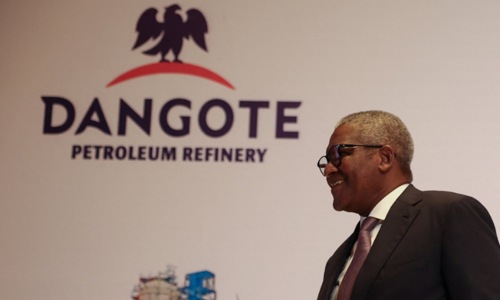
President of Dangote Industries Limited, Aliko Dangote, has described the Initial Public Offering of Dangote Petroleum Refinery and Petrochemicals as a “People’s IPO” as the N2.15tn offer officially opened on the Nigerian Exchange on Monday.
Dangote sounded the gong at the NGX trading floor in Lagos to formally open the offer, marking a major milestone for Nigeria’s capital market.
The IPO comprises 4.1 billion new ordinary shares priced at N525 per share, with a minimum subscription of 10 shares valued at N5,250.
RELATED NEWS: BREAKING: Dangote Refinery IPO Subscription Surpasses ₦1.4trn as Investor Demand Soars
The offer, which opened on September 14, 2026, is scheduled to close on October 13, 2026, subject to the terms contained in the prospectus.
Speaking after sounding the gong, Dangote said the offering was aimed at widening public participation in the ownership of the refinery.
“We fully share all our prosperity with the people. That’s why we call this ‘People’s IPO’. We know the journey has actually just started.
“It’s not only about the refinery.”
The Dangote Refinery IPO is the first refinery offering to investors on the Nigerian stock market in the 66-year history of the Nigerian Exchange.
The offer is open to retail, institutional and eligible African investors, providing members of the public with an opportunity to acquire an interest in one of Africa’s largest industrial projects.
Dangote also disclosed that the IPO was part of a broader plan by the Dangote Group to list more of its companies on the capital market.
He said the group intended to list every company that would operate under its umbrella in the future.
“We, as a group, will list every single company that will operate. I don’t know about the others, but I know our own market cap, even at a 10 times P/E ratio by 2030, should not be less than $350 billion,” he said.
The businessman added that the Nigerian Exchange would provide a platform for the group to pursue listings on other international exchanges.
“From this exchange, then we can go to any other place.
“So, Nigeria and Africa is our base. We want to make sure that we join our continent.”
The Dangote Refinery, located in the Lekki Free Zone, Lagos, has been positioned as a major investment in Nigeria’s domestic refining capacity and efforts to reduce dependence on imported petroleum products.
The opening ceremony was attended by Lagos State Governor Babajide Sanwo-Olu, NGX Group Chairman Umaru Kwairanga, the Ooni of Ife, Oba Adeyeye Enitan Ogunwusi Ojaja II, Zenith Bank founder Jim Ovia and other dignitaries.
The N2.15tn IPO will remain open until October 13, 2026, subject to the terms contained in the prospectus.
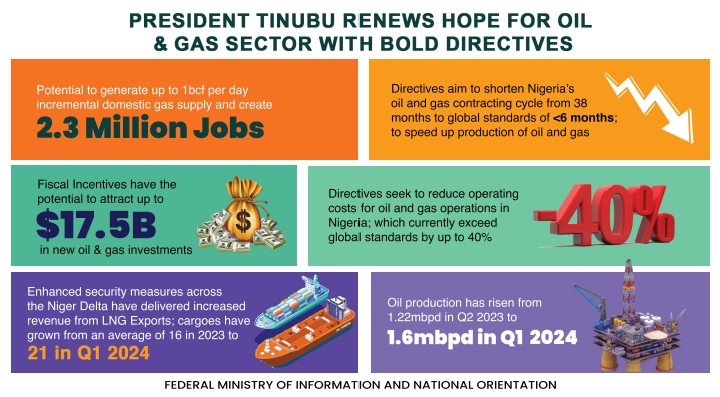
A 0.4 percent increase from the 1.67 million bpd recorded in July saw Nigeria’s crude and condensate production rise to 1,677,777 barrels per day in August 2026.
The growth, disclosed in a statement by Head, Media and Corporate Communications, the Nigerian Upstream Petroleum Regulatory Commission (NUPRC), Eniola Akinkuotu, on Sunday.
Another interesting aspect of the report is that it shows Nigeria’s consistent compliance with the Organisation of Petroleum Exporting Countries (OPEC) crude oil quota for the fourth consecutive month.
READ ALSO: Rufai Oseni Row: NiDCOM Breaks Silence on Nigerians Detained in India, Addresses Ekene’s Case
According to the regulator, crude oil production, excluding condensates, stood at 1,500,190 barrels per day in August.
The report revealed that Nigeria meeting her OPEC quota for the fourth consecutive month, reflects continued efforts by operators to restore affected production capacity and address operational bottlenecks.
The latest increase followed the resolution of operational challenges involving the Single Buoy Mooring at the Erha field, which had affected production performance in the preceding month.
The NUPRC said the restoration of normal evacuation and production operations at the asset contributed positively to the overall output recorded during the month.
The statement read, “The NUPRC attributed the modest improvement in August production largely to the resolution of the Single Buoy Mooring operational challenges at the Erha field, which had adversely impacted production performance in the preceding month.
“The restoration of normal evacuation and production operations at the asset contributed positively to overall production volumes during the period under review.”
The regulator added that production activities across most other producing assets remained relatively stable, with operators sustaining measures aimed at improving efficiency, maintaining asset integrity and reducing operational disruptions.
According to the commission, the lowest daily crude oil and condensate production recorded in August was 1.64 million bpd, while the highest stood at 1.71 million bpd.
A breakdown of production by terminals and streams showed that the Bonny Terminal recorded the highest average output during the month, accounting for 320.04 thousand bpd.
Forcados Terminal followed with 317.40 thousand bpd, while the Qua Iboe Terminal recorded an average of 171.72 thousand bpd of crude oil and condensates.
Escravos Oil Terminal posted a daily average of 131.71 thousand bpd, while Bonga ranked fifth among the leading producing terminals with an average of 92.50 thousand bdp of crude oil.
The August output represented an increase of 6,777 bpd from July’s 1,671,000 barrels per day, based on the rounded July figure. It was also 57,621 bpd, lower than the 1,735,398 bpd recorded in June.
The June figure represented a decline of about 3.3 per cent in August when compared with the latest available June production data.
The NUPRC said the August performance reflected the industry’s continued efforts to resolve operational constraints and restore affected production capacity.
It stated, “While the increase recorded in August was modest, it reflects the industry’s continued efforts to address operational bottlenecks and restore affected production capacity.
“Stakeholders remain focused on enhancing asset reliability, improving operational resilience and advancing intervention programs to support sustained production growth in the coming months.”
The regulator further emphasised the importance of timely intervention, effective asset management and collaboration among industry stakeholders in safeguarding the country’s crude oil production capacity.
Nigeria’s oil production has remained a major focus of government efforts to increase revenue, improve foreign exchange earnings and strengthen the country’s ability to meet its OPEC production quota.

Saudi Pipeline Disruption Pushes Nigeria’s Crude Beyond $115/barrel

DPRP IPO: Dangote Rings Opening Bell at NGX
Dangote Commends Fuel Subsidy Removal

Dangote Refinery IPO: SEC Warns Investors Against Fraudsters, Fake Platforms

NDC Condemns Attack on Members in Enugu, Accuses APC of Sponsoring Thugs

Dangote Calls Refinery IPO ‘People’s IPO’ as N2.15tn Offer Opens

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart