Business
Oxford Business Group signs MoU with Deloitte & Touche for 2023 economic report

By Edozie Obasi-Eze
The global research and advisory company, Oxford Business Group (OBG) is conducting research for its upcoming annual economic study of Nigeria. This is a critical time for Nigeria and the country plans to put the private sector at the heart of the next phase of its economic development. This will be explored in OBG’s forthcoming report.
The Report: Nigeria 2023 will assess the resilience of Nigeria’s economy and will highlight the sectors of the economy that are expected to drive recovery in the post-pandemic era. Sectors like agriculture, services, energy, and information technology (ICT) among others will be analysed in detail.
Read also>>>Nigeria’s Next President Must Be Brave About Power Sector – CEO, Century Power
The report will also examine the private sector’s role in unlocking the benefits of key legislation and initiatives, with specific focus on the Petroleum Industry Act and the African Continental Free Trade Area Agreement. It will evaluate the private sector’s capacity to plug lingering gaps in key industries by deploying capital to supplement ongoing governmental efforts. The report will also contain interviews conducted with public officials such as the Central Bank Governor, Godwin Emefiele, and key private sector leaders, such as the Chief Executive Officers of MTN and Microsoft Nigeria/West Africa.
OBG has signed a new memorandum of understanding (MoU) with Deloitte & Touche (Nigeria). Deloitte, a member firm of Deloitte Touche Tohmatsu Limited, is a leading professional services organization that provides, audit & assurance, tax & regulatory, consulting, financial advisory and risk advisory services.
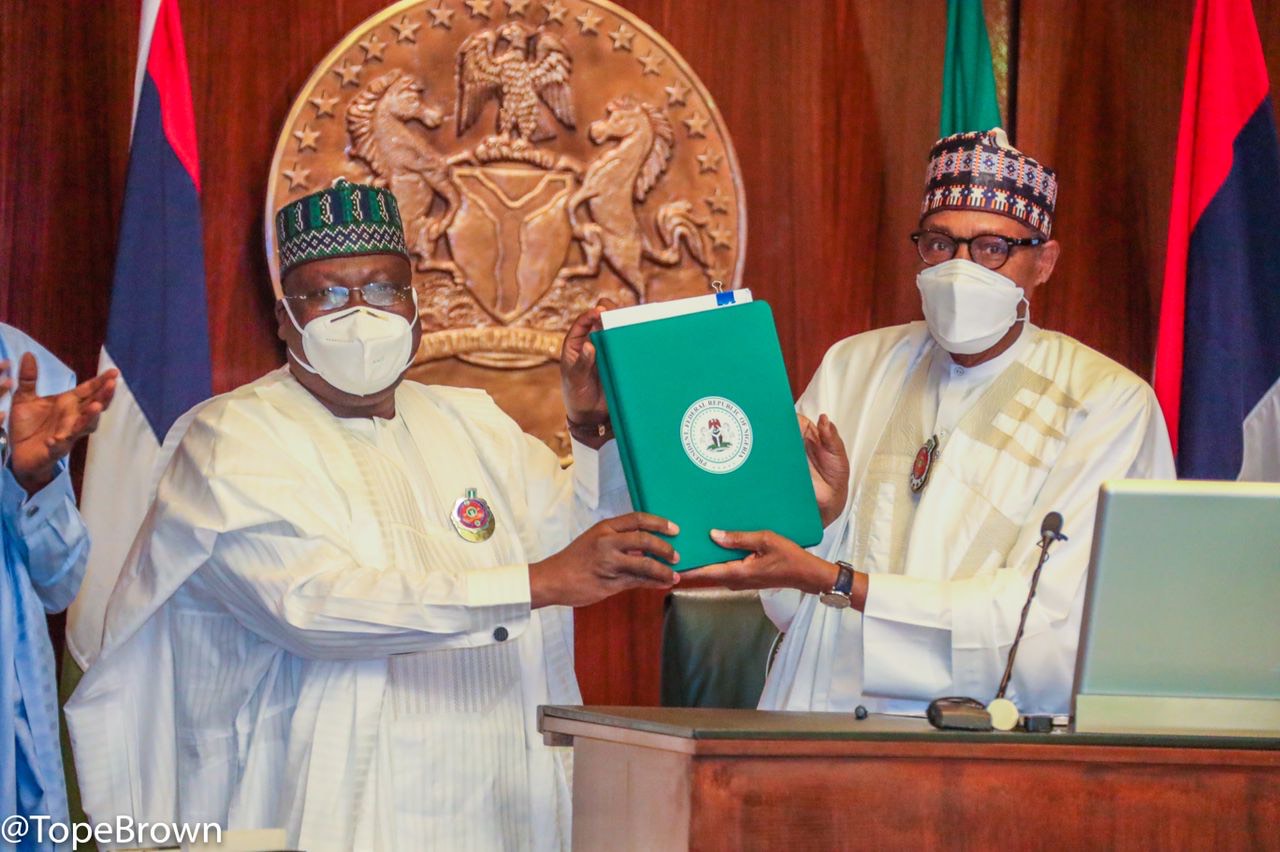
Under the MOU, Deloitte Nigeria will work with The Report: Nigeria 2023’s editorial team, under the direction of the Country Editorial Manager to research out and complete the Tax Chapter.
The MoU was signed by Wen Qian Chang, Country Director, OBG, and Yomi Olugbenro, West Africa Tax Leader, Deloitte & Touche (Nigeria).
After the signing, Olugbenro commented that Nigeria is grappling with the consequences of economic recession, inflation, infrastructure deficits, and unemployment. He also stated that the federal government has increased its debt obligations to N20.144 trillion as of March 2022, pushing its debt to GDP ratio to 23.3%, and has imposed strict foreign exchange controls.
“However, the economic outlook is buoyed by higher oil prices and increased post-covid remittances, “he said. “Deloitte leverages different expertise across the firm which include industry specialists, accountants, lawyers, supply chain specialists, auditors etc., to provide evidence-based research and analysis in support of policies that leverage trade integration or spur economic growth and development in emerging markets.”
Deloitte and OBG have partnered previously, for the Tax Chapter in the 2017 report. Delighted with the renewal of this partnership, Chang said that this alliance would help the international investment community have access to well researched information with a view of driving foreign investment and economic growth.
“We once again are looking forward to working with Deloitte & Touche (Nigeria). Their in-depth knowledge of the country’s tax framework will be invaluable for investors weighing up Nigeria’s opportunities amid the changing political landscape,” said Chang.
The Report: Nigeria 2023 will mark the culmination of more than a year of field research by a team of analysts from OBG. It will be a vital guide on the many facets of the country, including its macroeconomics, infrastructure, banking, and other sectoral developments. OBG’s publication will also contain contributions from leading representatives across the public and private sectors.
The Report will be available online and in print. It will form part of a series of tailored studies that OBG is currently producing with its partners, alongside other highly relevant, go-to research tools, including ESG Intelligence and Future Readiness reports, country-specific Growth and Recovery Outlook articles and interviews. Ok


Guinness Nigeria Plc is focused on sustaining growth through wider product availability, commercial expansion and disciplined pricing.
Managing Director and Chief Executive Officer, Guinness Nigeria, Girish Sharma made the disclosure in an interview with CNBC Africa, in which he outlined the priorities expected to shape the company’s performance in the coming quarters.
According to Sharma, the company would keep focusing on making its products more accessible to consumers while strengthening its presence across markets and distribution channels.
“The strategy has always been growing by being available at more places, having our beer, having our products cold in a lot of places and ensuring that we are playing at the right price points,” he said.
READ ALSO: Osun Tackles Sanitation with Adhoc Road Sweepers
Sharma explained that the company’s approach was centred on expanding its reach rather than relying on price increases to drive growth.
He said Guinness Nigeria had increased the number of locations and cities in which its products were available, alongside growth in its distributor network.
He maintained that the company’s commercial expansion is part of a longer-term plan that will continue over the next three to five years.
“In terms of number of touch points where we’re available to the Guinness Nigeria products, number of cities where we’re available today, number of distributors that we have that distribute our products today, on every single count we have grown multi-fold,” Sharma said.
He described the expansion as a significant undertaking for the business, noting that the effort began with his first 100-day plan and remains a key part of the company’s direction.
Sharma also pointed to operational discipline and improvements made over the past year as important foundations for the business. He said earlier decisions to address the balance sheet, adjust pricing and make fundamental corrections were now supporting the company’s growth trajectory.
He added that teams across operations and procurement were working to keep price increases to a minimum while increasing output, while a more stable currency environment had also been helpful.
Looking ahead, Sharma said the company would focus on maintaining consistency rather than promising a particular growth rate for the next quarter.
“I’m not here to stand and say that we’re going to do better than the third quarter, but what I see is we will be consistent in terms of delivering healthy results,” he said. “Consistency is the word.”
He also highlighted the importance of the final quarter of the year to the beverage industry, citing increased consumer activity around the festive season. Guinness Nigeria, he said, had strategic partnerships planned across the period, with some extending into the first quarter of the following year.
Sharma said the company’s broader ambition was to build a stronger business capable of funding its growth, rewarding shareholders and sustaining performance over time.
“The business is sturdy, business is strong, business is good, and I’m confident that we will continue to grow sustainably,” he said.
His comments underline Guinness Nigeria’s focus on extending its market reach, strengthening execution and building consistency as it pursues its longer-term growth ambitions.
Nigeria must be surefooted to attract the right investment to harness her full potential in the oil and gas industry.
At the 32nd Nigerian Economic Summit (NES) during a panel session titled, “Unlocking Nigeria’s Oil Potential: The Push for More Oil”, in Abuja, the Managing Director and Chief Executive Officer of NLNG, Adeleye Falade, decried the lack of certainties in the investment environment in Nigeria’s oil industry.
He traced Nigeria’s inability to attract sufficient financing for major oil and gas projects to uncertainties over investment terms, project execution and guaranteed markets for output.
According to Falade, investors and lenders must be confident that contractual agreements will be honoured, projects will deliver as planned and buyers will be available to purchase production before committing billions of dollars to capital-intensive energy developments.
READ ALSO: OTL Africa Urges ECOWAS to Adopt Regional Standardisation
He cited the financing of NLNG’s Train 7 expansion as evidence that investment certainty, a proven delivery record and credible commercial agreements could unlock substantial funding, even under challenging global economic conditions.
Falade explained that projects requiring huge upfront capital and 20 to 30 years to recover investments depend on confidence that the terms underpinning them will remain stable throughout their lifespan.
According to him, lenders assess not just the quality of an oil or gas resource but also the durability of the investment framework, the predictability of future earnings and the capacity of project sponsors to meet their obligations.
Falade pointed to the $3 billion in external financing secured from 31 local and international financial institutions for Train 7 in 2020, at the height of the COVID-19 pandemic, as proof of the importance of a credible investment proposition.
The project is being financed through a combination of internally generated cash flows and external funding, underpinned by NLNG’s record of developing six operating trains and repaying the loans used to finance their construction.
He said that track record gave lenders tangible evidence of the company’s capacity to execute complex projects and honour financial commitments, reducing the uncertainty that often discourages investment in capital-intensive developments.
He noted that each successful expansion strengthened NLNG’s credibility and positioned it to secure subsequent financing on more competitive terms.
He identified three fundamental questions that lenders seek answers to before financing major energy projects: “Who buys the product? Who carries the risk? Who stands behind the project?”
For NLNG, he said, long-term sales and purchase agreements, some spanning 20 years, provide the commercial foundation required to secure funding before a final investment decision is taken.

A call has gone to West African countries to adopt uniform fuel specifications, strengthen testing capacity, address infrastructure gaps and improve enforcement systems to facilitate more effective regional petroleum trade.
This formed the bulk of the submission of petroleum regulators at a panel session during the 20th OTL Africa Downstream Energy Week that ended in Lagos.
It is the considered opinion of the regulators that inconsistencies in standards across the region remain a huge disservice to fair competition. Therefore, they expressed a common view that putting in place an acceptable standard will ensure a harmonised fuel quality, improve infrastructure and stronger regulatory coordination which will facilitate cross-border trade and reduce market barriers across the region.
Speaking at the session themed: “Regulatory Convergence in African Oil and Gas Markets,” the Authority Chief Executive (ACE), Nigerian Midstream and Downstream Petroleum Regulatory Authority (NMDPRA), Rabiu Umar, argued that differences in fuel specifications across countries made it difficult to compare products and ensure fair competition.
READ ALSO: NUPRC Resorts to Technology to Reduce Emissions by 60%
For instance, he explained that the disparity between diesel specifications of 50 parts per million (ppm) and 1,500 ppm, presents a complication in efforts to harmonise standards across the region.
To this end, the ACE said the sub regional countries needed common product specifications and coordinated production rules to facilitate trade and promote competition.
Umar also advocated the establishment of a West African reference price for petroleum products, saying regional markets needed to strengthen trade among African producers.
On his part, the Chief Executive Officer of Ghana’s National Petroleum Authority (NPA), Godwin Tameklo, said that inadequate infrastructure was a major constraint to regional petroleum trade.
According to him, countries needed to address infrastructure gaps, regulatory differences and market constraints to improve the cross-border movement of petroleum products.
For instance, he disclosed that Ghana’s port and storage facilities could not always accommodate volumes delivered by larger vessels, forcing operators to consider smaller shipments or alternative arrangements.
Tameklo also stressed the need for clear implementation timelines to ensure that regional harmonisation initiatives translated into practical results.
In a similar vein, the Director of Water, Petroleum and Electricity at The Gambia’s Public Utilities Regulatory Authority (PURA), Musa Njie, highlighted the importance of laboratory facilities in testing petroleum product quality.
Njie identified the absence of a laboratory for petroleum product testing as one of the challenges facing The Gambia, and stressed the need to strengthen national quality assurance systems.
He said that harmonisation efforts should protect public health and the environment while improving market efficiency.
Njie also called for stronger coordination between regional frameworks and national regulatory institutions to ensure effective implementation of agreed standards.

‘I’ve Been a Threat to Gov’t Since Age 20’ – Sowore

Guinness Nigeria CEO Shares Sustainable Growth Strategy

Tinubu Sends Six NMDPRA Executive Director Nominees to Senate, Retains Three
Osun Tackles Sanitation with Adhoc Road Sweepers

NLNG: Nigeria’s Oil Ambitions Require Investor Guarantees
OTL Africa Urges ECOWAS to Adopt Regional Standardisation

Trump’s Family Unveils New Cryptocurrency Platform
Senate Denies Receiving Petitions Against Tinubu’s Ambassadorial Nominees

Dangote Cement Lights Up Benue Host Communities With CSR Initiatives

Reps Recommend 3-year Jail Term For Aviation minister

Tems Sets New Record On Billboard Hot 100 Chart